
Background
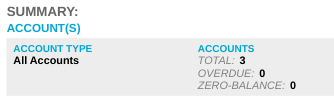
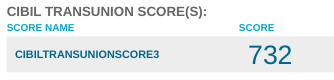
Chetan approached us because an urgent personal-loan application had been rejected. His CIBIL report, pulled on 10 September 2026, contained a ₹5,20,000 commercial-vehicle loan that he says he had never taken. That report listed three accounts and a score of 732.
The problem was not a debt he needed to settle. An incorrect account was being read as part of his borrowing history, preventing the lender from progressing with his application.
What the analysis found
We reviewed his concern and the documents he provided. The issue was account ownership: the loan was not his. Chetan says Supraja explained why an incorrect entry can appear on a report and collected the documents over WhatsApp. He also credits his friend Srinidhi for connecting him with her.
The approach
On the first day, we onboarded Chetan and raised a grievance with the lender’s higher authorities. We also contacted the CIBIL team about the incorrect entry and followed up for a resolution.
- Saturday: Chetan approached us and the case was taken up.
- Tuesday: CIBIL indicated that the issue would be resolved within two days.
- By Friday: the incorrect loan account had been removed.
The turnaround confirmed for this engagement is five working days. The reports were pulled on 10 and 18 September 2026; those are evidence dates, not the dates of first contact or the precise moment of correction. The weekday sequence above comes from the consultant’s account.
The outcome
Chetan’s personal loan was subsequently approved. In the video, he says the loan was credited two days after the correction.
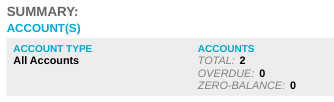
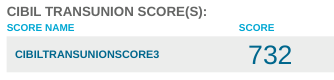
The report pulled on 18 September 2026 no longer lists the commercial-vehicle loan. The other two account identifiers match across both reports, and the total falls from 3 accounts to 2. The score remains 732 → 732. The result was a corrected borrowing record, with no score increase between these two report pulls.
Report evidenceCompare the before and after reports
Choose a report to view its extracts
The total account count
The score stayed the same
The disputed entry in the before report
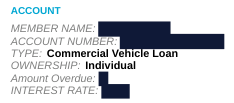
Crops from the client’s CIBIL reports, pulled 10 and 18 September 2026. The commercial-vehicle account is present in the first report and absent from the complete account list in the second; the two remaining account identifiers match across both reports. The entry shown above is from the before report only. Personal identifiers and financial values are cropped out or redacted; lender and account details are masked. The report dates establish when the correction was visible, while the five-working-day engagement timeline comes from the consultant’s account and client confirmation.
Hear Chetan’s account
Published with his written consent.
Five working days, in his experience
Chetan describes finding the unfamiliar account during loan verification, the follow-up from Supraja and his loan being credited after the correction.
The audio is Kannada. The subtitles and full text below are an English translation using Sarvam, rather than words originally spoken in English.
The video describes this client’s experience. It is not a promised turnaround or loan-approval commitment.
Read the full English translation ↓Full English translation of the Kannada testimonial
Hi, my name is Chetan. A few days ago, I said I wanted to take a loan, so I gave all the documents to a finance company and sent them to get verification done. While the finance people were doing the document verification.
They informed me that in your name, in CIBIL, in your name, in CIBIL, it is showing some commercial vehicle loan of ₹5,20,000. And that ₹5,20,000 is from the commercial vehicle loan.
They also said that they wouldn't be able to issue the loan until it was removed from your CIBIL. Actually, I hadn't taken any kind of loan. How did ₹5,20,000 come into my account? How is it showing in my CIBIL?
I got tensed. And I hadn't sent my documents to anyone for loan purposes. This is the first time I'm applying for a loan, and when I gave the documents to them, by mistake, I don't know if it was by mistake or what, but in CIBIL, this.
They informed me that it was showing ₹5,20,000. I got a little tense. After that, I had a friend named Srinidhi. He is very close to me. When I called him and told him, sir, this is what happened, ₹5,20,000 is mistakenly showing in my CIBIL, I said.
They immediately said, "Don't be afraid, these kinds of cases happen quite often. I have handled many cases like this. I will hand over your case to someone in my team. They will call you," they said.
Next, I got a call. When I received the call and they told me, there was someone named Supraja. They called and asked what the matter was, and after taking complete details from me, they told me why this is happening.
Explain in detail why it reflects in CIBIL and all. They immediately got all my documents WhatsApped to them. Later, in the meantime, I had asked someone else.
What is this that has happened, how to get it removed, they said it would take a minimum of fifteen to one month, working days, for it to be removed. Oh, fifteen to one month, I was very tense. Later, Supraja Madam, she very.
With responsibility and very well, they communicated with us, got all the documents from us, and within a minimum of 5 working days, they resolved our query. It was like, they called immediately.
What happened? Did you receive any mail? And did you get any reply from what we sent? They called three or four times every day and pushed the issue until it reached a certain point. Later, when I saw the mail came and it was resolved, it was resolved in about five days. Actually, I also had an emergency need.
So, because I contacted them, it would have taken fifteen to twenty days outside. But for me, my work was finished in just five working days. After that, my loan was also credited to me in two days. Actually, I would like to thank both Supraja and Srinidhi sir from Kenstone company. Thank you sir. Thank you ma'am.
Translation note: when recalling an estimate given elsewhere, Chetan says “fifteen to one month”; that phrase is unclear and is retained here. Later he says fifteen to twenty days. Neither is Kenstone’s estimated turnaround. His own outcome is stated as five working days.
Why this case matters
A wrong loan on a CIBIL report is an ownership dispute. It needs investigation and correction, rather than repayment of an account that is not yours. CIBIL’s dispute guidance explains that it sends the dispute to the reporting credit institution and needs that institution’s confirmation to change the information.
If you need to report a wrong loan in CIBIL, start with the account details on your report and the supporting documents. Our CIBIL dispute and escalation guide explains the process. You can raise a dispute yourself; our personal credit repair service provides a written review before payment if you want help.
Accurate negative history cannot be removed. This was correction of an account that did not belong to Chetan. Timelines vary, and the lender makes its own decision on any new loan.