Home · News & events · BNI Bangalore Members Day 2026
News & events · BNI Bangalore Members Day 2026 · Stall M56
What BNI Bangalore’s members asked us about credit.
Close to 200 members registered for a free credit assessment at our stall on 29 August — one in five of everyone who walked through Ebisu that day. The questions they asked are the real story.
 By Harish Krishnamurthy, Co-founder · Vice President, BNI UNO Bengaluru ↗Published 8 September 20266 min read
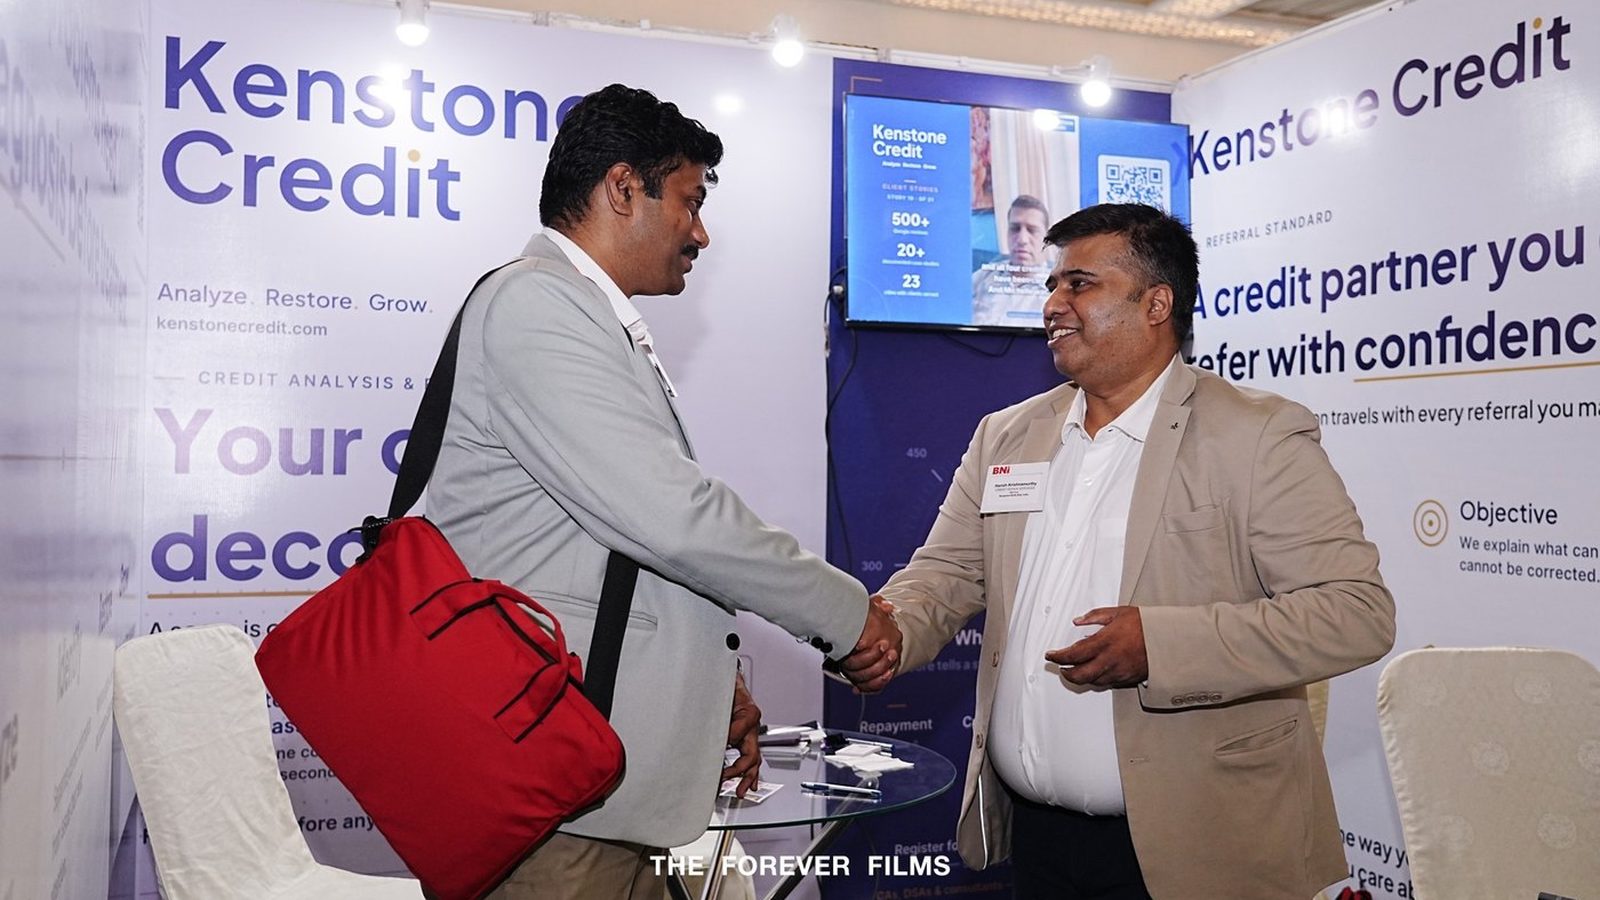
Close to 200 members registered for a free credit assessment at our stall on 29 August — one in five of everyone who walked through Ebisu that day. But the number I keep thinking about isn't 200. It's the questions. The same handful came up again and again, from members with excellent credit as much as from members with problems — and they're questions almost nobody answers plainly. The answers are below. The story of the day is first, because it's a good one.
Before
The decision, a year early.
I attended Members Day 2025 as a visitor. Walking that hall — a thousand business owners, every one of them a lender's customer, a borrower, or a referrer of both — I made up my mind that Kenstone Credit would have a stall the following year. When the 2026 edition was announced, we signed up within the first few days.
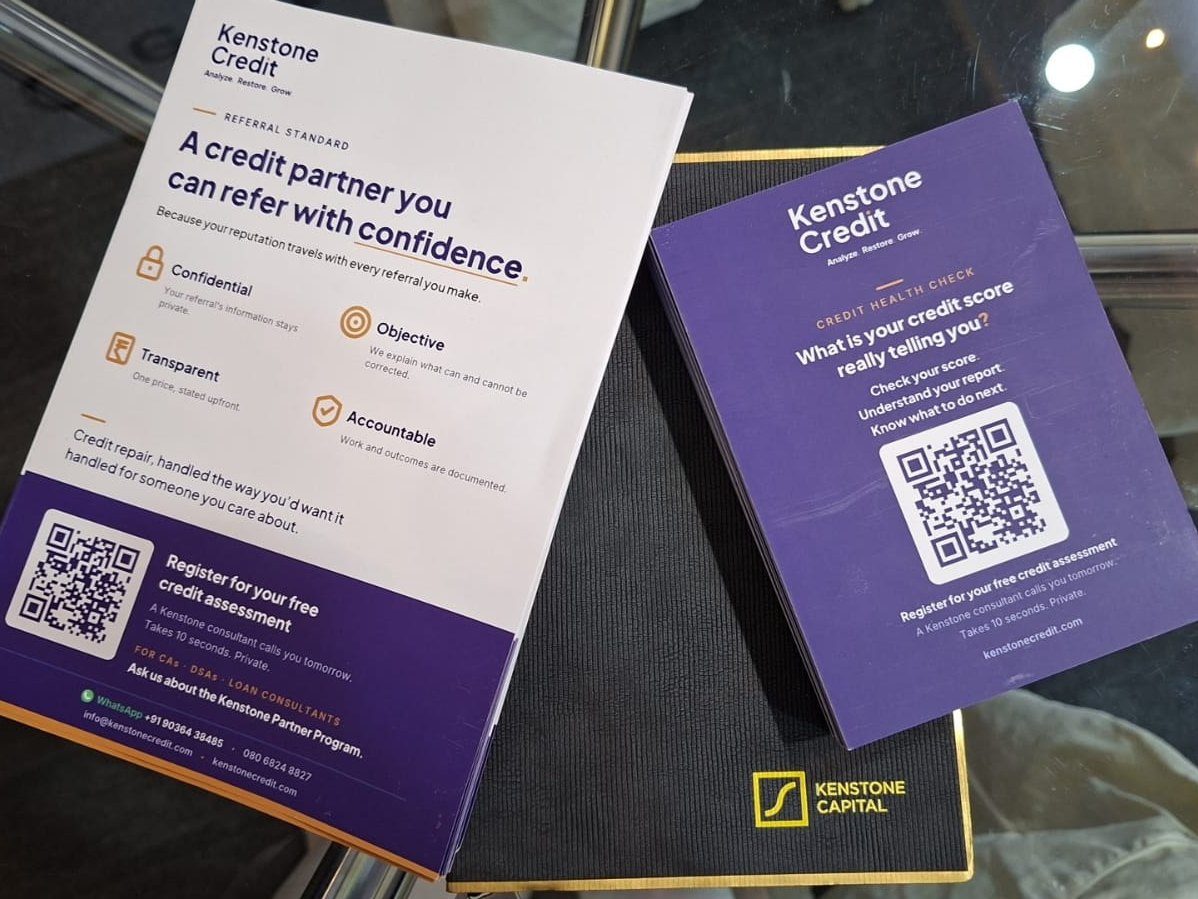
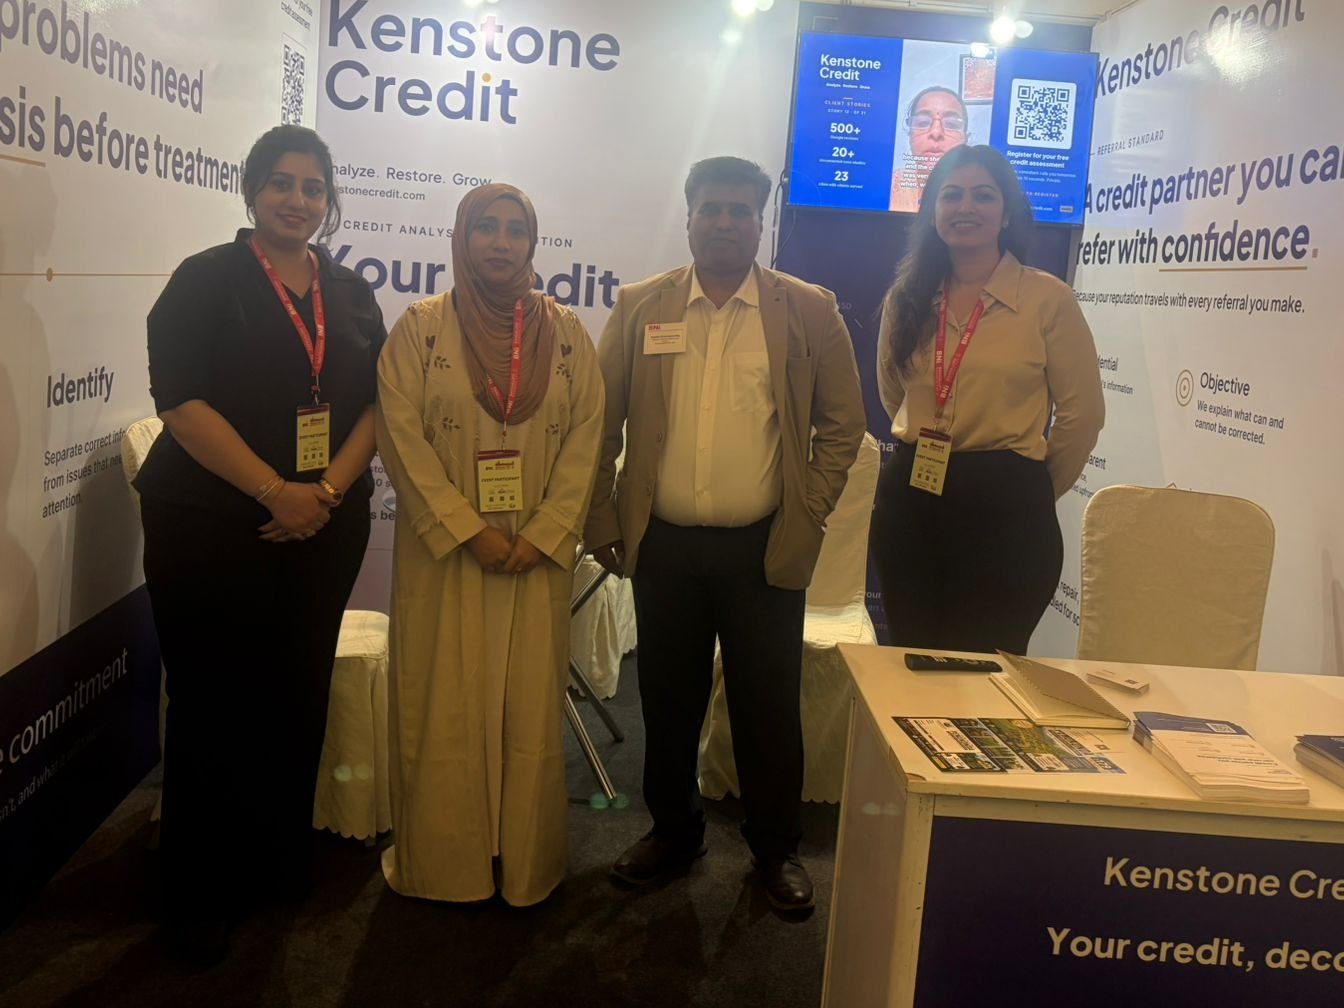
The planning started three weeks out: the stall design and branding, who would join me, and how we'd talk about what we do in a room where most people have never needed a credit consultant — and know several people who do. We used AI tools, including Claude, to help plan, produce and pressure-test the stall materials, and three of our consultants — Akshatha Shetty, Sumayya Khanan and Rabia Basri — agreed to give up a Saturday to run the stall with me.
A word for the BNI Bangalore leadership team, who made the exhibitor side of this remarkably smooth. Dr Sudhir Anand, Area Director (BNI profile ↗), and Johncey George, Senior Director Consultant (BNI profile ↗ · LinkedIn ↗), and their team shared every detail of the event well in advance and ran a coordination WhatsApp group where exhibitor questions were answered within minutes. Exhibiting is easy when the organisers treat you as a partner — and they did.
29 August
The day.
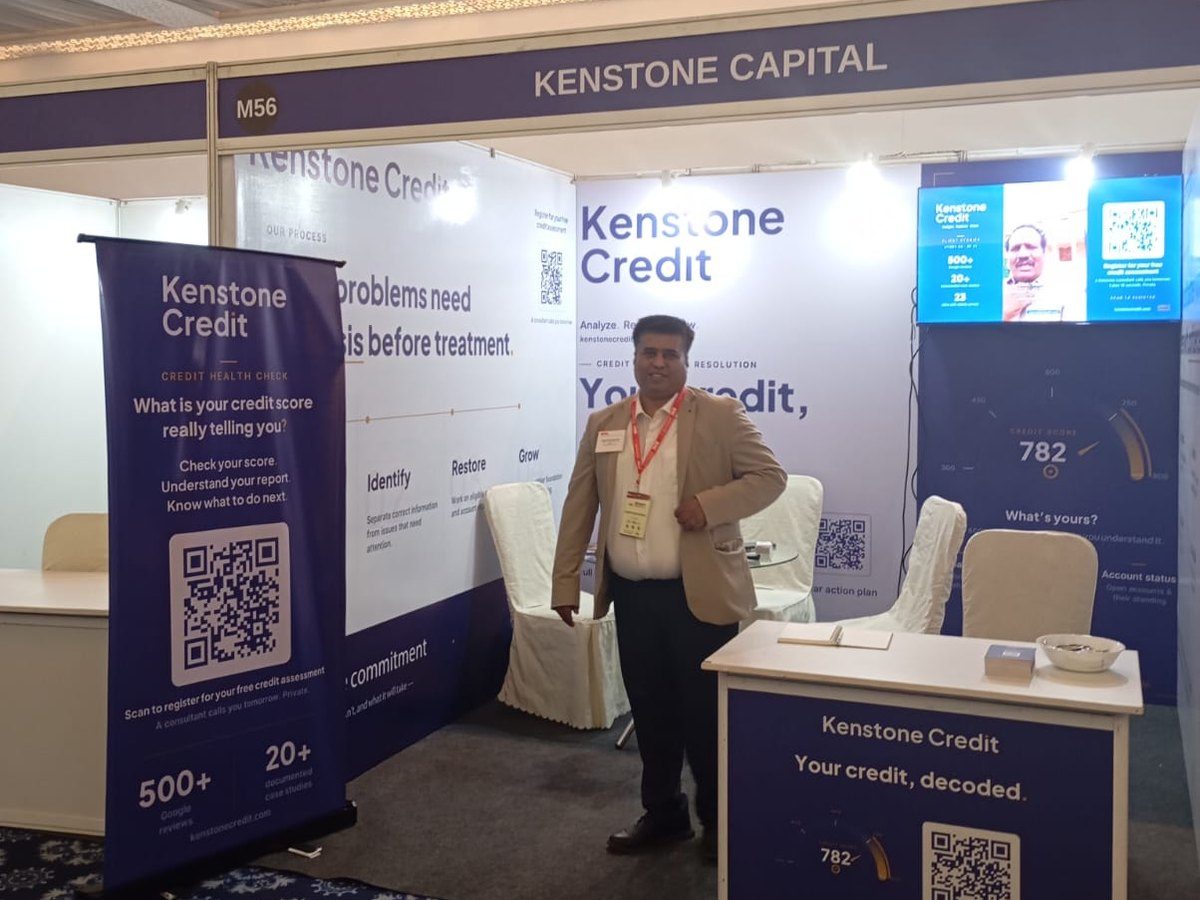
We started at 6:00 AM and were at Ebisu by 7:30 — flyers arranged, the table set, the TV wired to play our client testimonial videos on a loop with captions (the hall is loud; the captions did the talking). By the time the doors opened, Stall M56 was ready. The videos on that screen are on our site — 25 clients, in their own words.
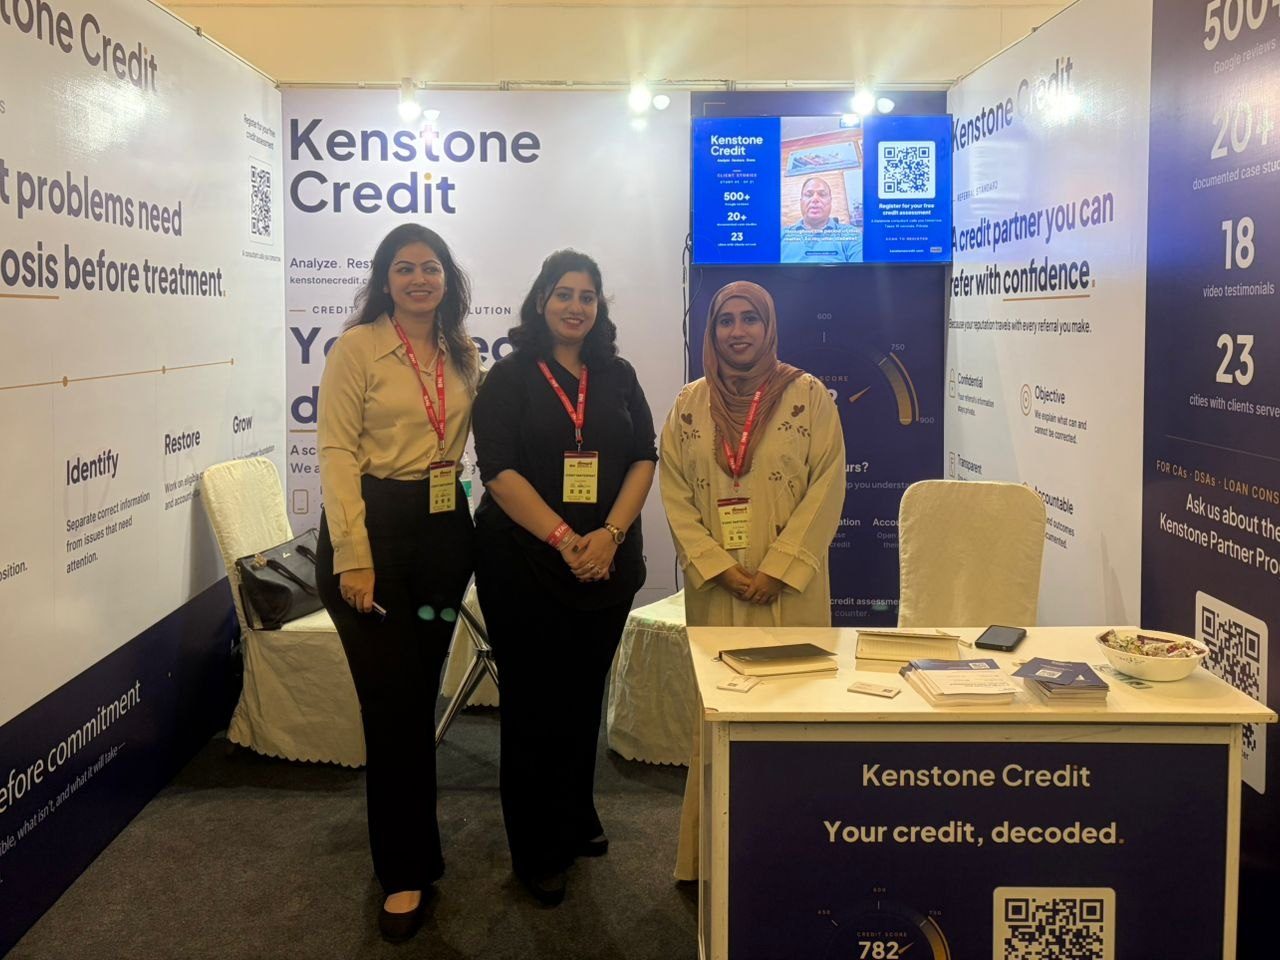
Then I largely left it. Rabia, Sumayya and Akshatha ran the stall on their own for most of the day while I was in the hall meeting members and explaining the work. That is harder than it sounds. A stall at a thousand-person event is eight hours of standing, of opening a conversation with a stranger every ninety seconds, of registering people in the ten seconds they'll give you, and of answering the same hard question — “do I still have to pay?” — with the same patience at 5 PM as at 10 AM. They did all of it, rotated stations without being asked, kept the registration count moving through the peak hours, and handed the difficult conversations to each other with a grace that members noticed and mentioned to me.
And the stall was only half their work. Every one of those registrations became a call the following week — a real assessment, opening with the member's situation and not with ours — and Akshatha, Sumayya and Rabia made those calls too. The promise on our wall was a named consultant calls you tomorrow. They are the names. I am proud of them, and grateful.
Our promise on every wall was simple: register with just your phone number, and a named Kenstone consultant calls you tomorrow with a free assessment. Close to 200 members took us up on it. Those calls began the following working day and are still running as I write this — each one opening with the member's situation rather than our services, which is the only version of a “free assessment” worth offering.
Seven questions
The questions members actually asked.
By mid-afternoon a pattern had set in. The first kind of visitor had a specific problem they had lived with for years — a status on a report that had blocked something, and no clear explanation from anyone. The second had no problem at all, an excellent score, and stopped anyway because someone they knew had been refused a loan that year. The third owned a business and had never seen a commercial credit report, only a personal one, and did not know the two were different documents with different scoring. Short answers here; each links to the fuller guide in our Credit Library.
“If I check my CIBIL score regularly, does it reduce my score?”
No. Checking your own score or report is a soft enquiry and has no effect on it — check it every month if you like. What can affect your score are hard enquiries: each time you apply for a loan or card and the lender pulls your report. Several of those in a short window signal credit-hunger to lenders. The confusion comes from lumping both together. More: Enquiries on your CIBIL report →
“The bank has written off my loan on the report. Do I still have to pay?”
Yes. A write-off is the bank’s accounting decision — it has stopped counting your loan as a performing asset. It is not a waiver, and the debt does not disappear. The bank, or a collection agency it assigns, can still pursue it, and the “Written Off” status stays on your report and blocks most new credit until it is resolved — usually by paying or settling and then getting the status updated correctly. More: What “written off” means in your CIBIL report →
“What’s the difference between a commercial CIBIL report and my individual credit report?”
They are different products for different borrowers. Your individual report carries a score from 300 to 900 on your personal loans and cards. A commercial credit report covers a business entity — a proprietorship, partnership, LLP or company — and carries a CIBIL MSME Rank (CMR) from 1 to 10, where 1 is the lowest risk. If you own a business, both reports matter, and they can tell very different stories. More: Commercial credit reports and CMR explained →
“What CMR rank do banks actually want?”
Most lenders read CMR 1–3 as strong, 4–6 as the watch zone where the comfort gate sits — usually around 5–6 — and 7–10 as distress. Unlike the individual score, the rank moves on a small number of factors — repayment record, utilisation of existing limits, and the age and mix of facilities — which means it can be improved with specific, deliberate steps. More: What each CMR rank from 1 to 10 means →
“Is “settled” the same as “closed”?”
No, and lenders read them very differently. Closed means you paid what was due. Settled means the lender accepted less than the full amount and closed the account — a mark that stays visible for years. If you paid in full and the report still says settled, that is a correction case. More: Loan settlement and your CIBIL report →
“Which bureau is the correct one — CIBIL, Experian, Equifax or CRIF?”
All four are correct, and they do not always agree. Lenders report to different bureaus at different times, so your four reports can differ — and a lender can pull any of them. When something looks wrong, it needs correcting at every bureau that carries it, not just the one you checked. More: CIBIL vs Experian, Equifax and CRIF →
“My credit is fine. Why should I care?”
Then this is not about you. Every member with excellent credit knows someone — a client, a relative, a fellow member — whose loan was rejected this year. That is who we exist for, and it is why we run a Partner Program for CAs, DSAs and loan consultants: your clients handled by a named consultant, documented from first call to closure, so the referral reflects well on you. More: Partner with us →
The reel
Twenty-one seconds of the day.
The recap reel from Stall M56 — the stall, the team, the members, the counter. Twenty-one seconds; if you were there, you may be in it.
Send this to the member who asked you about a rejected loan this year — the seven questions above are the ones they'll recognise.
Video and photos: The Forever Films.
Afterwards
What we'd do again.
Register first, talk second — the ten-second registration was the day's best decision, because a member who registered and left is a call, and an impressed member who never registered is a memory. Captions on the TV, because the hall drowns sound. The named-consultant promise, kept the next morning. And one thing we'd change: we designed the stall for the crowd we expected, and the crowd was smaller than expected — next year we'll spend less on walls and more on the two things that actually converted: the registration counter, and the people behind it.
The stall belonged to Akshatha, Sumayya and Rabia. Thank you, BNI Bangalore. See you at Members Day 2027 — we've already decided.
If you registered at the stall and haven't heard from us, or if any question above is yours: register for a free credit assessment — a Kenstone consultant calls you the next working day. No fee, no obligation, and we'll tell you what can and cannot be corrected before you decide anything.
Rank worse than your books deserve?
One free analysis of your commercial report tells you what is driving the rank and what is correctable — before any payment.
080 6824 8827 or WhatsApp us — replies in minutes