
Background
Santhosh lives in Bengaluru. He applied for a commercial vehicle loan, and the bank turned him down. The reason it gave: his CIBIL report showed several active loans, which made him look over-borrowed.
He had no such loans running. He had not seen the entries the bank was reading, so he came to us to find out what his report said and why.
What the analysis found
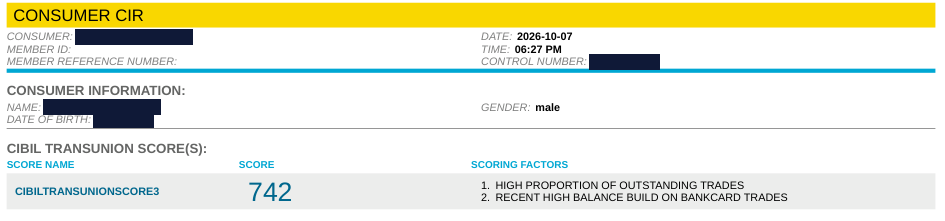
A wrong loan showing in CIBIL was the whole problem. His CIBIL report pulled on 7 October 2026 (score 742) listed five Shriram Finance commercial vehicle loans. Santhosh confirmed he had taken one of them.
- His own loan: opened 3 June 2022 and closed 10 December 2024.
- Four that were not his: opened 6 June 2023, 25 August 2023, 4 January 2024 and 24 July 2024, all still open and last reported on 16 September 2026, with about ₹6.3 lakh outstanding between them. The January 2024 account also showed ₹28,906 overdue, at 43 to 58 days past due from June to September 2026.
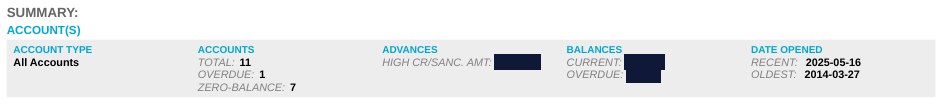
Those four accounts made up the entire outstanding balance on his report, and the only overdue account on it. A lender reading that file saw four vehicle loans running and one falling behind. None of it was his.
The approach
Supraja raised formal grievances with TransUnion CIBIL and with Shriram Finance, disputing the four accounts as not belonging to Santhosh. She then followed up by email with both, steadily, until the reporting was corrected.
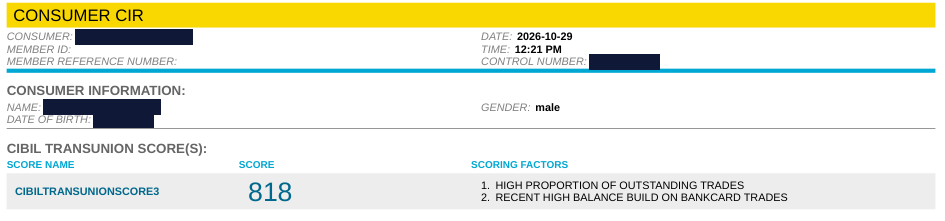
The dates on this page are the two report pulls, 7 and 29 October 2026; they are evidence dates, not the dates the engagement began or ended.
The outcome
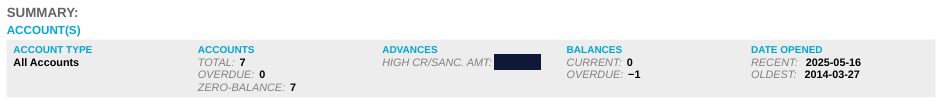
On the report pulled on 29 October 2026 (score 818), the four open Shriram Finance accounts are gone. The report lists seven accounts instead of eleven, the outstanding balance is ₹0, and no account is overdue. His own Shriram loan, closed in December 2024, is still there, as it should be.
After the correction, Santhosh received the sanction letter for his commercial vehicle loan.
Three honest notes. First, Supraja’s writeup counts six Shriram accounts with five removed; the 7 October report shows five, of which four were removed, and this page follows the report. Second, one other account changed between the two pulls: an auto loan on which he is a guarantor gained its December 2021 closing date. So we do not credit all 76 points to the removal alone. Third, the reports do not say why the four accounts were reported against him, and we do not guess.
Report evidenceCompare the before and after reports
Choose a report to view its extracts
CIBIL score and report date
Account summary
Shriram Finance accounts
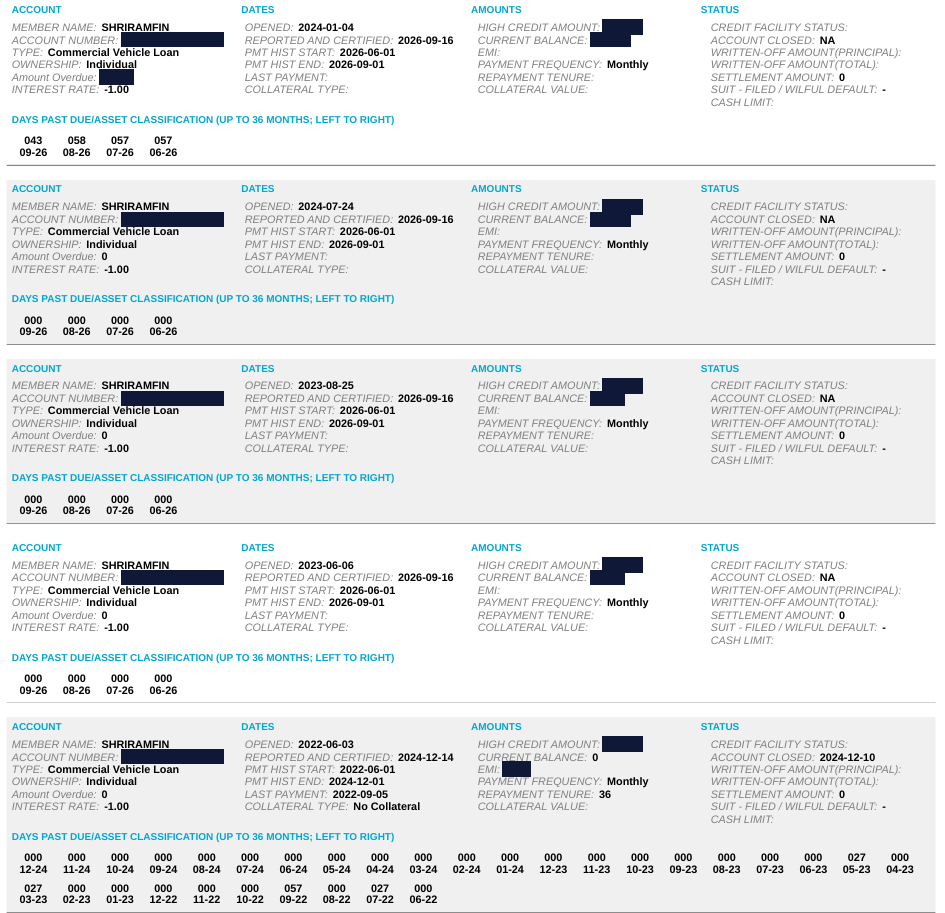
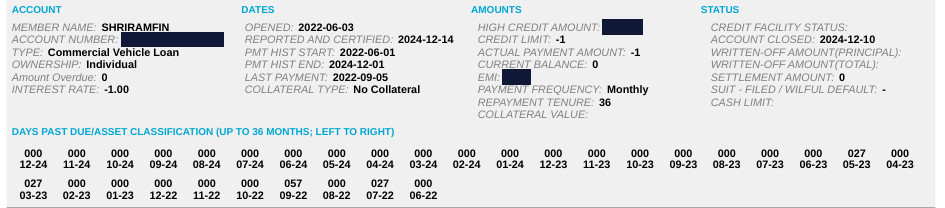
Crops from the client’s CIBIL reports, pulled 7 and 29 October 2026. The before image stacks all five Shriram Finance account blocks from the 7 October report; the after image is the only Shriram Finance account on the 29 October report. Account numbers, amounts, the control number, his name and date of birth are redacted; dates, statuses, days past due and scores are as reported.
His review, in his words
Good Advising,
Public Google review on our Bengaluru profile, quoted as written · view the original screenshot →
Why this case matters
A good score can sit on top of a wrong report. 742 is not a bad score, and the loan was still refused, because the lender read the accounts, not just the number. Check every account on your report, not only the score at the top. Our guide to a loan that is not yours on CIBIL shows how to spot one and what to collect.
Dispute with the lender and the bureau together. The lender reported these accounts and only the lender can confirm they are not his; the bureau runs the dispute. Raising both, in writing, and following up until the report changes is what moved this one. The CIBIL dispute and escalation guide sets out the routes.
What is accurate stays. His own Shriram loan, repaid and closed, is still on the report, and so are the late months in its history; only the accounts that were not his came off. Accurate negative history cannot be removed. If your report shows a loan you never took, our personal credit repair service gives you a written review before you pay.