Case studies · Personal · Bengaluru · account not his
Home · Case studies · Axis card not his, suppressed
A credit card that was never his: Axis Bank suppressed the account after document verification

Background
Ayaz Pasha is from Bengaluru, and he came to us because he could not get a loan. His CIBIL report, pulled on 8 August 2026, showed a score of 653 and, at the top of the accounts section, an Axis Bank credit card reported as opened in April 2006 with a Credit Facility Status of Written-off. The payment-history column on that card had been counting days past due upwards month after month. Any lender reading the file saw a written-off card first.
A written-off status is one of the heaviest marks a report can carry. It does not expire on its own, and the only honest routes out are paying what is owed and having the lender re-report, or showing that the entry should never have been there. Which route applied here turned on one question: whose card was it?
What I found first — and why it was not the end of it
When Ayaz first approached me, I read his report and checked the Axis Bank card against the bureau's own record of him. The account's details matched his KYC information there. On that basis I did what the report supported: I requested the foreclosure amount from the bank and advised him to pay it so the overdue status could be resolved.
Ayaz told me the card was not his, and that he had been struggling with this for a long time. He said it more than once. A bureau match is strong evidence, but it is the bureau's record, not the bank's file — and a client who keeps insisting, with nothing to gain from a lie, is a reason to look further rather than to close the conversation.
The approach: verify with the bank, not the bureau
Rather than proceed on the CIBIL record alone, I took the question to the Axis Bank nodal head. I shared Ayaz's PAN card, his Aadhaar card and his CIBIL report, and explained the position plainly: the account matched his KYC details in the bureau's record, and the client denied owning the card. I asked the bank to verify the account against his documents and, if it was genuinely his, to provide the original credit card application form as proof of ownership.
That request is the whole method. A bureau can only hold what a lender reports; it cannot tell you whether the lender's own records tie the account to the person. The application form is the document that does. Either the bank produces it, and the account is his, or it cannot, and the entry has no business on his report.
The outcome
After reviewing the documents, Axis Bank confirmed that the credit card account did not match Ayaz's documents and profile, and told us the account would be suppressed from the CIBIL records. With follow-up, it was. His CIBIL report pulled on 12 October 2026 carries no Axis Bank account anywhere in it, and shows a score of 719 — 66 points above the August report.
Two honest notes on that number. First, the August report also carried overdue amounts on several of his other, genuine accounts, and the October report shows those with no amount overdue; we do not attribute the whole 66-point rise to the Axis correction alone. Second, nothing accurate was removed: the bank withdrew an account it could not tie to him. The loan he had been refused has since come through — in his words below.
Report evidenceView his reports — before and after+
Tap to compare the two reports
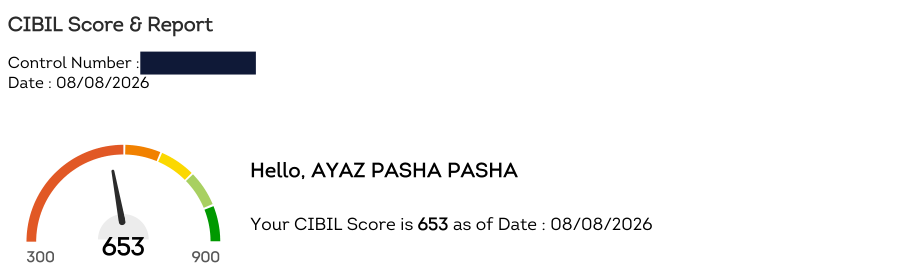
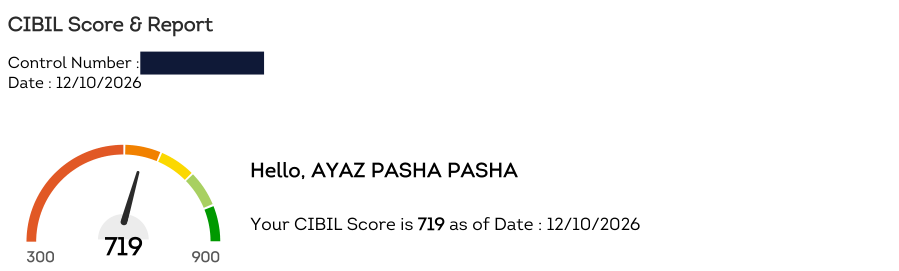
Axis Bank credit card — the first account on the August report; absent from the October report
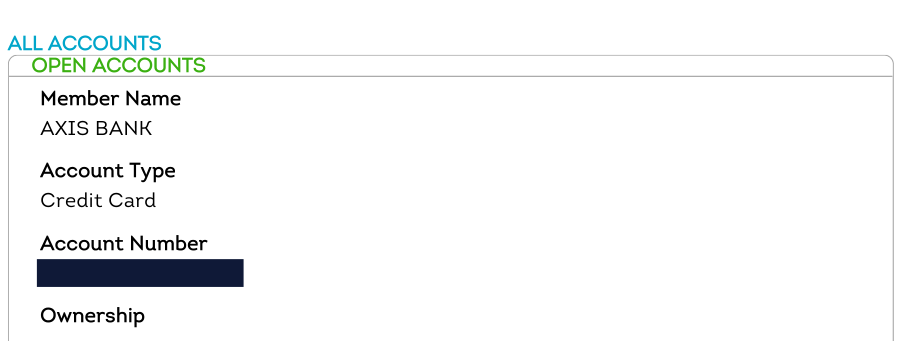
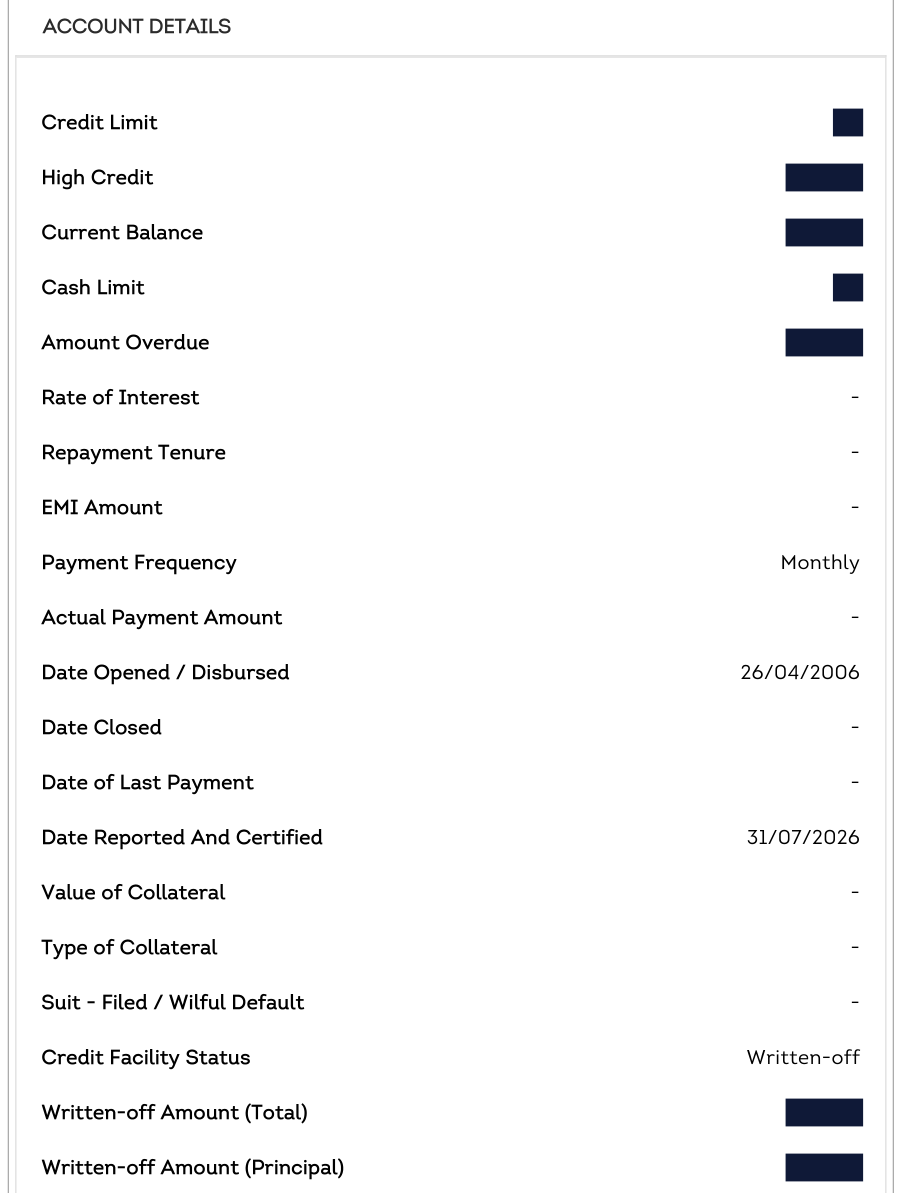
Extracts from the client's own CIBIL reports, pulled 8 August and 12 October 2026, published with his consent. Account numbers, amounts, control numbers and identifiers are redacted; dates and statuses are as reported. There is no 'after' extract for the card because there is nothing to show: no Axis Bank account appears on any of the October report's 51 pages. Both extracts of the card are from the August report.
His review, in his words
I was suffering from this problem from long time because one loan account was showing in my CIBIL and because of that I was not getting loan. My friend gave me Supraja madam number and I contacted her. First she also told that account belongs to me only as per report and asked me to make payment. But I explained my problem to her for long time and finally she understood my issue and told she will speak with bank. After few days she called and told my issue is resolved and that account is removed from my CIBIL report. I am very happy now because finally I got my loan also. Thank you Supraja madam for understanding my problem and helping me. Really thankful to you 🙏
Public Google review, quoted as it appears · view the original screenshot →
Why this case matters
Three things. First, a KYC match in the bureau's record is not proof of ownership. The bureau holds what lenders send it; if a lender has attached an account to the wrong person's identifiers, the bureau's match will look clean. Ownership is settled by the lender's own file — here, the application form — and that is where a disputed account has to be tested. Second, we say what we advised first. The report supported paying, and that is what I told him; it was his insistence, and the decision to verify with the bank rather than rely on the bureau, that changed the outcome. A client who is sure is a reason to check, not a problem to manage. Third, this is a suppression, not a deletion of history. Accurate negative history cannot be removed, and we never promise otherwise; what Axis Bank withdrew was an account it could not tie to him. When a report shows an account you do not recognise, the route is the one in our dispute escalation guide: dispute, then take it to the lender with your documents and ask for theirs. That is what personal credit repair looks like when the record, not the score, is the thing being fixed.
More documented cases
Different problems. Same standard.
A loan he never took. Corrected in five working days.
3 accounts → 2 · score unchanged at 732 · client video
By SuprajaA good score hid a broken report — 15 accounts that weren't hers
Data mismatch · CIBIL + Experian · clean report
By SuprajaA written-off loan he was sure he never took — the truth was more complicated
Evidence shared · dues cleared · written-off removed · DPDs masked
By SuprajaThree lenders, four bureaus — one report finally telling the truth
A guarantor account that wasn't his, gold loans wrongly written-off despite NOCs, and an untraceable overdue — corrected in 40–45 days. With the client's video story.
 By Smitha N · Credit Analyst
Looking for local help after reading this Bengaluru case? See Kenstone Credit in Bengaluru for the current contact and visit arrangements. This client’s outcome is not a promise of similar results.
Useful links