Case studies · Personal · Nellore, Andhra Pradesh
Home · Case studies · Card misuse cleared, home loan secured
A friend misused his card. A month of foreclosures and follow-up cleared the record — and won him a home loan.

Background
Mr. Gopal Batta of Nellore, Andhra Pradesh, onboarded on 10 July 2026 with his CIBIL at 666 and two accounts dragging it: an Axis Bank account and an SBI Card account, both reflecting written-off. In his own words, the trouble began when a friend misused his credit card — the kind of betrayal that turns someone else's spending into your credit history. What he needed was specific: the foreclosure details from each lender, a clean path to clear what stood outstanding, and the accounts correctly updated everywhere.
The work — foreclosures, payment, and the follow-through
Both banks were contacted for foreclosure details, and when routine follow-up stalled, the matter was escalated through the grievance process — the pattern our cases repeat because it works. The details arrived, they went to Mr. Gopal immediately, and he cleared the required amounts promptly — the part only a client can do, done without delay. Then the phase most people skip: monitoring every bureau and pushing the updates through until each report actually said what the payments had made true.
The outcome — and the choice inside it
On 10 August 2026 — one month to the day — the case closed with the mandate delivered: dues cleared against the foreclosure terms, both accounts at zero balance and zero overdue, and updates pushed across all four bureaus. The SBI Card entry came fully clean — its written-off reporting corrected outright. The Axis account closed with the classification "Post Write Off Closed" — and that is not an error; it is the accurate label for the choice Mr. Gopal knowingly made. Clearing it entirely would require paying the total loan value; he chose closure at the foreclosure amount, fully aware of the flag his choice retains, with full clearance remaining open to him any time he wants the label gone. And the outcome that vindicated the choice: his home loan was approved — the closure, not perfection, was what his goal required.
Report evidenceView his reports — onboarding day and today+
Tap to compare the two reports
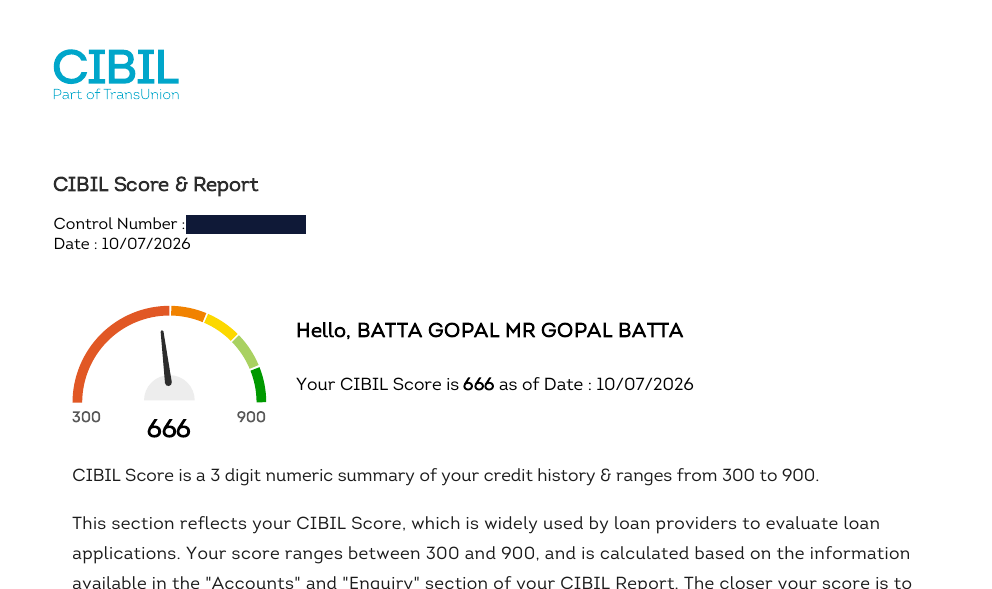
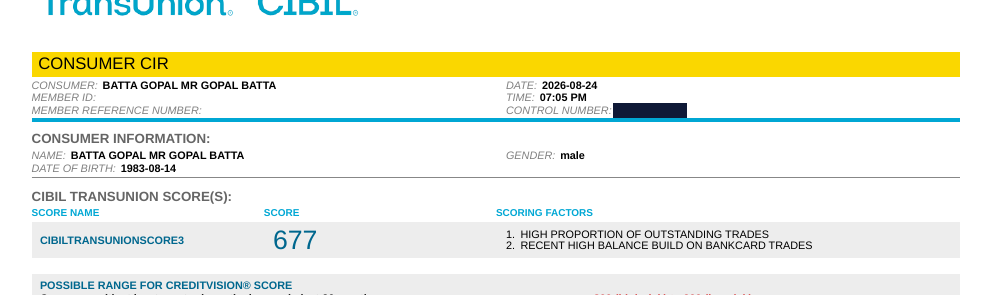
The SBI Card account — written-off at onboarding, fully corrected today
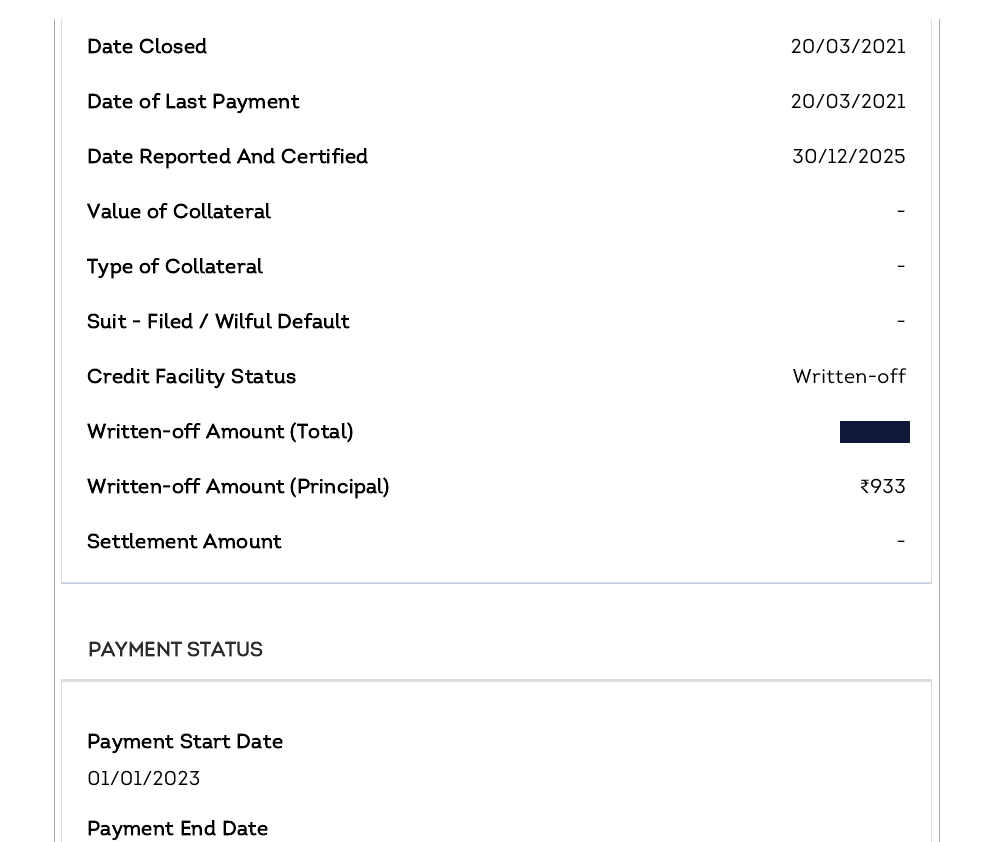
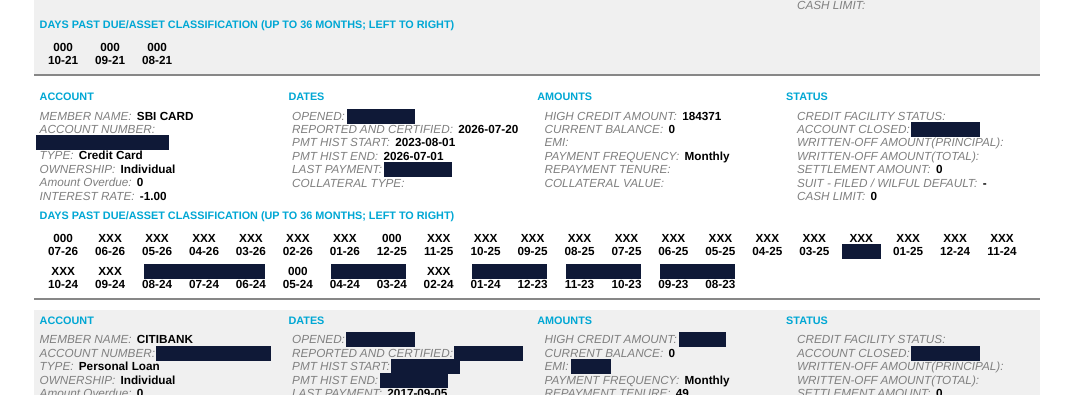
The Axis account — written-off at onboarding; today closed at zero, carrying the classification his closure choice retains
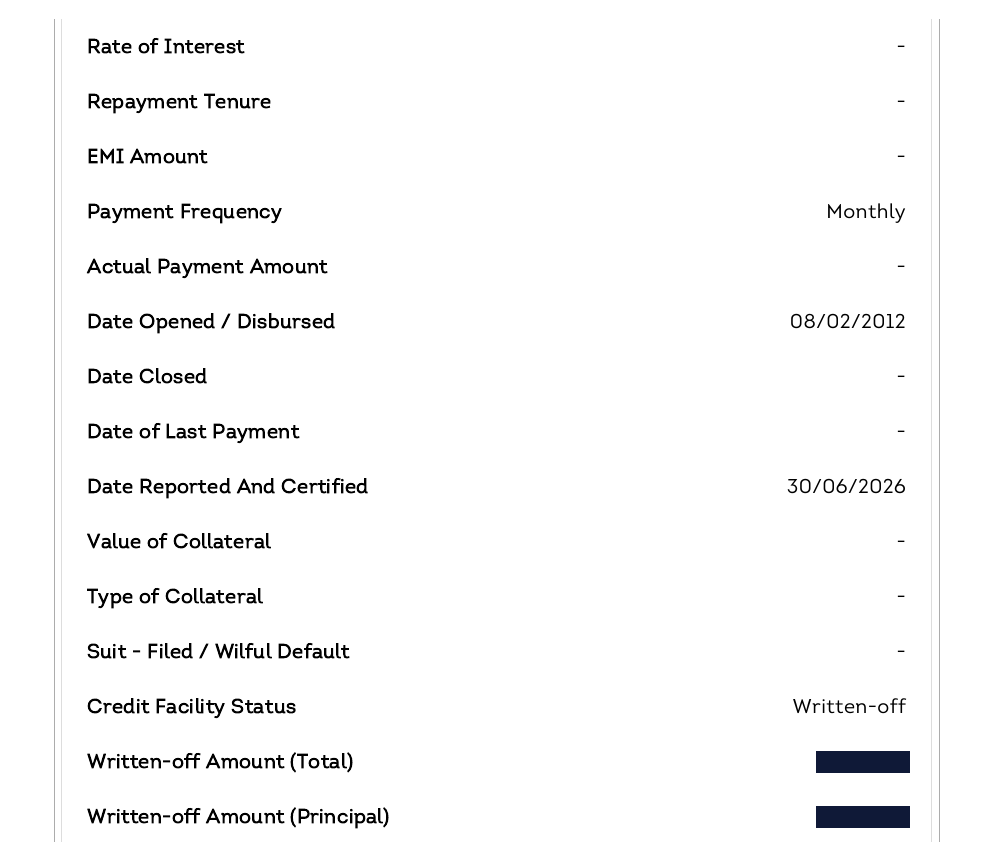
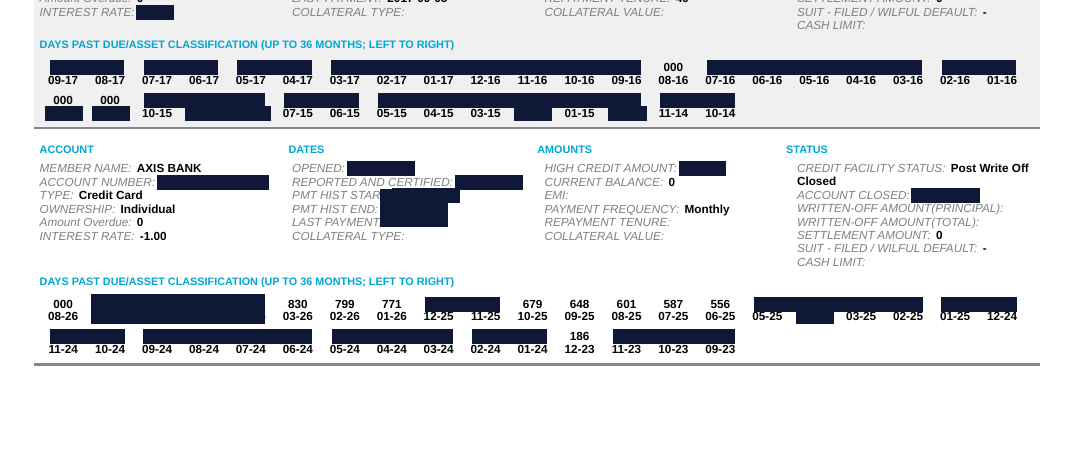
Raw extracts from Mr. Gopal's own TransUnion CIBIL reports, labelled by pull dates — onboarding day and the current report. Account numbers, amounts and identifiers are redacted; the lenders are named in this article, and the retained Axis classification is explained above, exactly as the client chose it. Published with his consent.
His testimonial, in his words
Recorded by Mr. Gopal — 35 seconds, captions available. His transcript, verbatim:
Hi, my name is Gopal. I was facing CIBIL dispute issues because a friend misused my credit card. I approached Kenstone Capital, and they helped me immensely in clearing all the disputes. Thanks to their assistance, I have now been able to secure a home loan. I want to extend a huge thank you to Vaidehi for resolving all these issues within just two weeks. Thanks again, Vaidehi, for all your help!
He remembers the disputes clearing in two weeks; the full case record, onboarding to four-bureau closure, runs 10 July to 10 August.
Why this case matters
Two reasons. First, card misuse by someone known to you is one of the most common — and least talked about — ways a clean payer ends up with written-off entries; the remedy is unglamorous and it works: foreclosure details in writing, dues cleared against them, follow-through across every bureau. Second — and rarer to see documented — this case shows the closure-versus-clearance choice stated honestly: paying the foreclosure amount closes the account at zero; blanking the classification entirely is a separate step, for which this bank asked for the total loan value. Mr. Gopal weighed the difference, chose closure with full knowledge of the label it retains, and his home loan was approved anyway — proof that the right question is never "how do I make it perfect" but "what does my goal actually require". The upgrade path stays open to him forever, exactly as our settlement guide explains. If a written-off entry is standing between you and a loan, start with what the status actually means — then start with the analysis.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
 By Michelle Juanita
Three delinquencies, two banks — one corrected rank
CMR 7 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad