
Background
Abhishek, from Bengaluru, came to us because his loan applications kept being rejected. That surprised him: his CIBIL report pulled on 24 July 2026 showed a score of 704. A score in the 700s is not where most people expect a refusal.
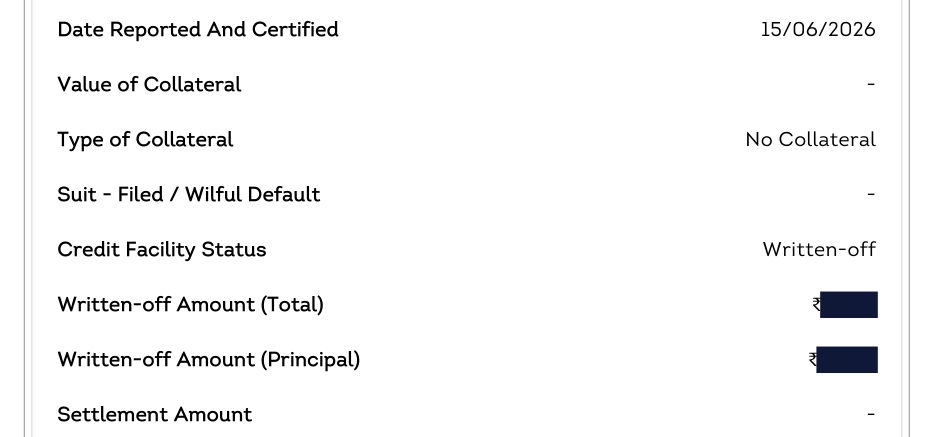
The score was not the problem. The entries were. Three small loans taken in 2019 were still open against him: a KrazyBee short-term personal loan that CIBIL showed as Written-off, and two Jalan Chemical Industries short-term personal loans that Experian, CRIF High Mark and Equifax showed as active with amounts overdue. A lender reading any of those reports saw unpaid debt, whatever the score said.
What the analysis found
These were his loans, and the dues were genuine. So this was not a dispute: nothing on the reports was wrong. The honest route was to pay what was owed and make sure each lender reported the accounts as closed, across every bureau that carried them.
The KrazyBee loan sat on CIBIL, Experian, CRIF High Mark and Equifax. The two Jalan loans did not appear on his CIBIL reports at all; they were reported to the other three bureaus. That is why the work had to cover all four bureaus, not just the one most lenders quote.
The approach
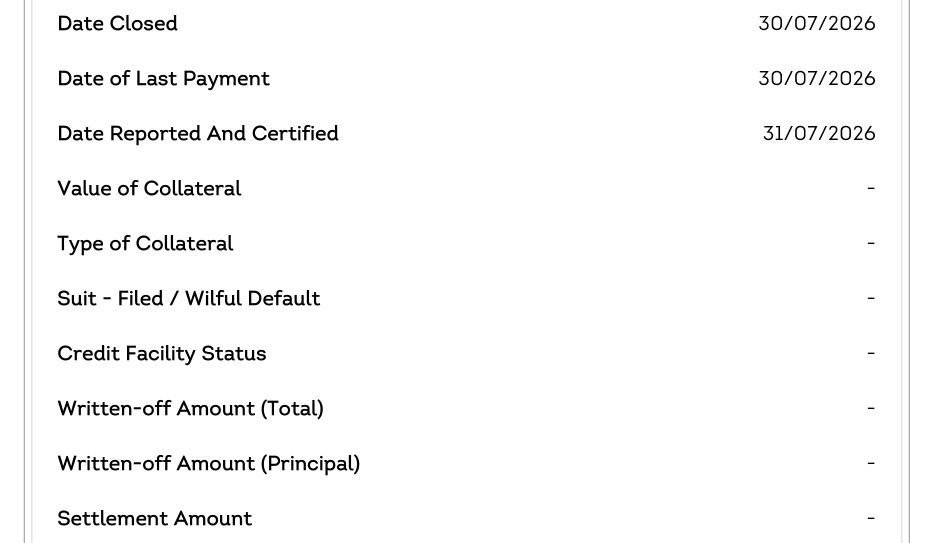
- KrazyBee: through our contacts with the lender, the dues were settled in full and the account closed within about 10 days. CIBIL shows it closed on 30 July 2026.
- Jalan Chemical Industries: the harder part. Even the lender’s contact details and a payment link were initially unavailable. We followed up repeatedly and escalated to the lender’s higher department until the payment link came through. Abhishek paid, and both loans show closed on 27 August 2026.
- Then the bureaus: we followed up so that the closures were reflected in his reports.
The ten-day figure and the escalation steps come from the consultant’s account. The report dates are evidence dates, not the start and end of the engagement.
The outcome
By mid-September all three loans were closed with nothing overdue, and his CIBIL score stood at 765.
| Bureau | Before | After | Source |
|---|---|---|---|
| CIBIL | 704 · 24 Jul | 765 · 15 Sep | Both reports on this page |
| Experian | 661 · 6 Aug | 666 · 16 Sep | Both reports on this page |
| CRIF High Mark | 553 · 6 Aug | 665 · 15 Sep | Before on file; the 15 Sep report on file prints no score, so 665 is from Supraja’s records |
| Equifax | 497 · 6 Aug | 610 · 15 Sep | After on file; 497 is from Supraja’s records |
Two honest notes. First, a score is a summary of the whole file, and several things changed between these pulls; we do not claim the exact number each closure added. Second, nothing accurate was removed. The KrazyBee entry still shows its earlier late months in the payment history; what changed is that it is now reported as closed and paid, not written off.
Report evidenceCompare the before and after reports
Choose a report to view its extracts
CIBIL score and report date
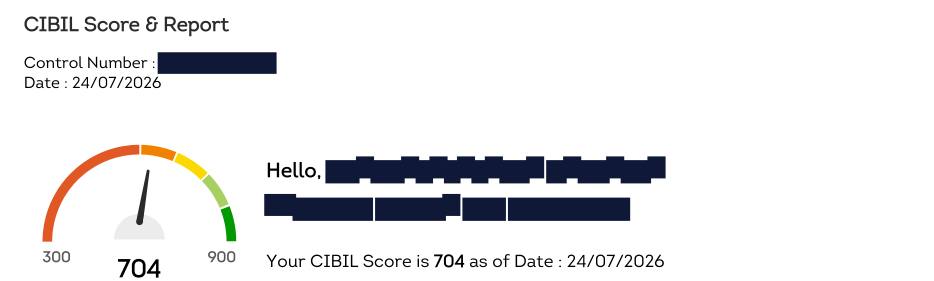
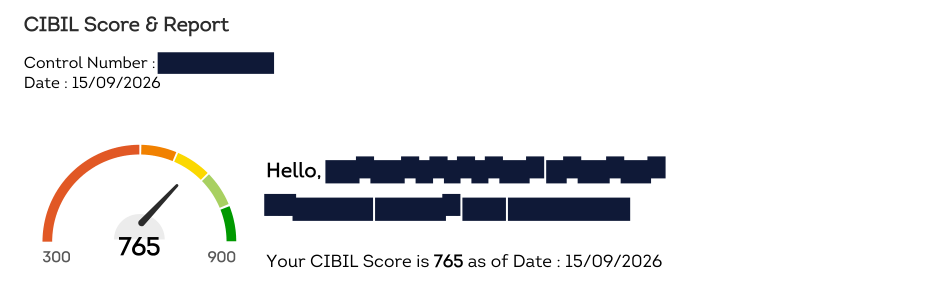
KrazyBee short-term personal loan on CIBIL
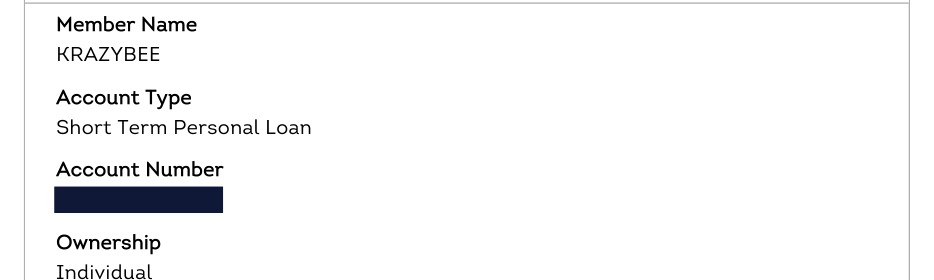
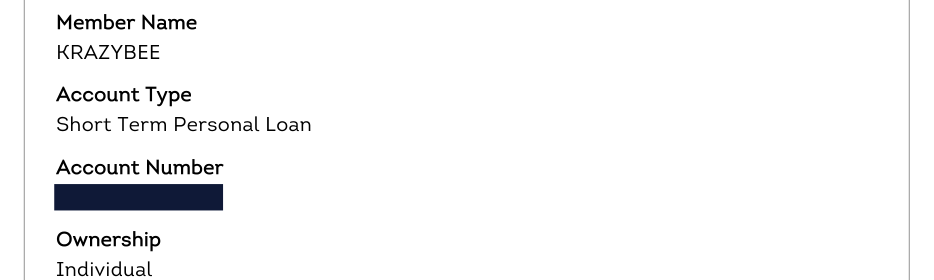
Its status: Written-off, then closed
The two Jalan Chemical Industries loans on Experian
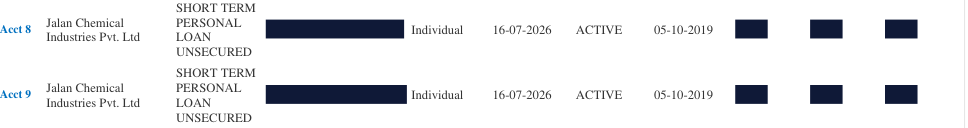
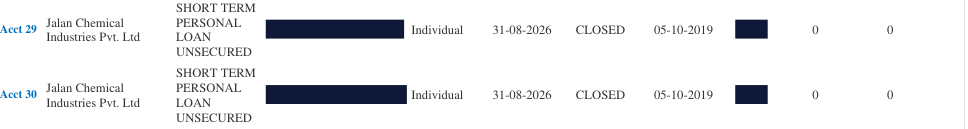
Crops from the client’s own reports: CIBIL pulled 24 July and 15 September 2026; Experian generated 6 August and 16 September 2026. Account numbers, control numbers, his name and every non-zero amount are redacted; dates, statuses and zeros are as reported. The Jalan loans do not appear on his CIBIL reports; they were reported to Experian, CRIF High Mark and Equifax, which show them closed on 27 August 2026. On CIBIL, the KrazyBee entry still carries its earlier months of late payment in the payment history: paying it changed the status, not the past.
Hear Abhishek’s account
Published with his consent.
Six or seven years of it, in his words
Abhishek describes the CIBIL problems that had followed him for six or seven years, and thanks Supraja for clearing them.
He speaks Kannada and English. The subtitles and full text below are an English translation using Sarvam; the English he spoke himself is kept as he said it.
The video describes this client’s experience. It is not a promised outcome.
Read the full English translation ↓Full English translation
Hello everyone. Previously, I am very suffering from in my CIBIL report. Last around six years back and seven years back. Now, my friend referred me to this company, Kenstone Capital. It's a beautiful working culture, it's very good. I have received a lot of help from them, be it my CIBIL or anything.
They have helped me a lot in financial matters. In this matter, I should never forget them in my life, because, like how important food and water are to a human, more than that, in our personal life, for some financial problems, CIBIL is also equally affected. So that's why, for that reason.
Kenstone Capital has cleared our issues very well. Thank you so much, especially Supraja Ma'am. Thank you so much, Ma'am. It's a very humble request for your beautiful working culture, Ma'am. Thank you so much, thank you so much, thank you so much.
Translation note: Abhishek refers to us as “Kenstone Capital”, a separate company in the same group; his case was handled by Kenstone Credit. His words are kept as spoken.
Why this case matters
A good score does not guarantee a loan. Lenders read the whole report: account status, overdue amounts and remarks such as written-off. A 704 with a written-off loan on it can be refused where a lower score with a clean file is not. Our guide on the CIBIL score lenders look for explains why the number is only the start.
Check all four bureaus. Two of these three loans never appeared on his CIBIL report. A lender pulling Experian, CRIF High Mark or Equifax would still have seen them. How the four bureaus differ explains why the same file can look different on each.
Genuine dues are resolved, not erased. Accurate history cannot be removed. When the debt is real, the honest path is to pay it and get the account reported correctly as closed, which is what changes how a lender reads it. Read what written-off means on your report, or ask for a written review before you pay through personal credit repair.