Case studies · Personal · Udupi, Karnataka
Home · Case studies · mPokket overdues cleared
Fifteen app-loan overdues, four CIBIL issues — one clean month

Background
Mr. Subramanya Hegde of Udupi came to us on 8 July 2026 with the modern version of an old problem: small app loans that had sprawled. His Equifax report carried fifteen overdue entries against mPokket accounts — the micro-loan app's small tickets, each one individually forgettable, collectively wrecking the file — and his CIBIL report carried four separate issues of its own. None of it was going to resolve itself, and every future application would read the wreckage first.
What the analysis found
The free analysis mapped all nineteen entries and told him the honest version: these were largely genuine dues stuck in unresolved states — not deletion candidates, but resolution candidates. The path was unglamorous and specific: obtain foreclosure details from each lender, clear the amounts, secure the No Objection Certificates, and then force the corrections through to all four bureaus. That is what he signed up for, in writing, with a fixed price — and it is exactly what happened.
The approach
Formal correction and foreclosure requests went to each lender by email. Where responses stalled, the matters were escalated through the public grievance (PMO portal) route — the escalation muscle that turns silence into paperwork. The CIBIL-side foreclosure details arrived within about ten working days; the mPokket details within roughly a week of escalation. Mr. Subramanya cleared each amount the moment the figures landed, and the follow-up shifted to collecting NOCs and monitoring the bureaus until every entry reflected the truth — across TransUnion CIBIL, Experian, Equifax and CRIF High Mark.
The outcome — in the client's words
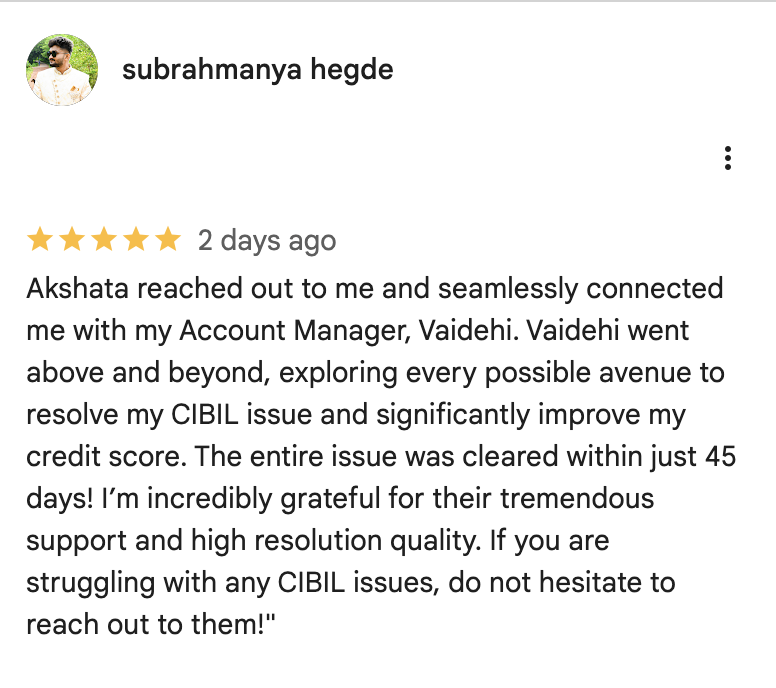
Onboarded 8 July 2026. Closed 8 August 2026. Nineteen entries resolved, NOCs in hand, four bureaus corrected — and a five-star review on our Udupi profile that names the people who did the work:
Why this case matters
Because it is the honest genre of credit repair, documented end to end: nothing here was "deleted" — genuine dues were resolved, closures were papered with NOCs, and the bureaus were made to reflect reality. It is also a warning label for the app-loan era: fifteen small overdue entries damage a file as surely as one large default, and they multiply quietly. If your report carries that sprawl, read it like an analyst, then start the same way this case did — with the analysis, before any payment.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
 By Michelle Juanita
Three delinquencies, two banks — one corrected rank
CMR 7 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad