Case studies · Personal · Bengaluru · all four bureaus
Home · Case studies · Four-bureau profile repaired
Four bureaus, four different scores, one cleanup: 670 → 759 and everything behind it

Background
When Mr. Praveen Kumar of Bengaluru came to us in February 2026, the striking thing was not one bad account — it was that all four bureaus told different stories about the same man: CIBIL read 670, CRIF High Mark 510, Equifax 440, Experian 439. Underneath the spread sat real problems: two ARCIL accounts reflecting overdue, a Clix account reflecting written-off, and — on Equifax — the same Clix-linked account appearing under multiple Clix entities. A profile like this fails loan checks unpredictably, depending on which bureau a lender happens to pull.
Onboarding scores (February 2026) → scores at resolution (June 2026), from the case record. CIBIL movement is documented in the report extracts below.
What the analysis found
Each bureau's report was reviewed separately — because each was wrong differently. The honest shape of the case was mixed, like most real files: genuine pending dues that needed clearing, and reporting problems that needed disputes — duplicate entries and cross-bureau mismatches that no payment would ever fix. The plan covered both tracks, with the price fixed in writing before any fee.
The approach — four bureaus, two tracks
Disputes went out account by account, with verification-and-correction mails drafted to each lender. Where genuine dues existed, Mr. Praveen cleared them, and each payment was papered so the lender's update could be forced through. Where follow-ups stalled, the matter escalated through the grievance machinery — including public-grievance (PMO) complaints where required. And when subsequent report pulls surfaced additional duplicates and mismatches beyond the opening list, those were taken up too: the mandate was a clean profile, not a closed ticket.
The outcome
By June 2026, the major issues were resolved: the ARCIL account now reports closed with zero balance and zero overdue (documented below), the written-off and duplicate reporting was rectified, and every bureau moved — CIBIL 670 → 759, Experian 439 → 709, Equifax 440 → 591, CRIF 510 → 573. The honest caveat, stated the way we always state it: further movement across CRIF and Equifax will follow subsequent reporting cycles and repayment behaviour — scores are the bureaus' verdicts on corrected data, not ours to promise.
Report evidenceView his CIBIL reports — before and after+
Tap to compare the two reports
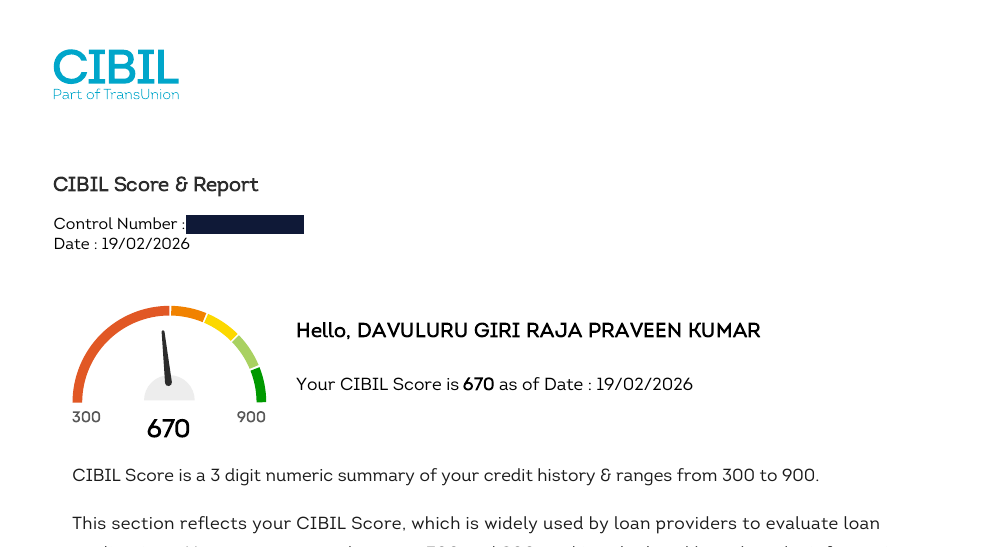
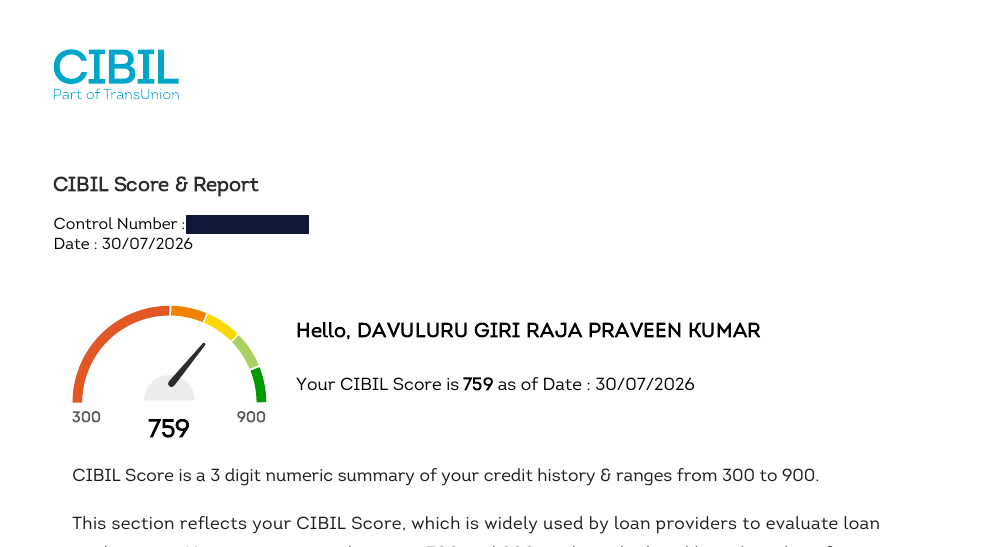
The ARCIL account — open on the February report, closed at zero on the July report
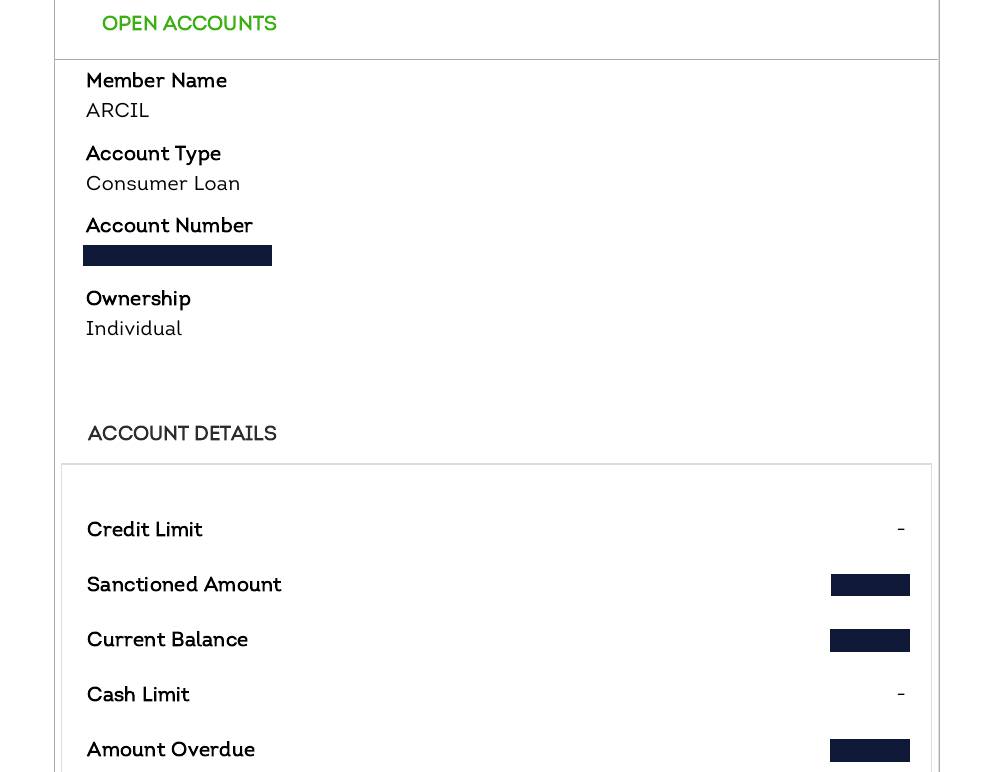
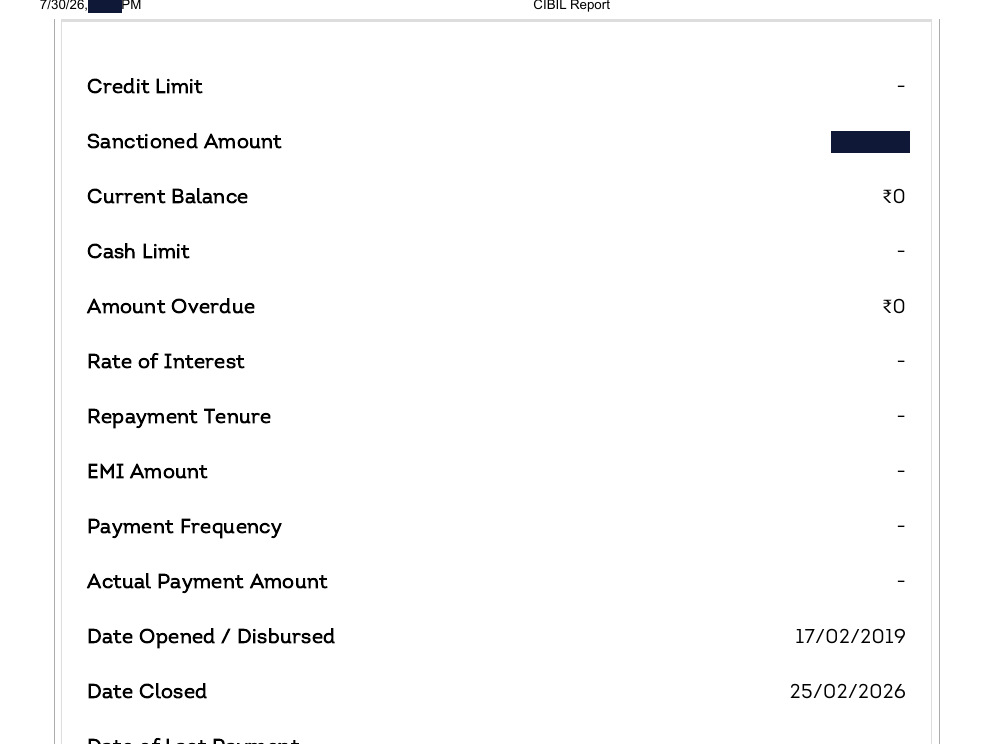
Raw extracts from Mr. Praveen's own TransUnion CIBIL reports, labelled by report pull dates. Account numbers, amounts and identifiers are redacted; the lenders are named in this article. Published with his consent.
I had a great experience with Kenstone Capital. The team, especially Rudolf, was professional, supportive, and kept me informed throughout the process. They helped resolve issues on my CIBIL report, clear pending dues, and significantly improve my CIBIL score. I highly recommend Kenstone Capital for their transparent, reliable, and customer-focused service.
Why this case matters
Because it documents what "my score is different everywhere" actually means — and what fixing it takes. Four bureaus hold four copies of your history, wrong in four different ways; correcting one report corrects nothing at the other three. This case ran the full machinery — account-level disputes, lender mails, payment papering, grievance escalation, and re-checks that caught issues the first pass could not see — across every bureau in parallel. It is also the first published case from Rudolph Mathias's desk, and it carries his signature: the mandate ends when the profile is clean, not when the ticket closes. If your scores disagree with each other, start with why the four bureaus differ — then start with the analysis.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
 By Michelle Juanita
Three delinquencies, two banks — one corrected rank
CMR 7 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad