Case studies · Personal · Hassan, Karnataka
Home · Case studies · HDB written-off remark corrected in 30 days
A good score, a stuck loan — and one remark that wasn't true.

By Rudolph Mathias, Credit Analyst, Kenstone Credit.
Background
When Mr. Francis Xavier approached us, he was facing a challenge many borrowers don't expect: a good credit score, a healthy repayment history, and a personal loan application that simply would not move.
My initial review found the root cause. His HDB Financial Services personal loan, closed in full, was incorrectly reported with a Written-Off status. One reporting error, one stalled application. I reviewed the account history, repayment details, and reporting across all major bureaus to confirm it was the only significant negative remark, explained the process, the expected timeline, and the escalation stages if the standard route failed. He was onboarded on 1 June 2026, and I took ownership of the case.
My approach, the full ladder
Bank first. Formal representations to HDB Financial Services requesting removal of the incorrect status across all bureaus. The first challenge was silence, delays despite multiple follow-ups. I kept the matter active with continuous reminders.
Then a CIBIL dispute. I raised the dispute with TransUnion CIBIL and monitored it through the prescribed period. Here is the honest part: even after the dispute completed, the Written-Off status remained. The standard process was not going to be enough.
Then the PMO. I escalated through the Prime Minister's Office Grievance Portal with a detailed complaint and full supporting documents. Within seven working days, the bank acknowledged the reporting error, corrected the account status, and removed the remark.
Then verification. Once the correction reflected in CIBIL, I verified and monitored the profile across all major bureaus until the incorrect status was confirmed removed from every one.
The result
Report evidenceView the report, before and after+
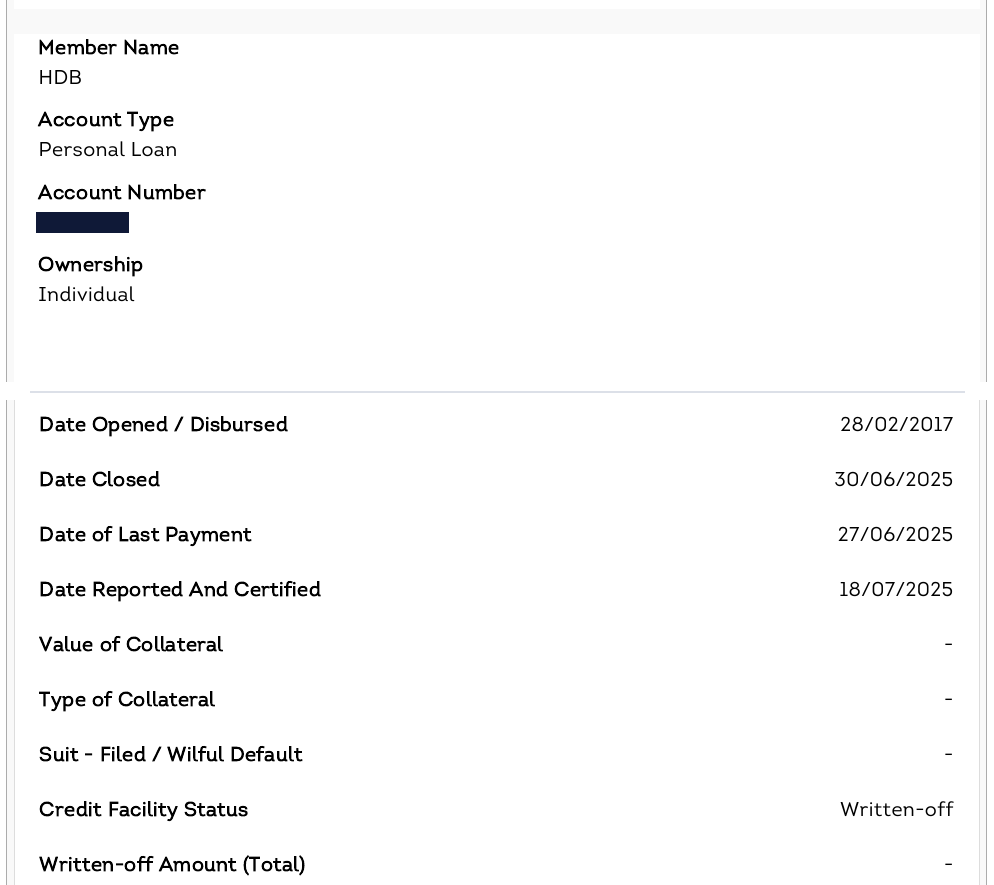
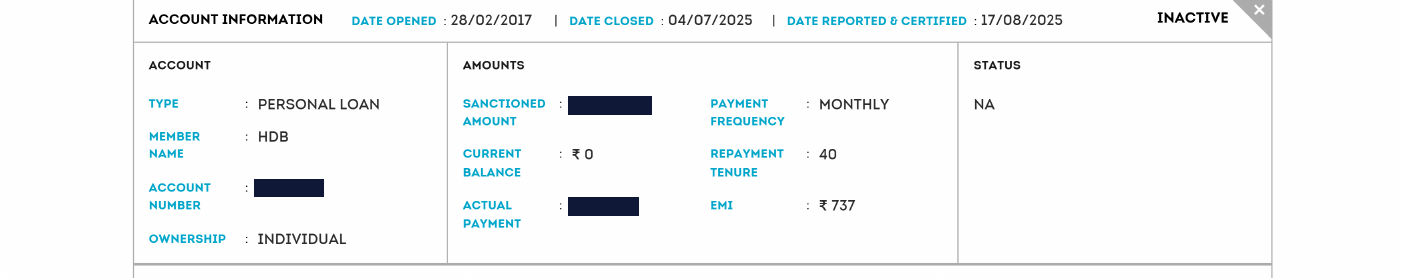
Same account, two CIBIL pulls one month apart. On the left, the report pulled just before onboarding still carries Credit Facility Status: Written-off, with the lender's certification frozen at July–August 2025, because HDB had stopped active monthly reporting. That staleness is exactly what kept the wrong status in place. On the right, after the escalation, the written-off status is gone and the account is reported closed. Account number and amounts are hidden; excerpts shown with the client's written consent.
Why this case matters
Even borrowers with good scores can be stopped cold by one wrong remark. And when the standard channels fail — as the CIBIL dispute did here — knowing the escalation ladder is the difference between a stuck case and a resolved one. My role continues until the report is accurate: representations, disputes, escalation, and follow-up to verified closure. We had committed to 35–45 working days; it took about thirty.
Francis Xavier
Nice service supportive iddarae
Kenstone capital superr
Published with the client's written consent.
 0:35
Full video transcript
My name is Francis Xavier. I took a personal loan from HDB and closed it in full. However, there was a return up. It was very difficult for me to get a CIBIL. So, in our shop, Anjan Shetty, a loan consultant, got acquainted with a company called Kenstone Capital, and said that it would be fixed in thirty-five to forty-five days. But everything is fine now in thirty days. Now I have also gone for a return. The service is fast. There is no problem. You can do it easily. Now the CIBIL score has increased, and now we can get a loan from any bank. Thank you.
More documented cases
Different problems. Same standard.
Ready to pay — and no way to pay. Until the right escalation.
PMO escalation · 1 month
 By Vaidhehi P
Settled in 2023 — then sold, and reported "written-off"
RBI + PMO · ₹5,000 compensation
 By Supraja
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · ₹16L sanctioned
 By Smitha N
A genuine written-off account, resolved the honest way
14 days · fully remote
 By Aradhana Prasad