Background
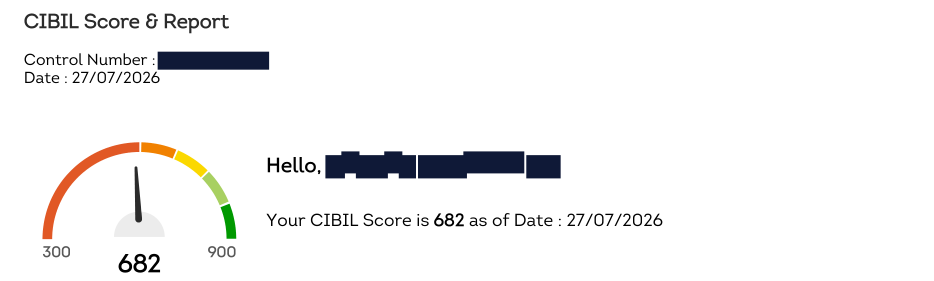
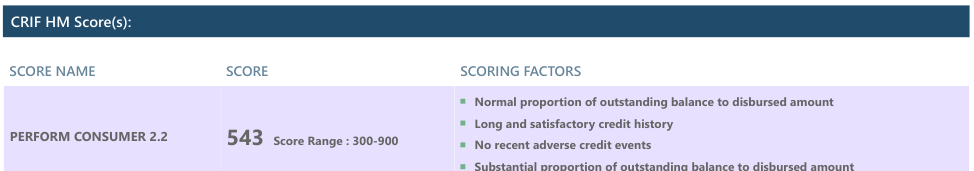
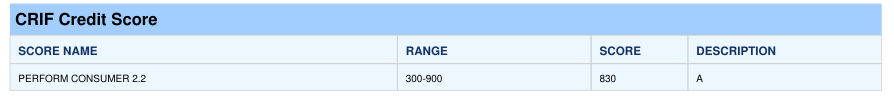
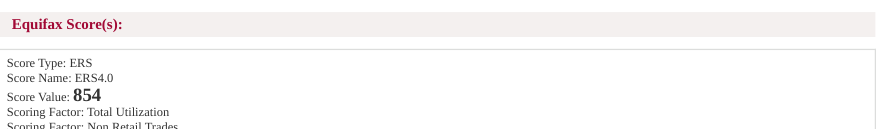
Gaurav found us through a police station. Another of our clients, whose identity had been misused in the same way, had filed a police complaint on our advice; he met Gaurav there, and Gaurav came to us with the same problem: loan accounts on his credit reports that he had never taken. They were dragging his scores down: his CIBIL report pulled on 27 July 2026 showed 682, his CRIF High Mark report on 29 July showed 543, and his Equifax report on 6 August showed 548.
He had already complained to the lenders concerned. They had rejected his complaints, and they would not give him the loan agreements or the KYC documents behind the accounts, which were the only things that could show who had actually applied.
What the analysis found
Two accounts did not belong on his file, both personal loans opened in September 2025 from non-bank lenders:
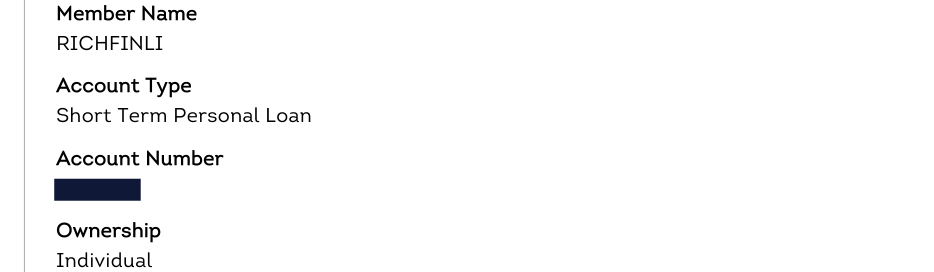
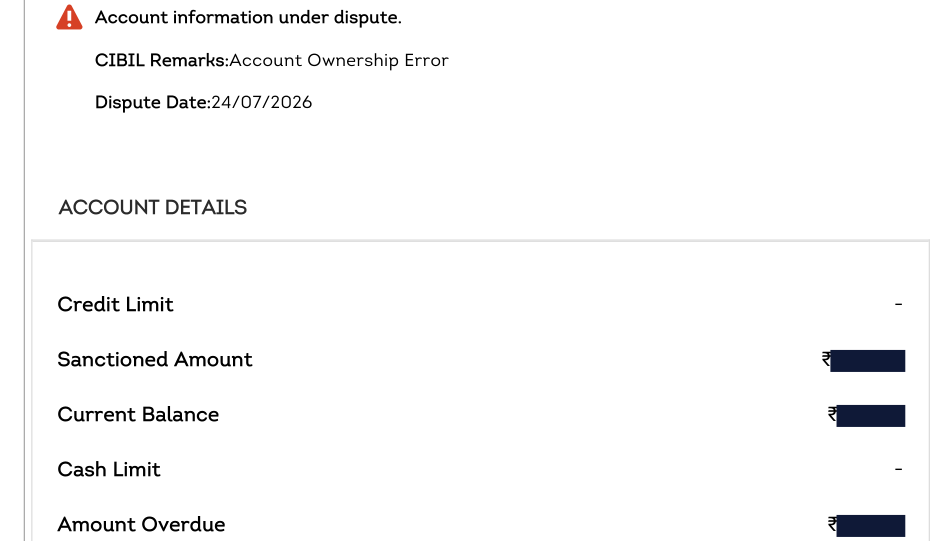
- Richfinli, a short-term personal loan on his CIBIL report, opened 22 September 2025 and showing an amount overdue. By the July pull it was already marked “Account information under dispute” with the CIBIL remark “Account Ownership Error”.
- Vrinda Finlease, a personal loan on his CRIF High Mark and Equifax reports, opened 8 September 2025. Equifax showed it 180–359 days past due and classified Doubtful.
A bureau can only hold what a lender reports. When a lender has attached a loan to the wrong person, the proof sits in the lender’s own file: the agreement, the KYC, the photograph of whoever applied. Getting those documents was the whole case.
The approach
Aradhana Prasad took ownership of the case and escalated it through the PMO grievance portal, asking for the loan agreements, the KYC records, the borrowers’ photographs and the other documents the lenders were holding.
With persistent follow-up, the lenders disclosed the records. According to Aradhana, they showed that Gaurav’s PAN and Aadhaar details had been manipulated to take the loans. On that evidence the lenders acknowledged the discrepancy and removed the accounts from his credit reports.
The outcome
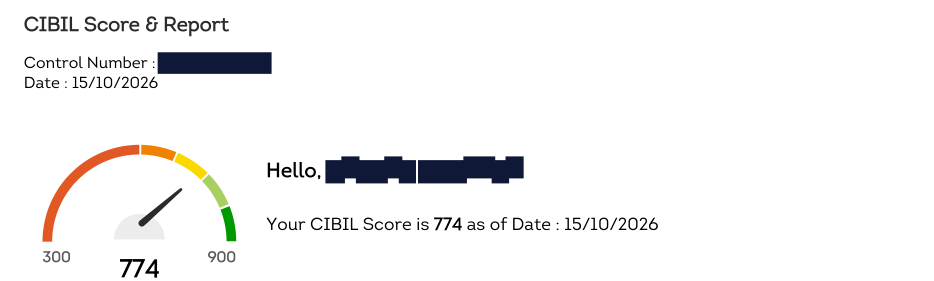
The Richfinli loan is gone from his CIBIL report pulled 15 October 2026; the Vrinda Finlease loan is gone from his CRIF High Mark report of 16 September and his Equifax report of 7 September. On each bureau, these were the only accounts that left his report.
| Bureau | Before | After |
|---|---|---|
| CIBIL | 682 · 27 Jul | 774 · 15 Oct |
| CRIF High Mark | 543 · 29 Jul | 830 · 16 Sep |
| Equifax | 548 · 6 Aug | 854 · 7 Sep |
Nothing he genuinely owed was touched: every other account on his reports stayed exactly as it was. After the resolution, Gaurav also chose our annual maintenance contract, so his reports are checked regularly and anything new is caught early.
Report evidenceCompare the before and after reports
Choose a report to view its extracts
CIBIL score and report date
CRIF High Mark score
Equifax score

The Richfinli loan on the July CIBIL report — before only
Already flagged on that report: “Account Ownership Error”
The Vrinda Finlease loan on the August Equifax report — before only
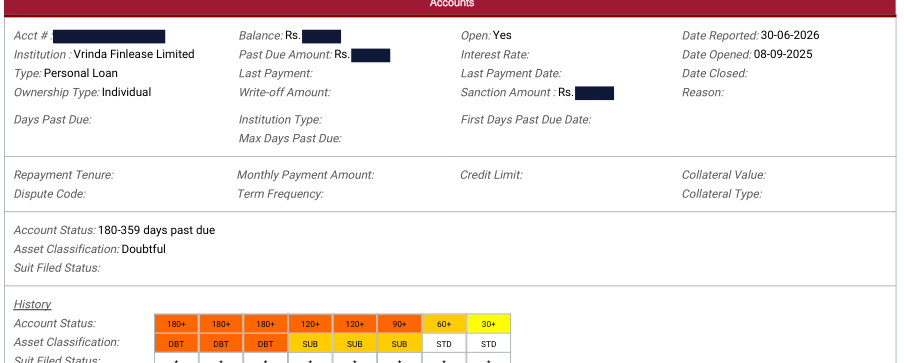
Crops from the client’s own reports: CIBIL 27 July and 15 October, CRIF High Mark 29 July and 16 September, Equifax 6 August and 7 September 2026. Account and control numbers, his name and every amount are redacted; dates, statuses and scores are as reported. The Richfinli loan appears in the July CIBIL report and not in October’s; the Vrinda Finlease loan appears in the July CRIF and August Equifax reports and not in the later ones. On each bureau these were the only accounts that left his report between the two pulls.
The police case
Gaurav also filed an FIR over the misuse of his identity. We gave the police the documents from his case, setting out how far the misuse went and how it was hurting him for loans he had never taken. On 30 September 2026, Live Hindustan reported that the East Delhi district cyber police had arrested two brothers from Gurugram, accused of altering the photographs and fathers’ names on other people’s PAN and voter ID cards to take more than 70 fake loans, with losses so far of over ₹1 crore. Dainik Jagran reported police sources putting the figure far higher. These are allegations reported in the press; the investigation is the police’s, not ours.
Hear Gaurav’s account
Published with his consent.
“Absolutely perfect”, in his words
Gaurav describes hearing about us from a friend he met at the police station, and thanks Aradhana and Anita for setting it right and for the guidance since.
The audio is Hindi. The subtitles and full text below are an English translation, rather than words originally spoken in English.
The video describes this client’s experience. It is not a promised outcome.
Read the full English translation ↓Full English translation of the Hindi testimonial
Hi. Actually, about CIBIL — I have a friend I met, basically, inside the police station. He told me about it. So when I talked to Anita Ma'am and Aradhana Ma'am, they advised me: Gaurav ji, do this and this, and all these things can be set right.
And it turned out absolutely perfect. Aradhana ji sorted out all my things perfectly, in a systematic way, and she also gave me guidance for the future: Gaurav ji, do it this way and it will stay this way; it needs a little care. So from my side, many, many thanks to Anita Ma'am, Aradhana Ma'am and Kenstone Credit. Thank you so much.
Translation note: machine translation (Sarvam) rendered his opening “CIBIL के लिए” as “for Kenstone”; the English above follows what he said (“about CIBIL”). The rest is as translated.
His review, in his words
U guys are amazing
You have turned my problems in to a better and smiling solution
Thanks Aradhana
Public Google review on our Bengaluru profile, quoted as written.
Why this case matters
Identity theft shows up on a credit report as somebody else’s debt in your name. The bureau cannot tell who signed; only the lender’s file can. When a lender rejects your complaint and keeps the paperwork to itself, a formal escalation that asks for the agreement, the KYC and the applicant’s photograph is what makes the evidence appear.
Check all your reports. One of these loans showed on CIBIL, the other on CRIF High Mark and Equifax. A lender pulling any one bureau would have seen debt he never took. Our CIBIL dispute and escalation guide sets out the routes, and how to read your CIBIL report shows where to look.
Accurate history cannot be removed. What came off his reports were accounts that were not his. If you find one on yours, report the misuse to the police as well as the lender. Our personal credit repair service starts with a written review before you pay.