Case studies · Personal · Resolved from Australia
Home · Case studies · INTEGROFI overdue resolved from Australia
Resolved from 8,000 km away: an INTEGROFI overdue, four bureaus corrected, 649 → 706

Background
Ms. Shubha Sumesh lives in Australia. Her credit history lives in India — and in July 2026, one line of it was doing disproportionate damage: an INTEGROFI credit card reporting overdue, its trail running back two decades, its DPD grid showing LSS, the loss classification. Her CIBIL score stood at 649. She was ready to clear the dues; what she could not do from another continent was make an Indian lender produce foreclosure figures and make four bureaus update. That is what she assigned to us on 15 July 2026.
How this case arrived — from the sales desk
The enquiry did not begin with us — it began with a bank saying no. Ms. Shubha had approached a bank for a loan in India and was told she was ineligible because of an issue on her credit report. She had not visited India in almost fifteen years, and her available documentation here came down to one thing: her PAN card. That was enough — with the PAN we fetched and reviewed her report, and found the long-standing credit card account still reflecting against her. To her knowledge, the card had been paid and long abandoned; on the report, it was still alive and still doing damage.
My job at that stage was not to promise an outcome — it was to explain the problem truthfully: an old, inactive account can keep appearing when the lender's records were never properly updated, and that is a credit-reporting problem with a process, not a life sentence. What she was facing was not really a loan rejection; it was a correctable reporting issue wearing one. Once the process was clear — reach the institution, establish the account's true status, resolve what was genuinely owed, and force the corrections through — she signed up, and the case moved to Vaidhehi's desk. What happened there is the rest of this page.
What the analysis found
The report analysis confirmed the honest shape of the case: this was a genuine due in an abandoned state — a resolution case, not a deletion case. The path was the unglamorous one we publish again and again: obtain the exact foreclosure amount from the lender, have the client pay it, secure the confirmation, then force the corrected status through every bureau. She signed for exactly that, with the price fixed in writing.
The approach — run entirely remotely
Lender communication opened immediately; when the foreclosure details stalled, the matter went through the public grievance (PMO portal) escalation route — the same muscle documented across our cases. The foreclosure amount arrived, was shared the same day across time zones, and Ms. Shubha paid without delay. Payment confirmation in hand, disputes went to all four bureaus — TransUnion CIBIL, Experian, Equifax and CRIF High Mark — with follow-up until each one reflected the truth. All four updated within 15 working days.
The outcome
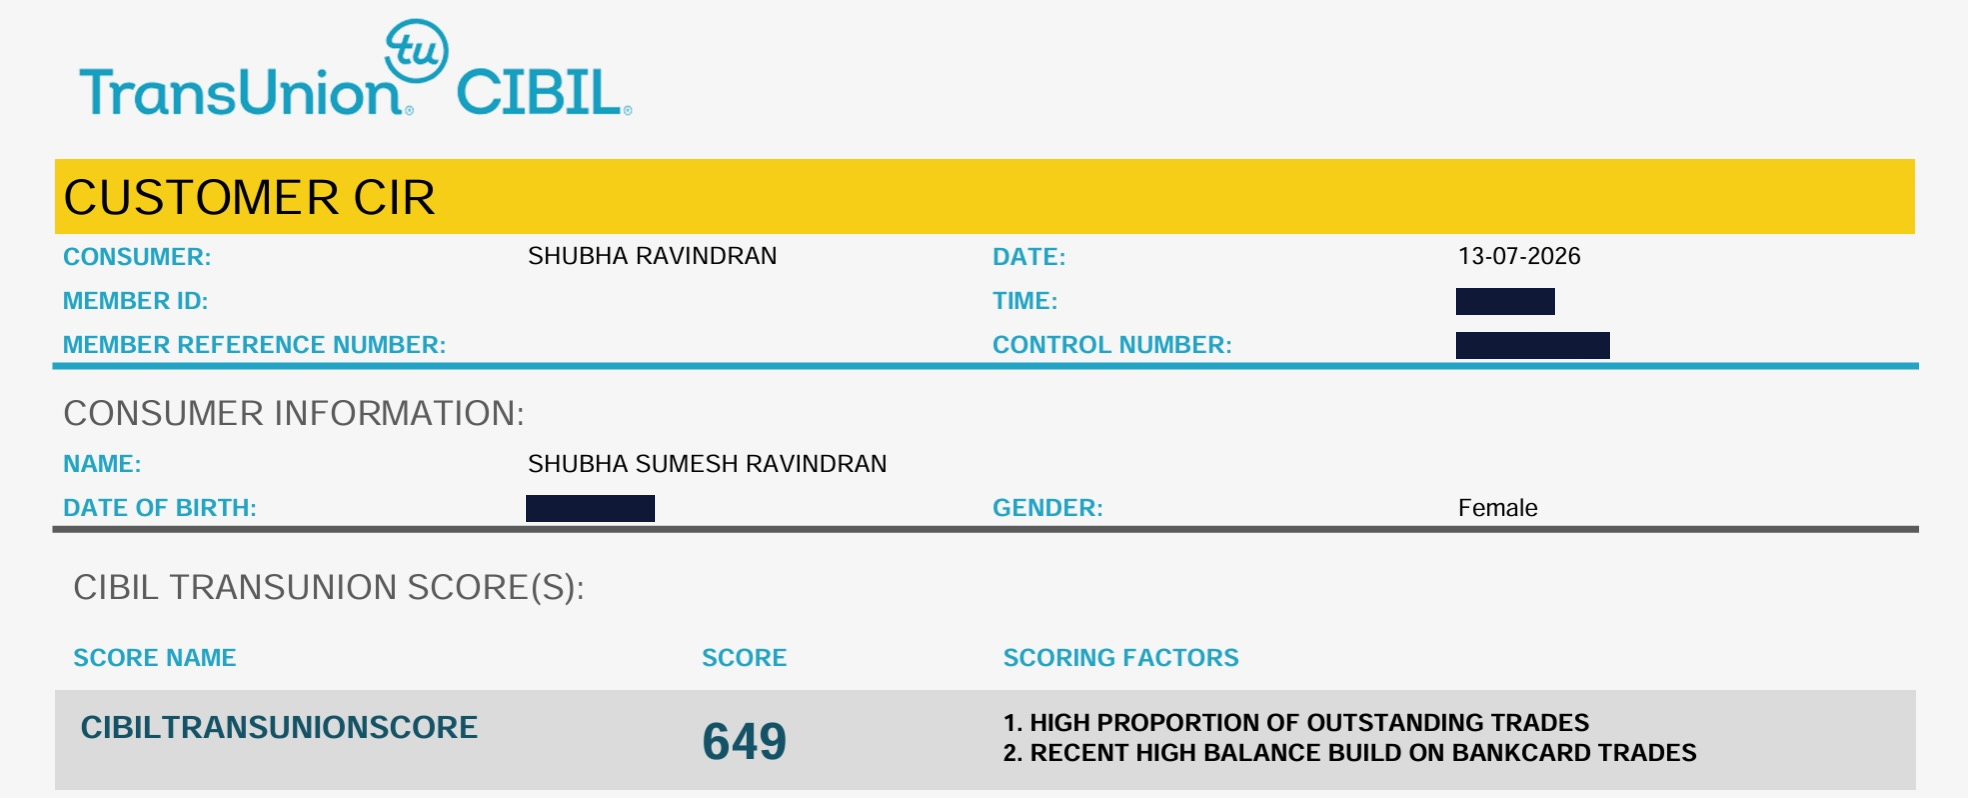
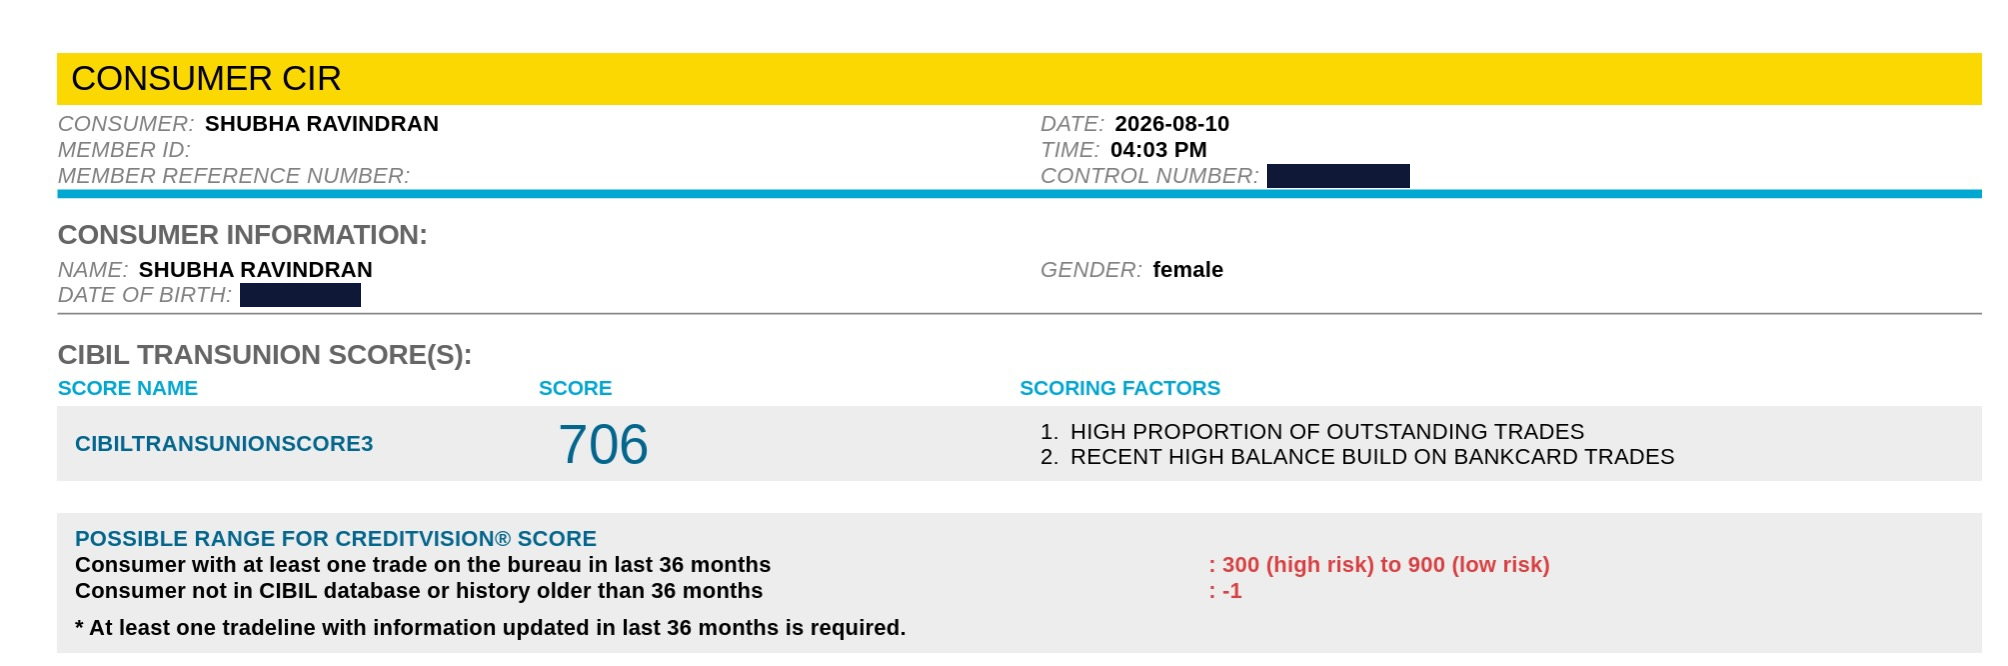
Assigned 15 July 2026; resolved within the month. The INTEGROFI account now reports closed with zero balance, and her CIBIL score moved from 649 to 706 — a 57-point recovery — documented below in her own report extracts, pulled before and after.
Report evidenceView her reports — before and after+
Tap to compare the two reports
The INTEGROFI account line — same account, both pulls
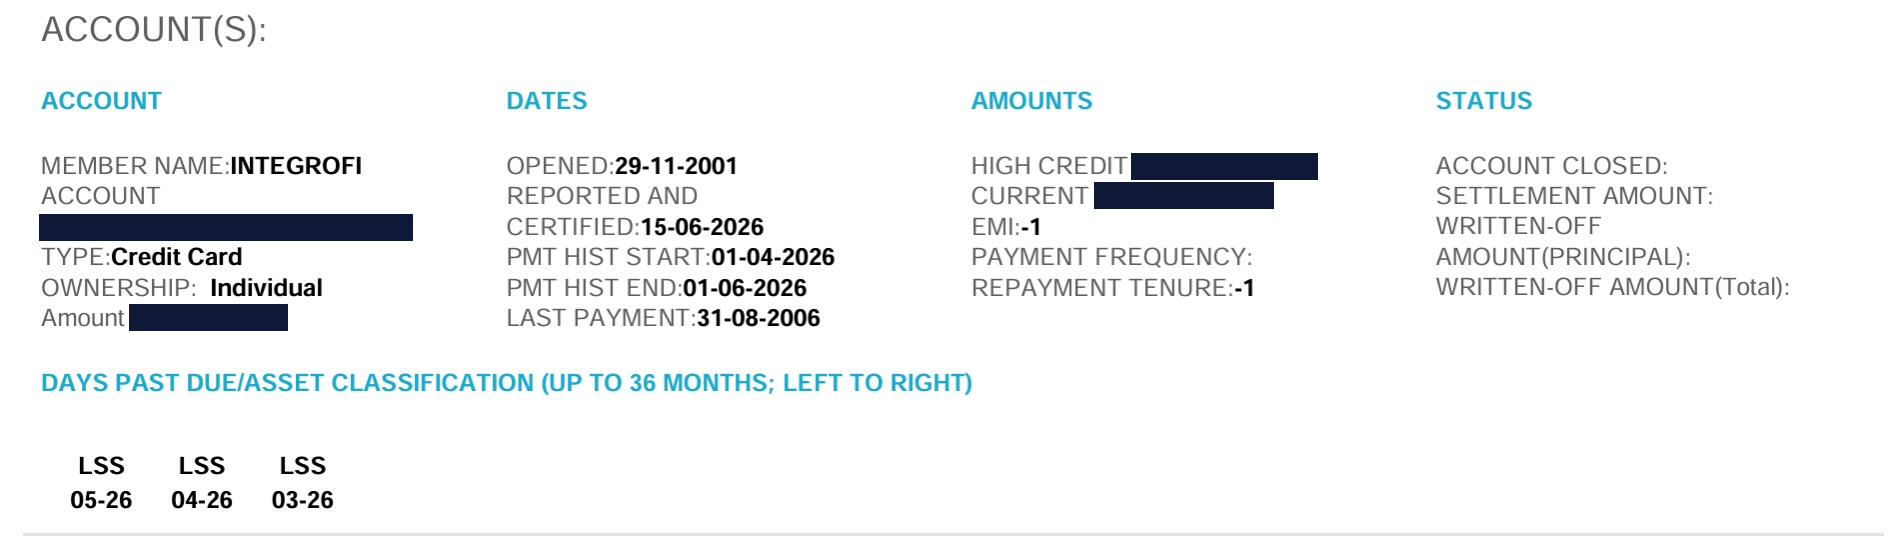
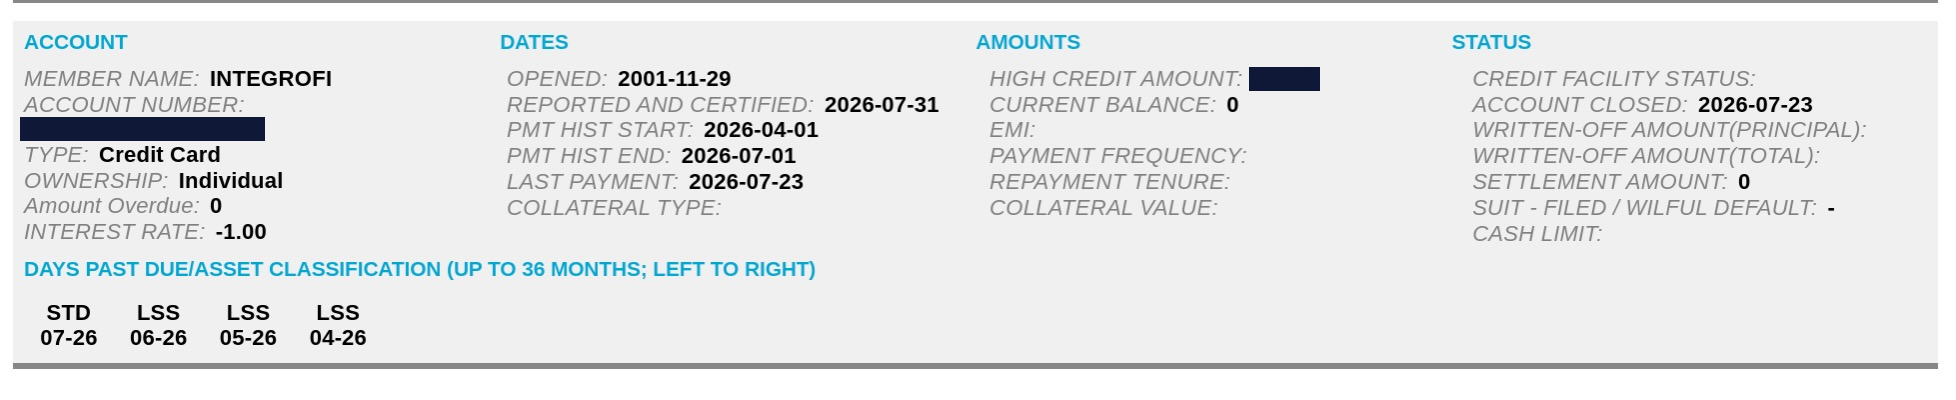
Raw extracts from Ms. Shubha's own TransUnion CIBIL reports, labelled by report pull dates. Account number, date of birth, control numbers and amounts are redacted; the lender is named in this article. Published with her consent.
Her testimonial, in her words
Recorded by Ms. Shubha from Australia — 1 minute 22 seconds, captions available. Her full transcript follows, verbatim.
Hello. My name is Shubha Sumesh. I would like to share my recent experience with Kenstone. I approached them for my CIBIL issue, which was a very old issue. And I came across recently, and it was holding me back. So Kenstone explained me the process to deal with it and get the clearance from the CIBIL report. And they assigned me the case officer. I got luckily Vaidehi, who is incredible. She explained the process to me and managed to get the clearance report. And I'm very happy with the service. Especially, I would like to thank Kenstone as well as Vaidehi for her amazing service and support for getting my financial health back on track. Thank you Vaidehi once again. Thank you very much.
Why this case matters
Two reasons. First, it is the honest genre at its clearest: nothing here was "deleted" — a genuine due was paid, the closure was papered, and the bureaus were made to tell the truth; the score moved because reality moved. Second, it is our remote-service model proven at its logical extreme: if an overdue can be escalated, resolved and corrected across four bureaus for a client eight thousand kilometres away in Australia, the same desk serves every city in India without a flight. For NRIs carrying old Indian credit trails — dormant cards, forgotten app loans, addresses long left behind — this case is the template: the process runs on documents and escalation, not on your presence.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
 By Michelle Juanita
Three delinquencies, two banks — one corrected rank
CMR 7 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad