Background
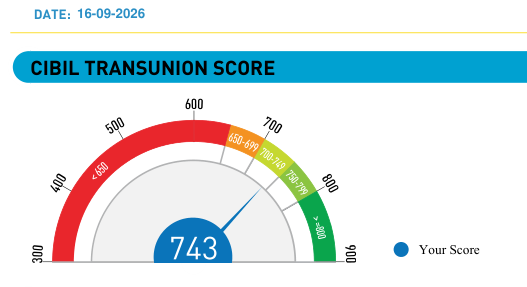
David, from Hyderabad, came to us because two old accounts on his CIBIL report were holding up a loan application. His report pulled on 16 September 2026 showed a score of 743, and two written-off entries:
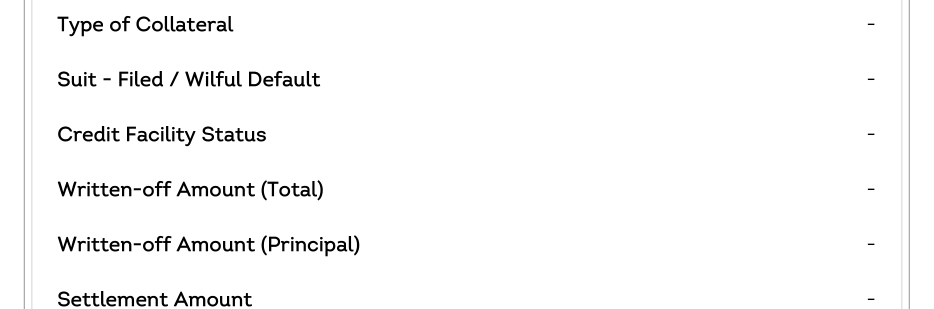
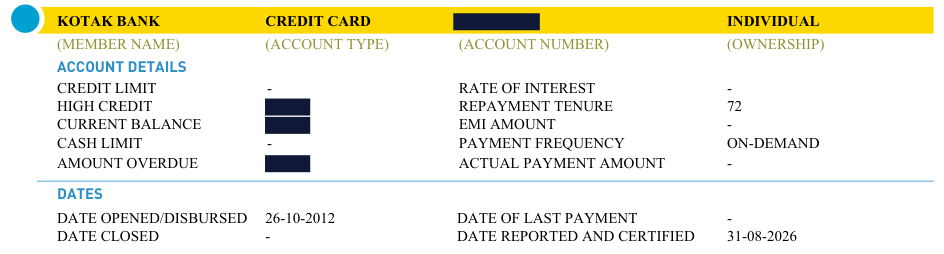
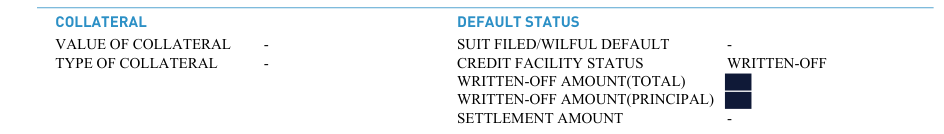
- Kotak credit card, opened in October 2012, reported with a Credit Facility Status of “Account Purchased and Written Off” and an amount overdue, last reported 31 August 2026.
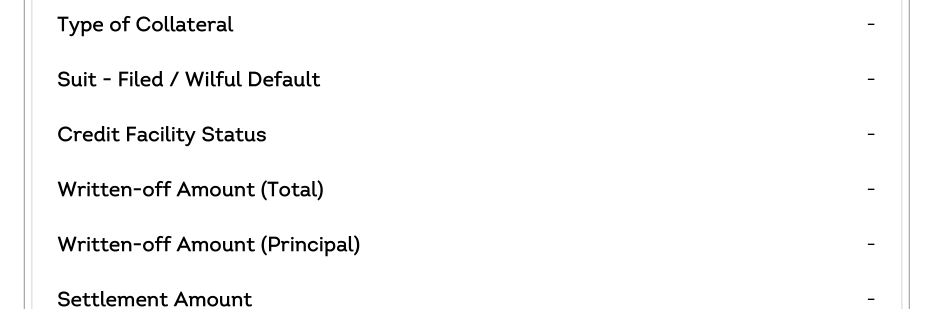
- HDFC personal loan, opened in April 2011 and shown as closed in 2014, but still carrying a Written-off status and a small amount overdue.
He had already tried to settle the Kotak card himself, and it was taking longer than he could wait. On the HDFC loan, his position was that the payment had been made and the status had simply not been updated.
The approach
Aradhana Prasad took ownership of the case. She raised grievances through the PMO grievance portal to move both banks, and alongside those escalations worked directly with each bank’s point of contact, following up regularly.
- Kotak: she followed up with the bank’s officials to resolve the written-off status and to obtain the No Dues Certificate.
- HDFC: she worked with the bank’s point of contact to get the reporting corrected.
Per Aradhana, both were resolved within 18 days. The report dates below are evidence dates, not the start and end of the engagement.
The outcome
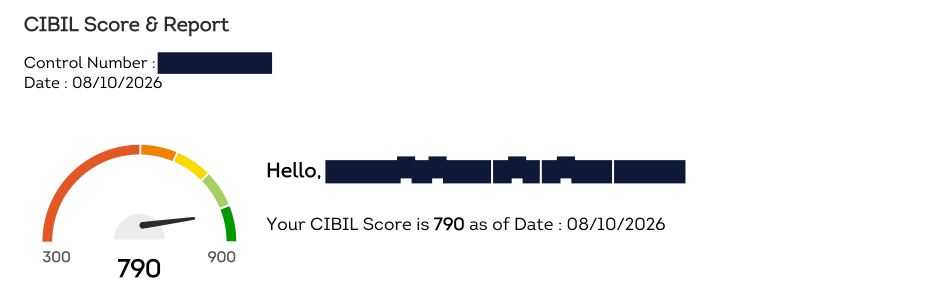
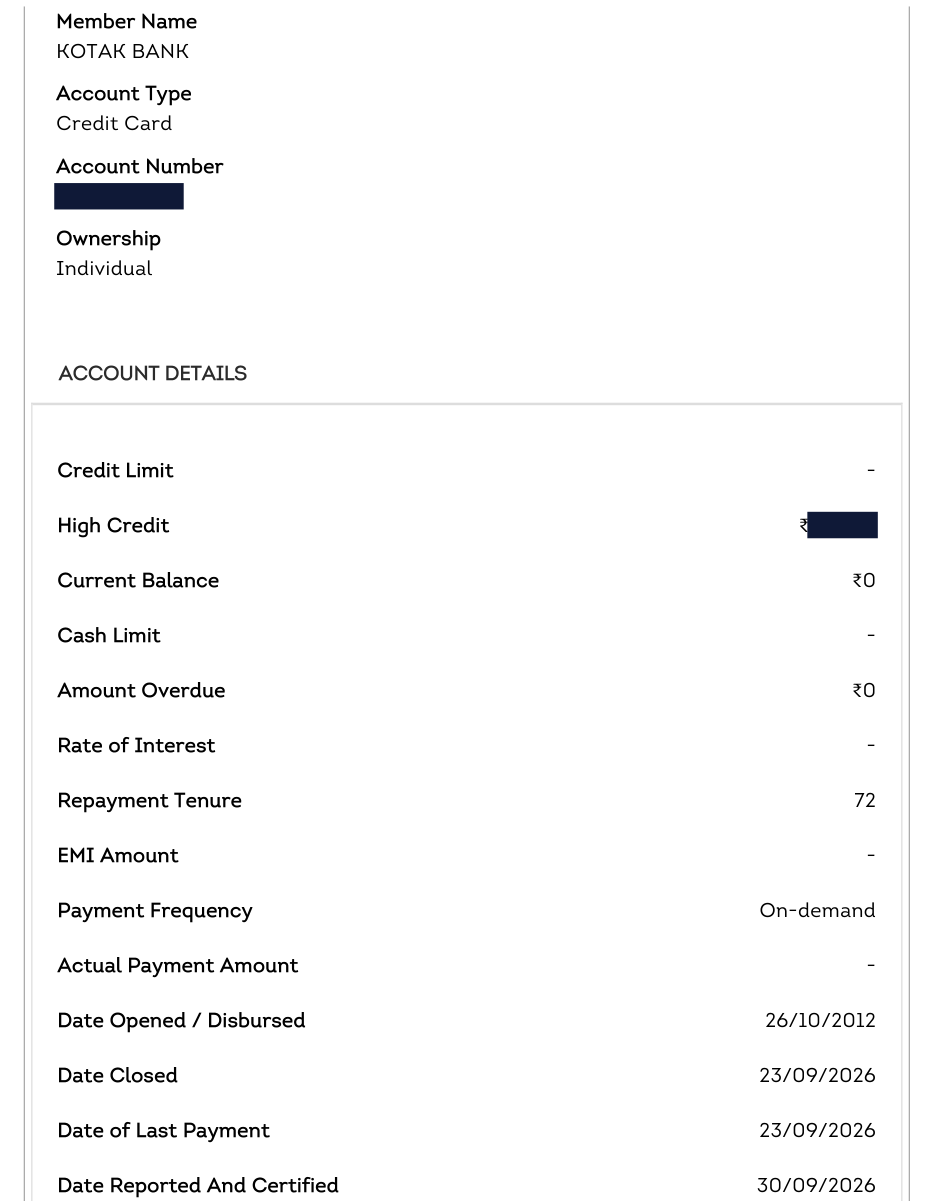
On his report pulled 8 October 2026, both accounts show a zero balance and nothing overdue, with the written-off status gone. The HDFC loan records a final payment on 16 September and closure on 19 September 2026; the Kotak card, payment and closure on 23 September 2026. His CIBIL score moved from 743 to 790, and Kotak issued a No Dues Certificate.
An honest note: nothing accurate was removed. Both accounts still show their earlier months as late in the payment history, because those months were late. What changed is that they are now reported as paid and closed instead of written off.
Report evidenceCompare the before and after reports
Choose a report to view its extracts
CIBIL score and report date
Kotak credit card: status
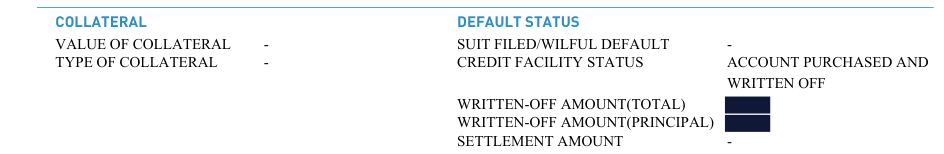
Kotak credit card: account details
HDFC personal loan: status
HDFC personal loan: account details
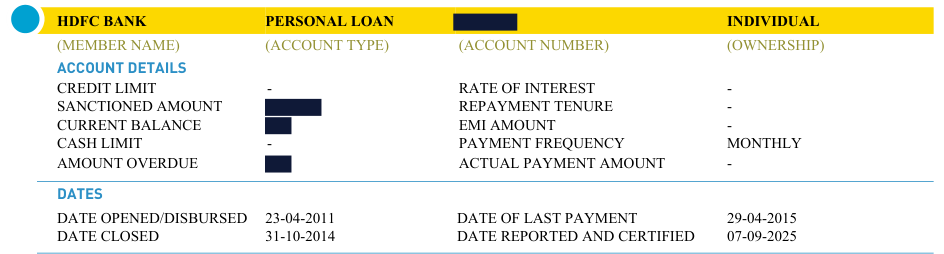
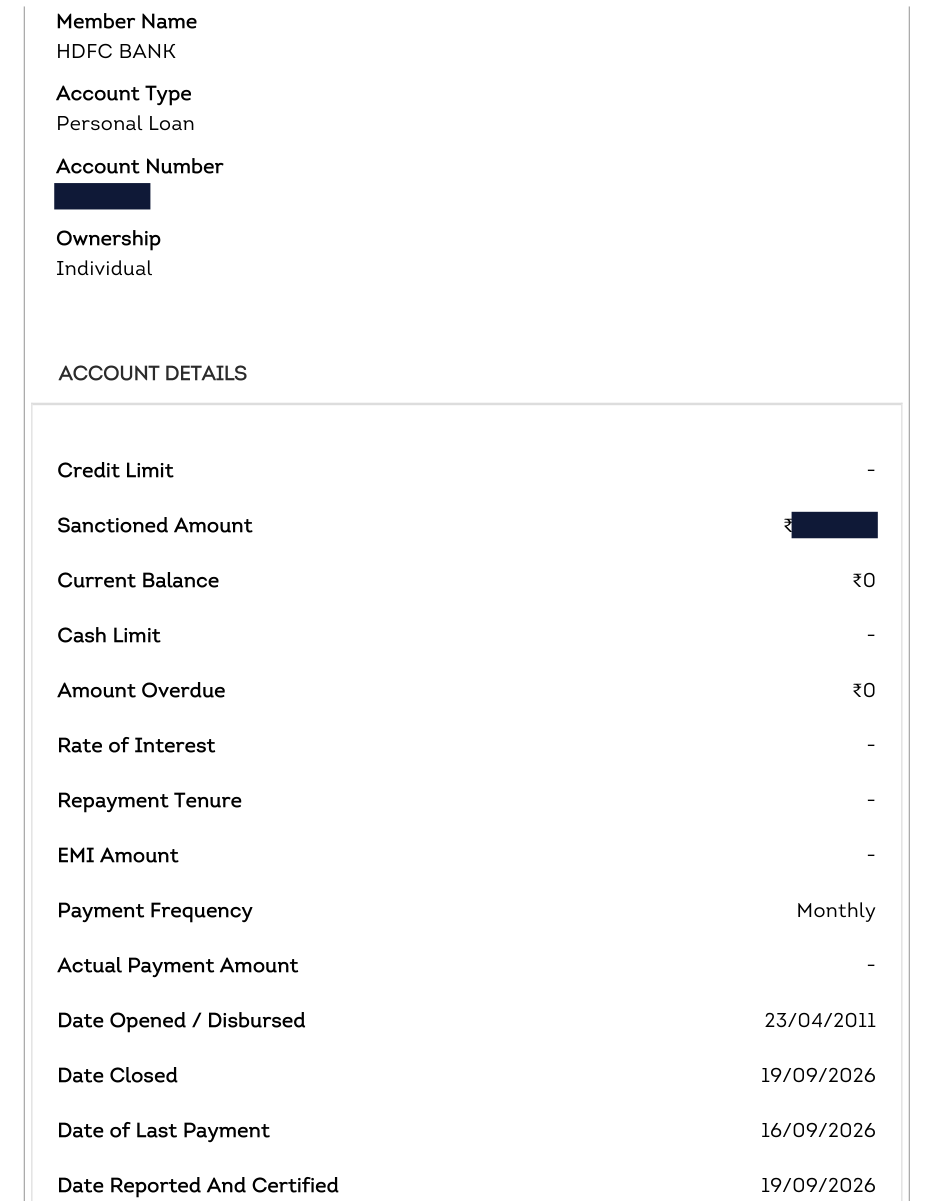
Crops from the client’s own CIBIL reports, pulled 16 September and 8 October 2026. Account and control numbers, his name and every non-zero amount are redacted; dates, statuses and zero balances are as reported. Both accounts still show their earlier months as 900 days past due in the payment history: what changed is their status and balance, not their past. The two reports use different CIBIL layouts.
His review, in his words
The process is very good and transparent. The entire team quickly helped to resolved my issues. Special thanks to Aradhana.. for constantly working on my case and a quick resolution. Thank you
Public Google review, quoted as written · view the original screenshot →
Why this case matters
Old written-off entries do not fade on their own. A card from 2012 and a loan from 2011 were still being read by lenders as written off in 2026. When the dues are genuine, the honest route is to settle them and make sure the bank reports the account as closed. Our guide on what written-off means on a report explains why lenders treat it so seriously.
Keep the paper. A No Dues Certificate is the proof that closes the argument if the status ever slips back. Our guide to the No Dues Certificate covers what it must say.
Accurate history cannot be removed. The late months stay; the status and balance are what get corrected. Timelines depend on the banks, and no score change is promised. If you want help, written-off correction starts with a written review before you pay.