
Background
Praveen N G is an ex-serviceman living in Ernakulam, Kerala. He found us through our website after his applications for an education loan kept being turned down. The banker told him why: his credit report showed a bad account.
That account was an IDFC First Bank consumer loan from 2013. His CIBIL report pulled on 6 October 2026 showed it with a Credit Facility Status of Written-off, an amount overdue, and a written-off amount, reported as recently as 4 October 2026. He told us he had cleared the loan long ago. What he did not have was the paper to show it: no NOC and no payment receipt.
What the analysis found
Akshatha Shetty took his first call, explained how we would ask for the account status to be reviewed and corrected, and onboarded him. Vaidhehi P then read his report line by line. The IDFC entry was the problem: the last payment it recorded was in October 2014, yet more than a decade later the account was still being reported as written-off with money overdue.
Without an NOC or receipt there was nothing to send the bureau as proof. A bureau dispute alone would go back to IDFC First Bank to confirm anyway, so the bank itself had to look up its own records and correct what it was reporting.
The approach
- First, the bank: we contacted IDFC First Bank and asked it to clarify and correct the written-off status. The regular channel did not produce a satisfactory answer.
- Then a formal complaint: with the issue unresolved, we raised a formal complaint against the bank and kept following up for corrective action.
- About a week after the escalation: the matter was addressed and the status corrected.
The case was onboarded on 24 September 2026 and closed on 8 October 2026. Those dates and the one-week figure come from the consultants’ account; the report dates below are evidence dates.
The outcome
On his CIBIL report pulled 7 October 2026, the IDFC First Bank loan no longer carries a written-off status or written-off amount, the amount overdue is 0, and October 2026 shows as current. His CIBIL score moved from 676 to 722 between the two pulls.
Two honest notes. First, nothing accurate was removed: the loan’s earlier months still show as late in the payment history, because that is what happened. What changed is the status the bank reports today. Second, the report still shows a small current balance on the loan, so we describe the outcome as a corrected status, not a closed account.
Report evidenceCompare the before and after reports
Choose a report to view its extracts
CIBIL score and report date
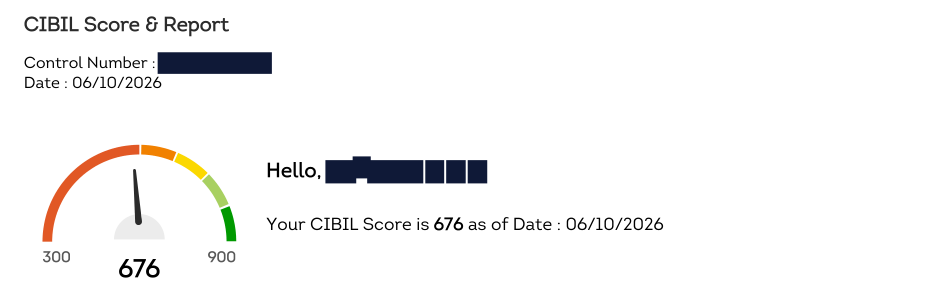
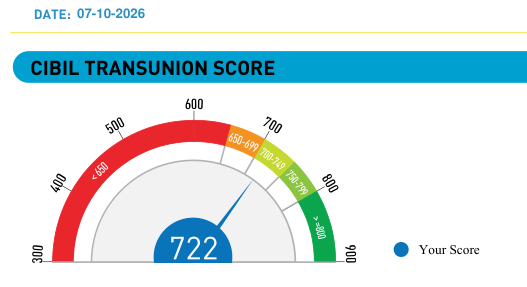
The IDFC First Bank consumer loan
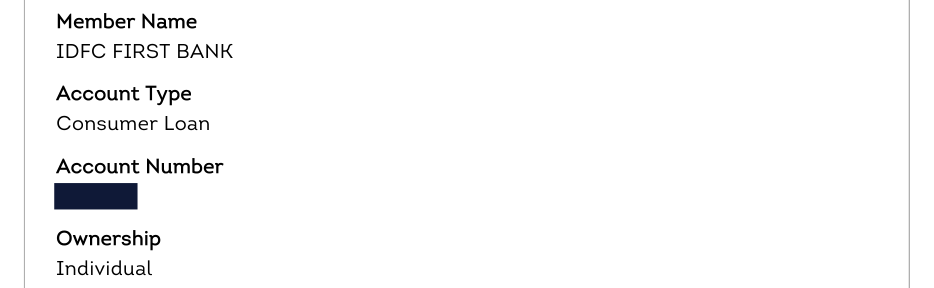
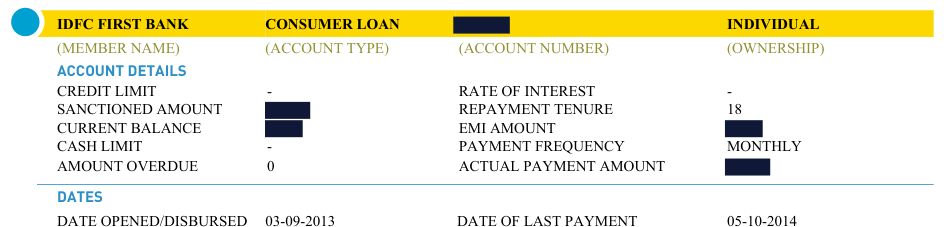
Its status: Written-off, then blank
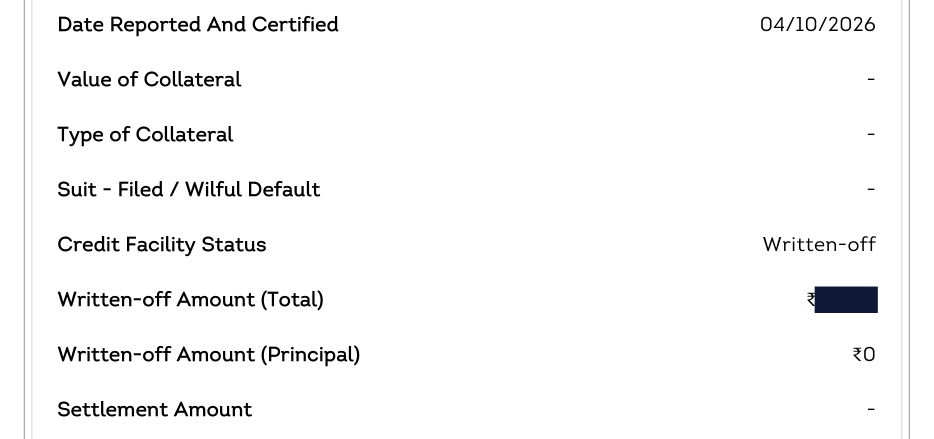
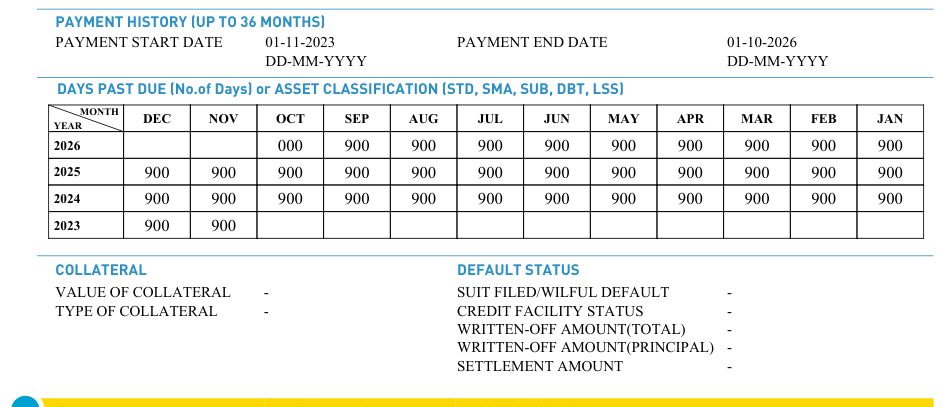
Crops from the client’s own CIBIL reports, pulled 6 and 7 October 2026. Account and control numbers, his name and every non-zero amount are redacted; dates, statuses and the payment history are as reported. The earlier months still show 900 in the payment history: the correction changed the account’s status, not its past. The two reports use different CIBIL layouts, so the same fields sit in different places.
His review, in his words
I am a ex servicemen I had cibil issue for years and now it got resolved Miss Akshatha and Miss Vaidehi were so supportive and did the job with in no time with minimal amount of fee..I am fully satisfied 🤘❤️
Public Google review on our Kochi profile, quoted as written.
Why this case matters
Losing the paperwork does not mean losing the argument. An NOC is the easiest proof that a loan was settled, but the lender holds the underlying record. When a bank keeps reporting an old loan wrongly and you have no receipt, the route is to ask the bank to check its own books, and to escalate formally when the normal channel does not answer. Our CIBIL dispute and escalation guide sets out the steps, and our guide to the No Dues Certificate explains why it is worth keeping one.
An old written-off entry can block a new loan. His banker read the IDFC line as an NPA and stopped there. What written-off means on a report explains why lenders react that way.
Accurate negative history cannot be removed. This was a status the bank corrected; the late months stay on record. Timelines depend on the lender, and no score change is promised. If you want help, written-off correction starts with a written review before you pay.