Case studies · Personal · Ernakulam · closed loans reported live
Home · Case studies · RBL loan paid in 2025, reported live till 2026
A loan he paid off in January 2025 was still reported as live in August 2026. Closed, with two more loans, in 28 days: 727 → 761
Background
Loshin Joseph works in home-loan sales in Ernakulam, Kerala. A bank manager referred him to us in August 2026 with a problem he had already diagnosed himself: accounts on his CIBIL report that did not say what they should.
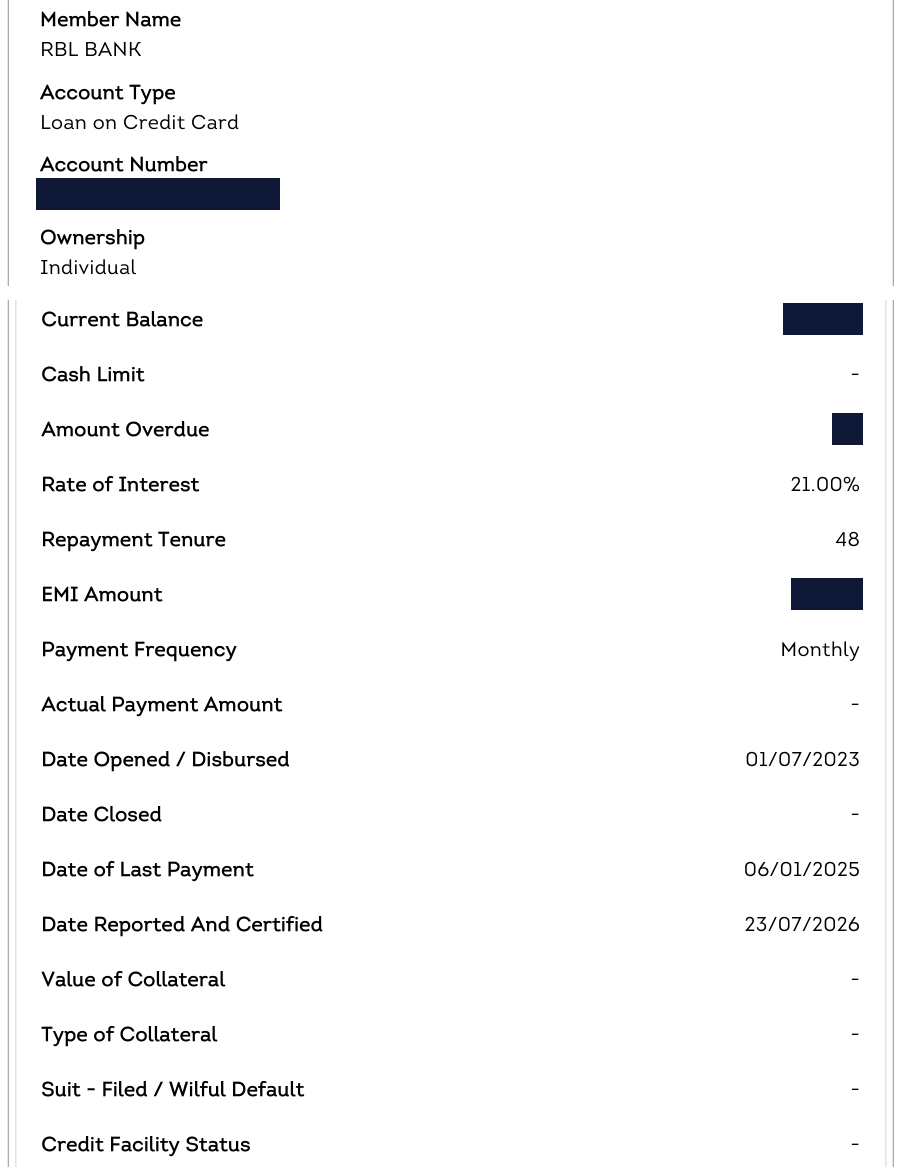
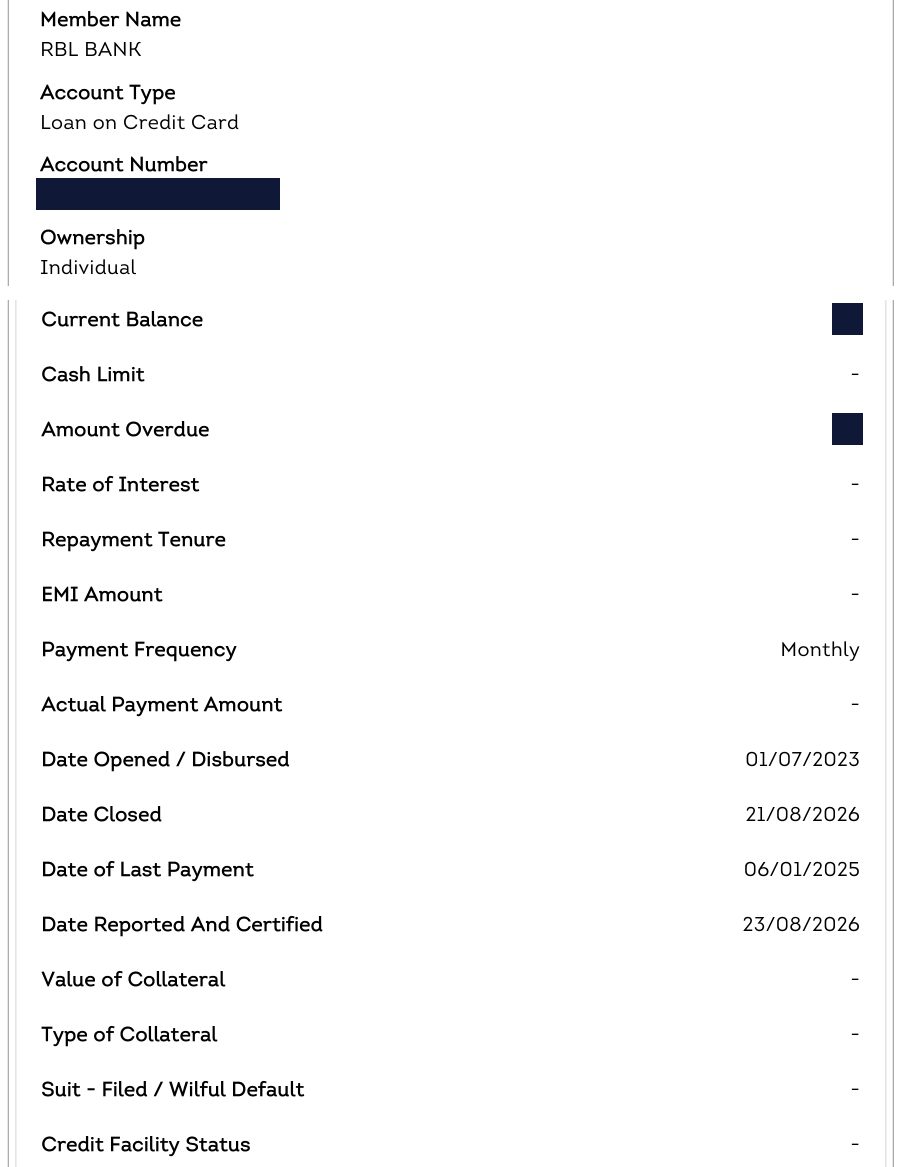
The clearest one was a loan on his RBL Bank credit card. He had paid it off in January 2025. Nineteen months later, on a report pulled on 7 August 2026, the account still carried an outstanding balance, no closure date, and a lender certification dated 23 July 2026. To any lender reading the file, it was a live loan.
Two more loans — a personal loan from a lender reported as PEOUCBT and an L&T Finance personal loan — were open and running. He wanted both cleared and closed, and the closures reflected on the report. His score on that August report was 727.
The first consultation: what he asked for, and what he did not
Akshatha Shetty took the consultation. The scope was set by him, account by account: close the RBL loan that was already paid, clear and close the two running loans, and get every change reported.
He was equally clear about what he did not want. His report also carries four accounts from 2011 to 2015 — three with HDFC Bank and one with ICICI Bank — that stand as settled: closed for less than the full amount owed. He was not willing to pay the outstanding balances on those at this time, and he asked us to leave them alone. We did. They are on his September report exactly as they were on his August one. A settled tag does not go away without the lender agreeing to a closure, and that is a decision only the client can make. What a settled status means and what it costs is on the page we point every client to.
What the analysis found
Smitha N handled the case. The RBL account was the kind of entry that looks like a default and is really a reporting gap: the client's last payment was dated 06/01/2025 on the report itself, yet the account had never been re-reported as closed, and the lender had gone on certifying it as open every month since. A paid loan that is still shown live inflates what a bank believes you owe and counts against you on every application in between.
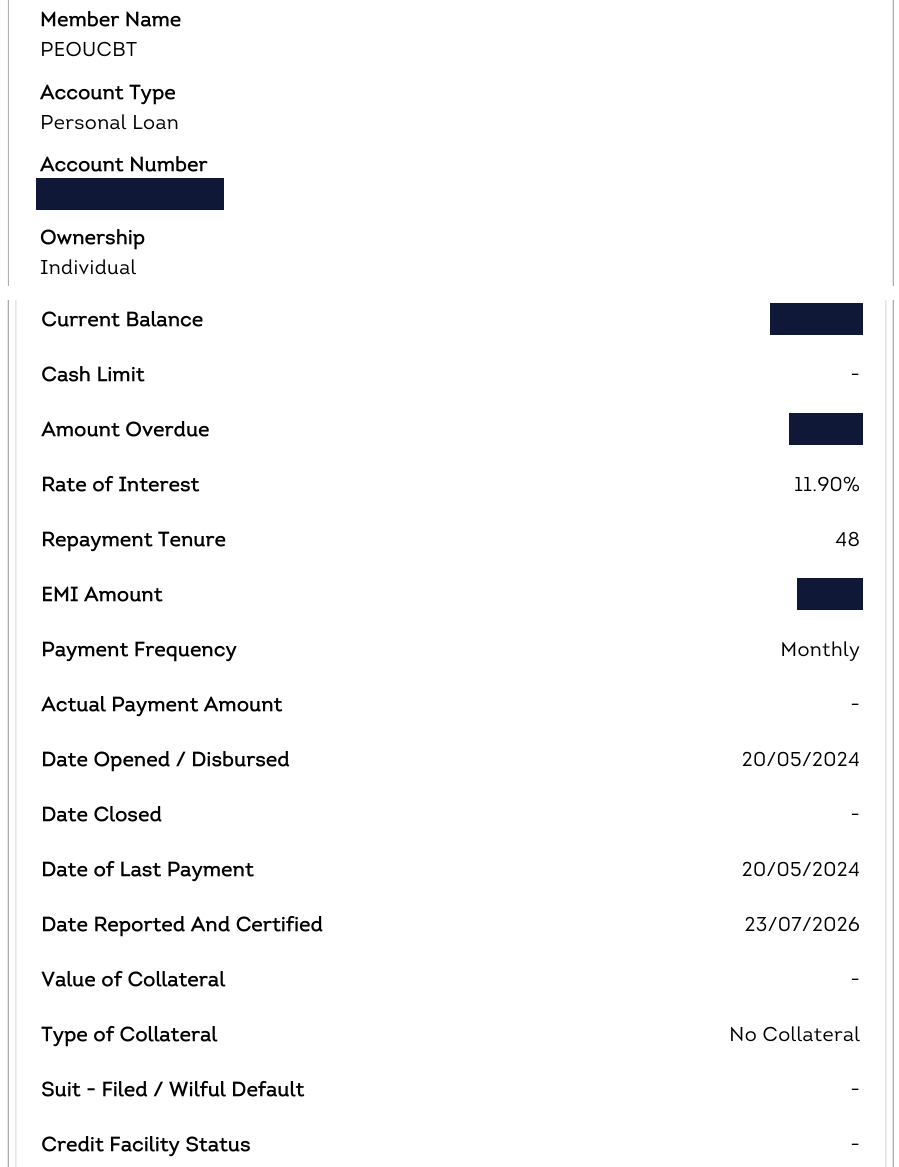
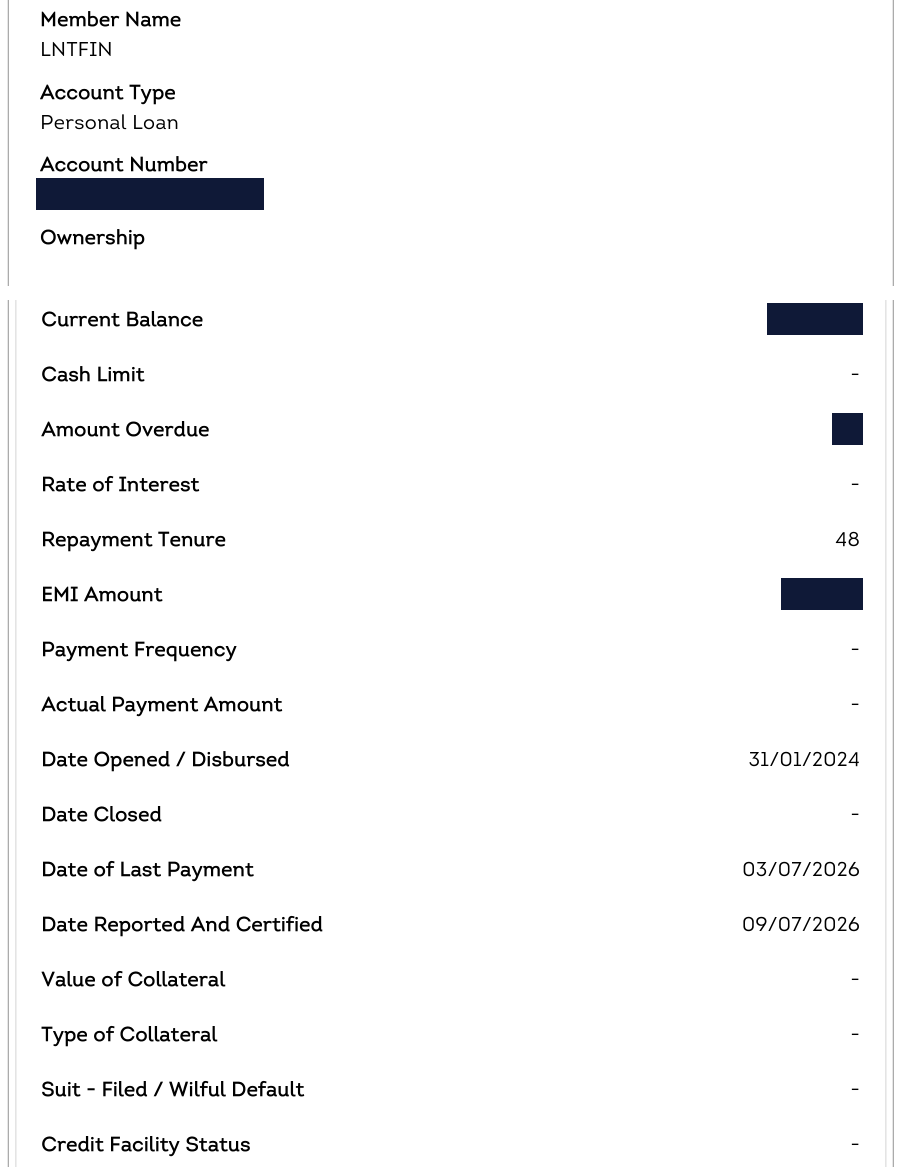
The PEOUCBT loan was behind: the August report showed an overdue amount on it and days past due for July 2026. The L&T Finance loan was current. Neither of these was a reporting error. They were genuine dues, and the only honest route for a genuine due is to pay it and have the closure reported correctly.
Closing three accounts, and getting each one reported
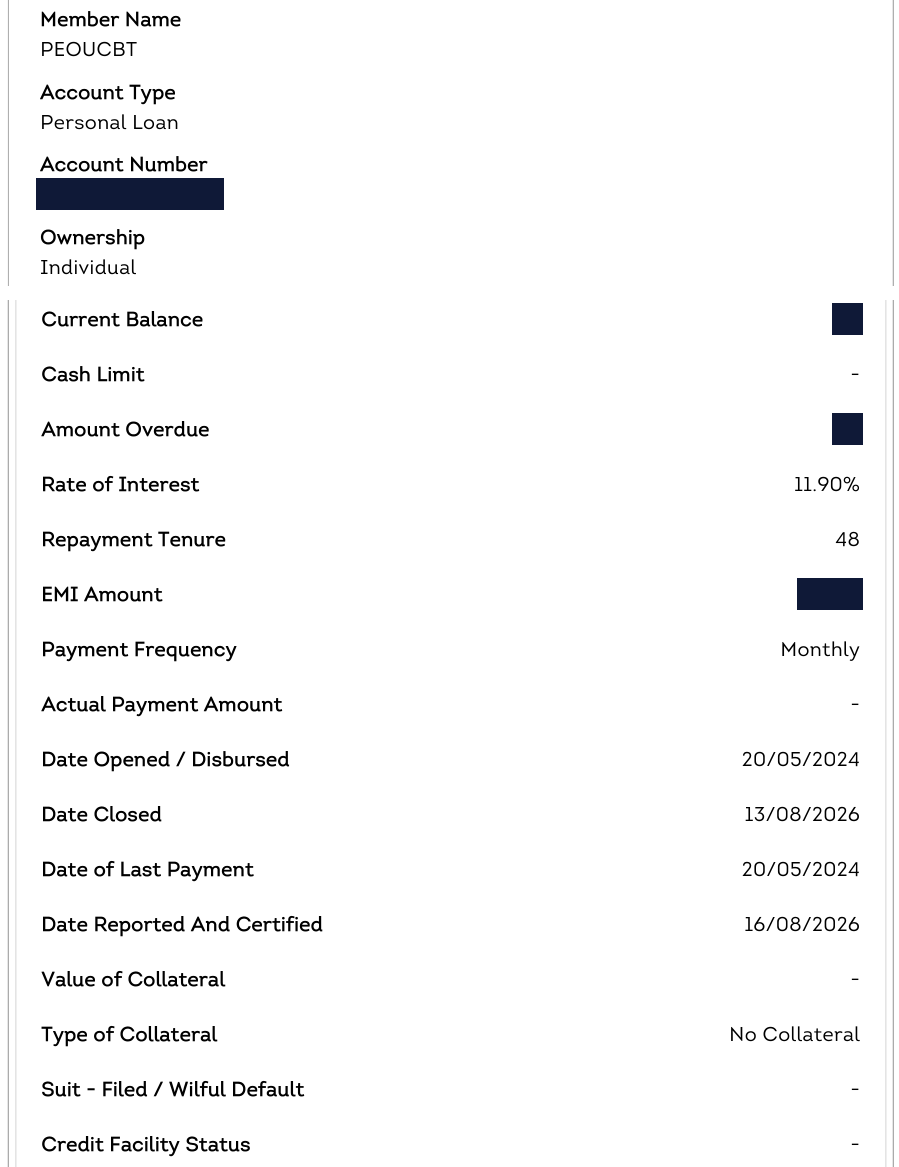
The client cleared the two running loans. PEOUCBT reported its loan closed on 13 August 2026 and L&T Finance reported its loan closed on 18 August 2026, each with a nil balance. The RBL account — the one that had been paid nineteen months earlier — was taken up with the bank for closure and re-reporting, and the bank reported it closed on 21 August 2026, balance nil, with the original last-payment date of 06/01/2025 unchanged. Nothing on the report was deleted; the lenders were made to report what had happened.
One honest detail from the same report: the July 2026 days-past-due figure on the PEOUCBT loan sits on the September report as it was reported. Accurate payment history, including a late month, stays. What changed is the status: three accounts that were open, one of them wrongly, are now closed with nil balances.
The outcome
A report pulled on 4 September 2026, 28 days after the first one, shows all three accounts closed and the score at 761, up from 727. The four settled accounts he chose to leave are unchanged, and we have said so on this page because that is what the report says.
Report evidenceView his reports — before and after+
Tap to compare the two reports
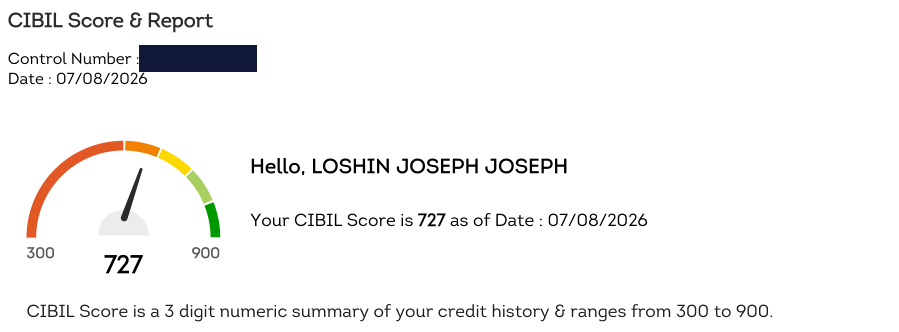
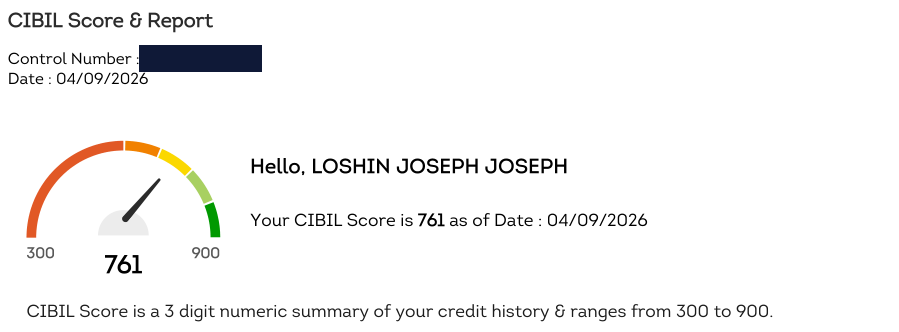
RBL Bank loan on credit card — paid 06/01/2025, the closure date
PEOUCBT personal loan — overdue in August, closed 13/08/2026
L&T Finance personal loan — open in August, closed 18/08/2026
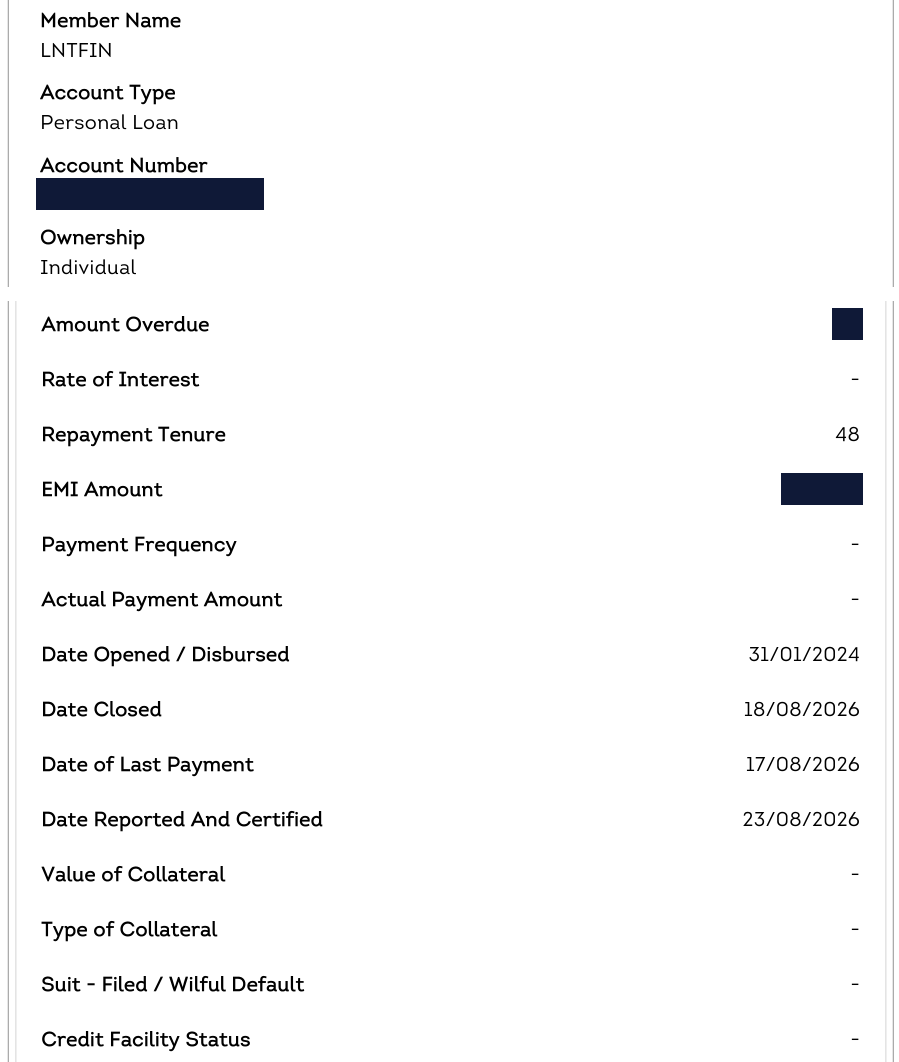
Extracts from the client's own CIBIL reports, pulled 7 August and 4 September 2026, published with his written consent. Account numbers, amounts, control numbers and identifiers are redacted; dates and statuses are as reported.
His review, in his words
Kenstone capital especially Akshatha and Smitha went above and beyond to fix the errors on my credit report. They took the time to explain the entire process, answered all my questions, and delivered exactly what they promised. Exceptional service!"They successfully resolved the issues on my credit report …
Public Google review, quoted as it appears · view the original screenshot →
Why this case matters
Two reasons. First, a paid loan that is still reported as live is one of the commonest problems on an otherwise clean report, and one of the least visible: no late payments, no bad status, just an account the lender never closed. It drags utilisation, inflates the debt a bank thinks you carry, and sits there until someone makes the lender re-report it. Nineteen months, in this case. Checking the closure date against your own payment records is the first thing to do on any report you read. Second, it is a case about scope chosen by the client. He could have been sold work on his four settled accounts; he said no, and the page says so. The score moved because three accounts were closed and reported truthfully, not because anything was removed — and the settled tags he kept are a reminder of what a settlement costs, which is why we put that cost in writing before anyone signs one.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
By Smitha NStuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
 By Michelle Juanita
Three delinquencies, two banks — one corrected rank
CMR 9 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad
Looking for local help after reading this Ernakulam case? See Kenstone Credit in Kochi for the current contact and visit arrangements. This client’s outcome is not a promise of similar results.
Useful links