Case studies · Personal · Hyderabad · settled accounts
Home · Case studies · Settled tags cleared, SBI Card error removed
Two settled loans cleared, one SBI Card tag the bank admitted was wrong — and the dispute remark that outstayed them all
Background
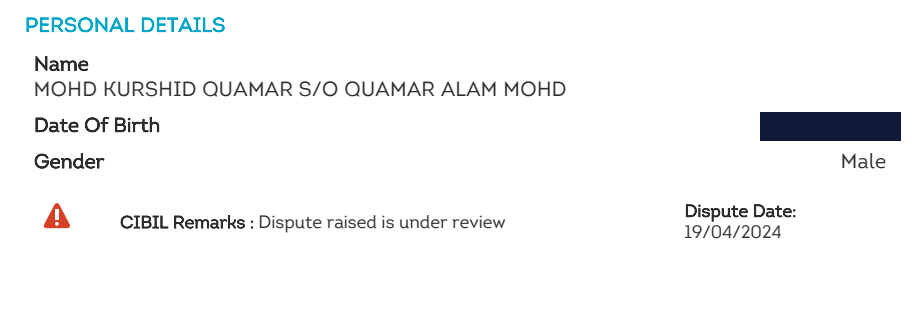
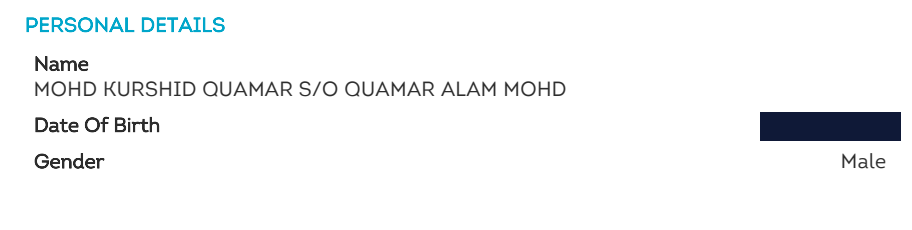
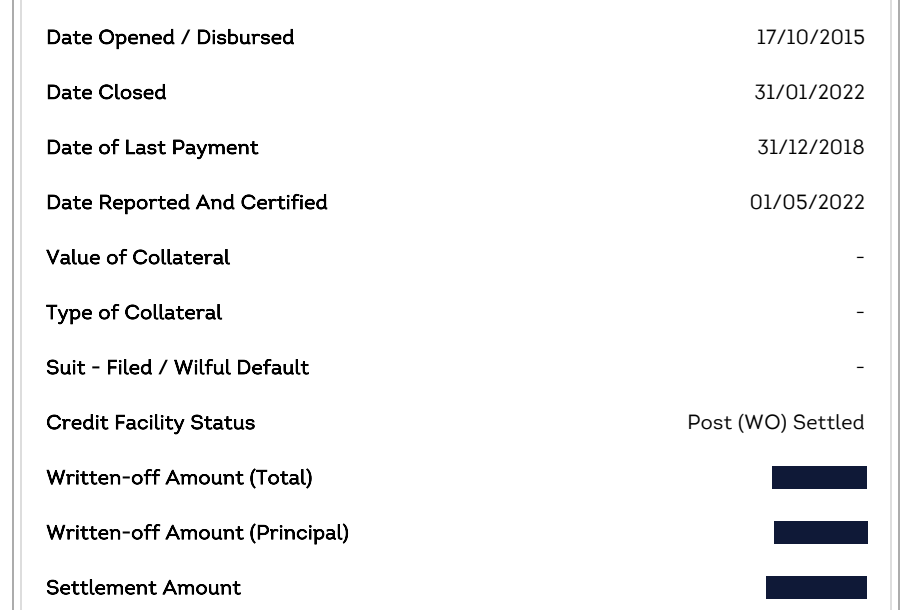
Mr. Mohammad Kurshid Quamar of Hyderabad came to us with a report that had three accounts wearing a settled tag — and a loan he could not get because of them. A "settled" status tells a lender that less than the full amount was accepted and the file was closed on that basis; underwriters read it as a default that ended in a compromise, whatever the score says. His October 2025 report carried the tag on an HDFC Bank personal loan (Post (WO) Settled), a Kotak Mahindra Bank personal loan (Settled) and an SBI Card credit card (Post (WO) Settled). Sitting above all three was a fourth problem he had not noticed: a CIBIL remark reading "Dispute raised is under review", dated 19 April 2024 — a year and a half old, and still on the report.
The first consultation: one account at a time
Akshatha Shetty, Sr. Credit Consultant, took the initial website enquiry. The client had faced repeated rejections for a large loan. He told her he had been informed that the accounts were closed in the lenders' systems, with nothing left to pay. He had not understood why his CIBIL report still showed Settled entries or how those entries could affect a new loan application.
Akshatha explained the difference between an account being closed in a lender's system and a settled status on the credit report. For the genuine settlements, the route involved agreeing the required payments with the lenders and having the accounts re-reported truthfully. An incorrect status, as Michelle established on SBI Card, needed a correction instead.
The client could not pay all the settled accounts at once. Akshatha proposed taking them one account at a time, making the next steps manageable. He agreed to proceed and completed the settlement repayments over seven to eight months. Michelle handled the lender follow-up and reporting work described below; the SBI Card error required no payment.
What the analysis found
After reviewing his reports, I identified the three accounts that needed attention — and that each needed a different approach. The HDFC and Kotak loans were genuine settlements: real dues had been compromised, the write-off amounts were recorded, and no dispute would move them. The honest route there is the one we set out on our settlement page: pay what the bank will accept as full closure and have the account re-reported truthfully. The SBI Card account was different. The client was confident he had closed it with nothing pending, and the report agreed with him in every field except the status — a nominal ₹1 sat against the written-off and settlement amounts, the kind of entry that is a reporting artefact, not a settlement. That one was a correction, not a payment.
Clearing the HDFC and Kotak accounts
The first major concern was the HDFC Bank personal loan, which carried a substantial outstanding amount. I reached out to the bank, obtained the foreclosure details, and explored the possibility of a waiver on the outstanding. We followed the same process with Kotak Mahindra Bank — foreclosure details first, then the waiver conversation. The client was willing to make the required payments, and once the arrangements were in place he cleared both accounts. The Kotak account now shows a closure and last-payment date of 18 August 2026; HDFC re-reported the account on 20 August 2026 with the settled status gone from the status field. Nothing was deleted here — dues were paid and the accounts re-reported as they now stand.
Correcting the SBI Card account
The SBI Card account presented a different situation. The client was sure he had closed it and had no dues pending, yet it reflected as settled. I raised a complaint with SBI Card and asked them to investigate the reporting. After reviewing the matter, SBI Card acknowledged the error, apologised for the incorrect reporting, and removed the settled status. The client did not have to pay anything on this account — the correction was re-reported on 4 November 2025, the first of the three to clear.
Quick updates after payment
Once the HDFC and Kotak payments were completed, I followed up with both banks immediately so the updated status reached the bureaus without the usual drift. Both accounts were updated within the next reporting cycle, and the corrections were reflected in his reports without unnecessary delay — the part of the engagement Mr. Kurshid said he valued most.
Getting the final dispute remark removed
Even with all three accounts cleared, one thing still sat on the report: the "Dispute raised is under review" remark from April 2024. A remark like this tells a lender the file is contested, and it was causing a problem while he was applying for loans. We had already followed up with CIBIL more than once and been assured it would go; it stayed. I contacted the CIBIL team again, set out the entire history in one place, and asked for the remark to be removed at the earliest, given how long we had been following up. CIBIL took note and removed it immediately. That cleared the last item still affecting the report.
The outcome
Three settled tags became none — two by honest payment and re-reporting, one by a bank correcting its own error — and the stale dispute remark came off. The score is not the story in this case and did not move meaningfully between the two reports (738 → 733); what changed was the four fields an underwriter actually reads. With the accounts cleared and the incorrect SBI Card status removed, the major issues affecting his loan eligibility were resolved, and his updated profile allowed him to become eligible for a loan. The before and after, in his own report extracts, is below.
Report evidenceView his reports — before and after+
Tap to compare the two reports
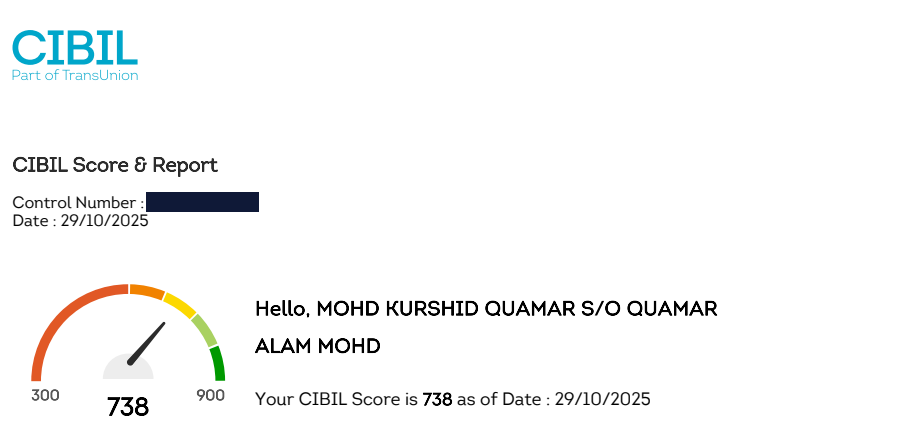
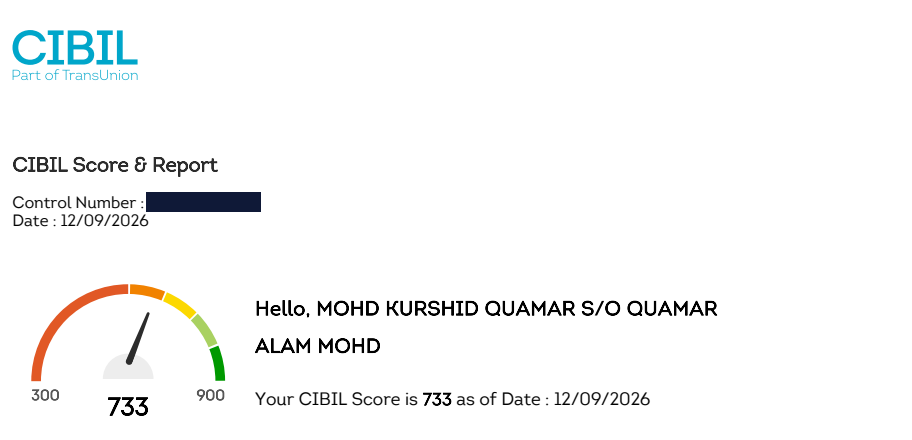
The CIBIL remark on the personal-details block — present in October, gone by September
HDFC Bank personal loan — the status field
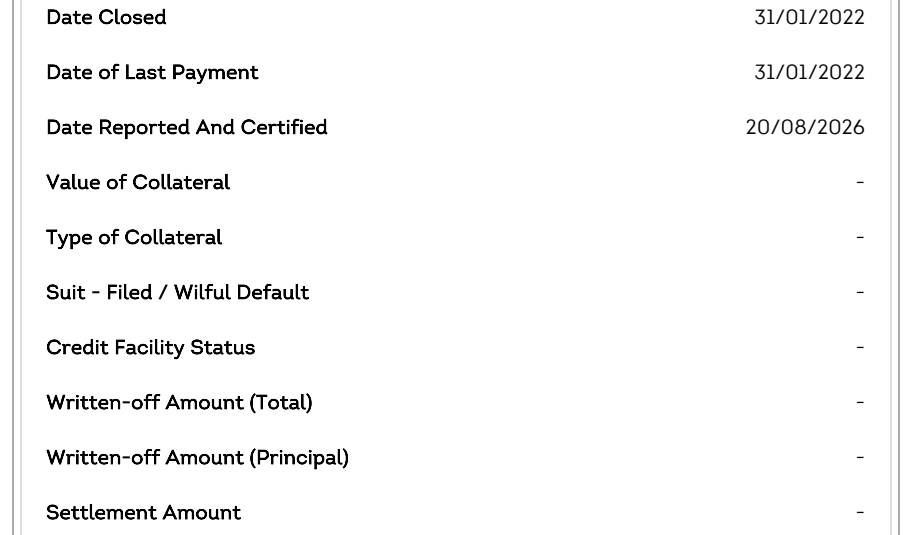
Kotak Mahindra Bank personal loan — the status field
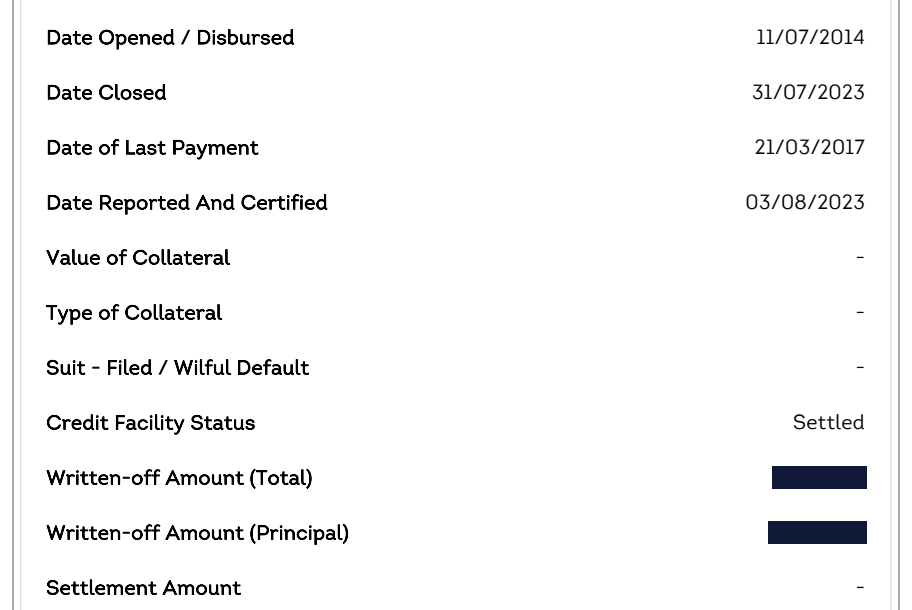
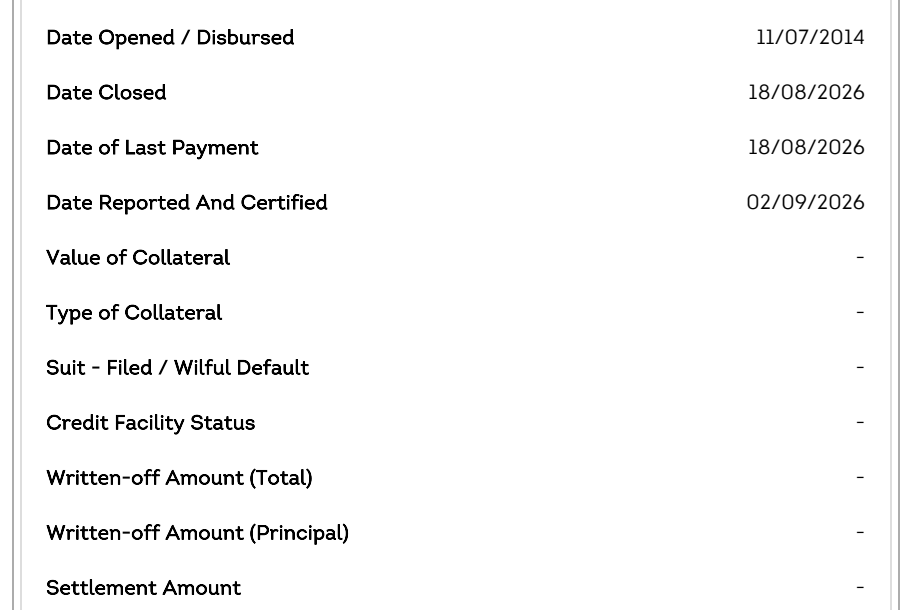
SBI Card credit card — the status field (the block runs across a page break in the report and is shown joined)
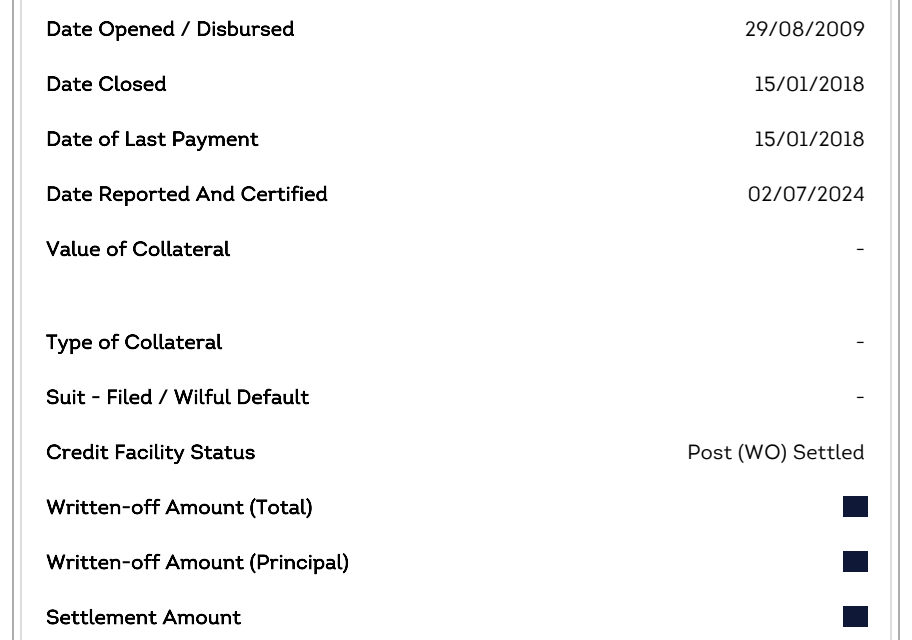
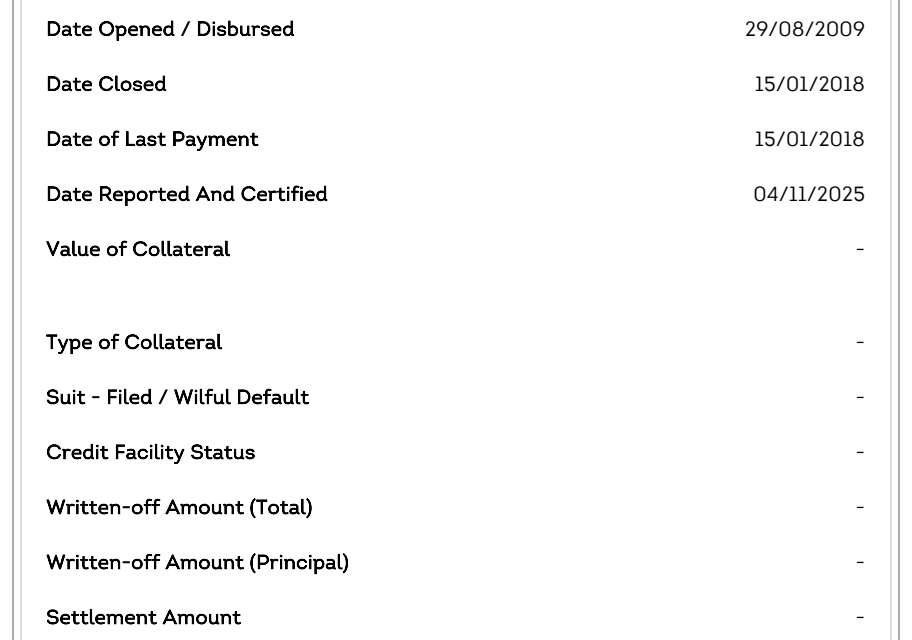
Raw extracts from Mr. Kurshid's own TransUnion CIBIL reports, labelled by report pull dates. Account numbers, amounts, date of birth and identifiers are redacted; the banks are named in this article. Published with his consent.
His review, in his words
I honestly don't have enough words to thank all of team member of kenstone for the way they deal with customers and, more importantly, for the way each and every individual behaves and supports to customer.
Whenever you connect or speak with any one of them, you get this feeling that, "Yes, we have reached the right place." No matter what kind of problem you may have, you always feel confident that they will take care of it.
Of course, the professional and work-related support is excellent, but what really stands out is the personal and moral support that they provide as well. That is truly exceptional.
So, whenever any one of you faces an issue or needs any kind of correction or rectification, please go ahead and reach out to them immediately—without doubting, without overthinking, and without hesitation.
I can genuinely say that you will feel supported and confident that you are in the right hands.
Public Google review on our Bengaluru profile · view the original screenshot →
Why this case matters
Three reasons. First, the same word on three lines needed three different tools: two genuine settlements that only payment and truthful re-reporting could change, and one "settled" that was a bank's error and needed a complaint, not a rupee. Telling them apart is the analysis — and it is why we explain what a settled status actually means before anyone pays anything. Second, it is the honest version of a settled-status case: nothing here was deleted. Dues on the HDFC and Kotak loans were paid; the SBI Card correction happened because the bank, made to check, agreed it was wrong. Third, the dispute remark. A "dispute under review" flag can outlive the dispute by years, and lenders read it as an open contest on the file. It is not something a bureau removes on its own — it took a complete history put in front of the right team, after the accounts themselves were already clean. If a settled tag is sitting on your report, start with which kind it is.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
By Michelle JuanitaThree delinquencies, two banks — one corrected rank
CMR 9 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad
Looking for local help after reading this Hyderabad case? See Kenstone Credit in Hyderabad for the current contact and visit arrangements. This client’s outcome is not a promise of similar results.
Useful links