Case studies · Personal · Ernakulam · settled accounts
Home · Case studies · Settled tags from 2012 cleared
Settled in 2012, still tagged in 2026: two auto loans cleared after the bureau rejected the disputes

Background
Madhu K A is self-employed in Ernakulam, Kerala, and came to us with a problem he had already narrowed down to two accounts. His CIBIL report, pulled on 16 July 2026, carried two car loans from 2007 — one from Kotak Prime, one from ICICI Bank — both closed in 2012 and both still showing a Credit Facility Status of Settled. His score on that report was 738.
A settled status means the lender accepted less than the full amount and closed the account. It is one of the first things a lender looks for, and it does not fall off the report with time. These two had been there for fourteen years, next to a current vehicle loan, a Mudra loan and a guarantee on a business loan — an active file on which a 2012 settlement still gets asked about.
What the analysis found
Vaidhehi P handled the case. The two accounts were not the same problem. On the Kotak account, the client had already cleared the required amount, so the Settled tag was out of date: the account should have been reported as closed in full. On the ICICI account there was still an amount pending, and no lender will change a settled status while something remains unpaid. The sequence for that one had to be payment first, correction second.
Kotak: a rejected dispute, then an escalation
We raised a dispute with the bureau asking for the Kotak status to be corrected. It was rejected, and the Settled tag stayed. That is a common outcome, and it is worth understanding why: the bureau only relays a dispute to the lender, and if the lender does not confirm a change, the bureau closes the dispute as it stands. So we escalated the matter against the bank through the PMO grievance portal and followed up with the lender until the correction was processed and the account updated.
ICICI: pay the pending amount, then correct the status
We coordinated with the bank to establish exactly what was pending, and the client paid it promptly. We then filed the dispute for the status to be updated — and it was rejected too. We escalated through the same route and followed up with the lender until the update was made. The report pulled on 28 August 2026 shows the result on the ICICI account: Credit Facility Status blank, last payment 24/08/2026, account closed 24/08/2026, re-certified by the bank the same day. Nothing was deleted. A loan settled in 2012 was paid in full in 2026 and the bank reported it as closed.
The outcome
Both accounts were corrected, and we checked the client's reports with all four bureaus — TransUnion CIBIL, Experian, Equifax and CRIF High Mark — to confirm the updates had reached each of them. One honest note on the number: his score was 738 on the July report and 738 on the August one. The scoring factors listed on the August report point to his live borrowing — a high proportion of outstanding accounts and a recent balance build on a card — not to the two old loans. What changed is what a lender reads about him: two Settled tags are gone, and the account history behind them is reported as it happened.
Report evidenceView his reports — before and after+
Tap to compare the two reports
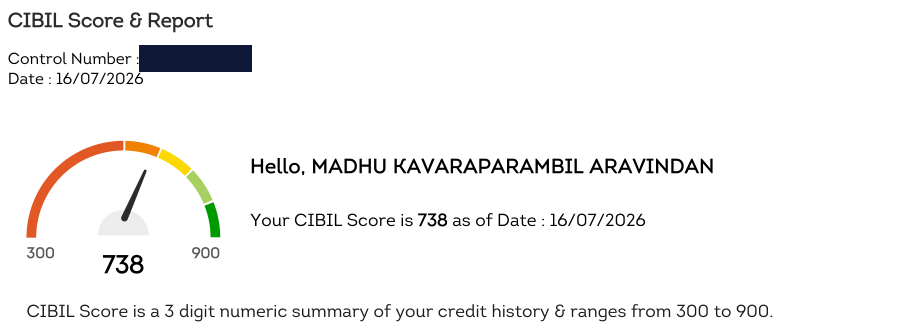
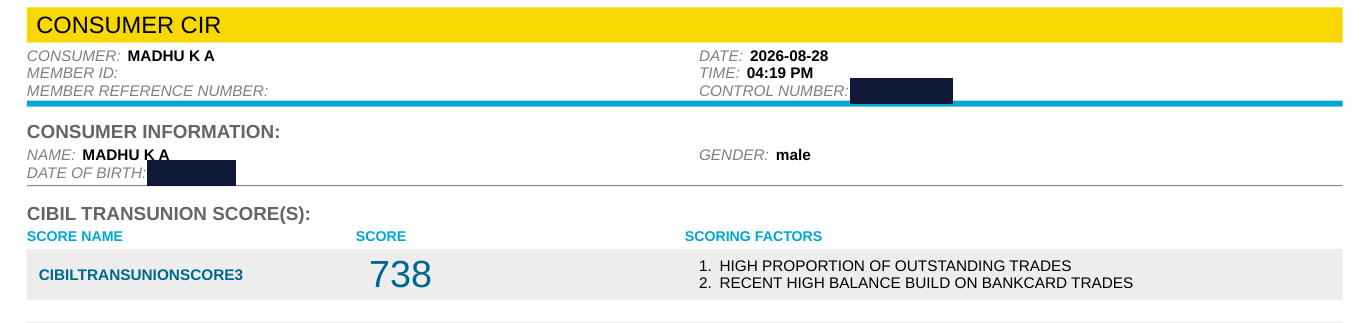
ICICI Bank auto loan — settled and closed in 2012; paid in full and re-reported closed on 24/08/2026
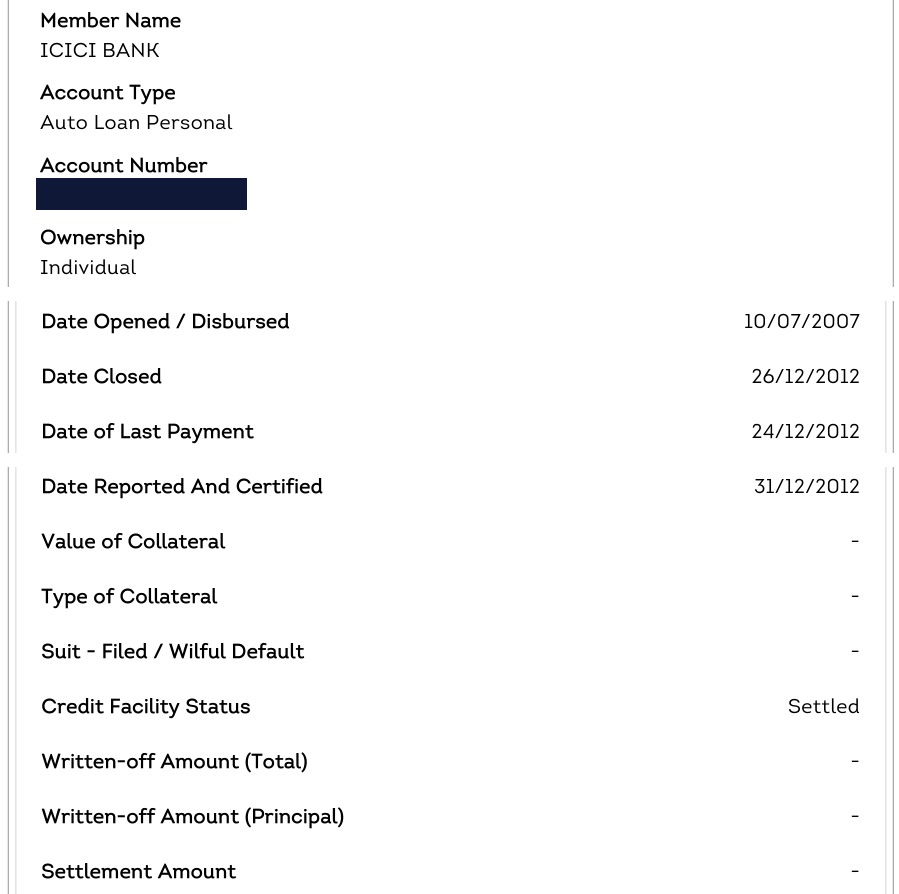
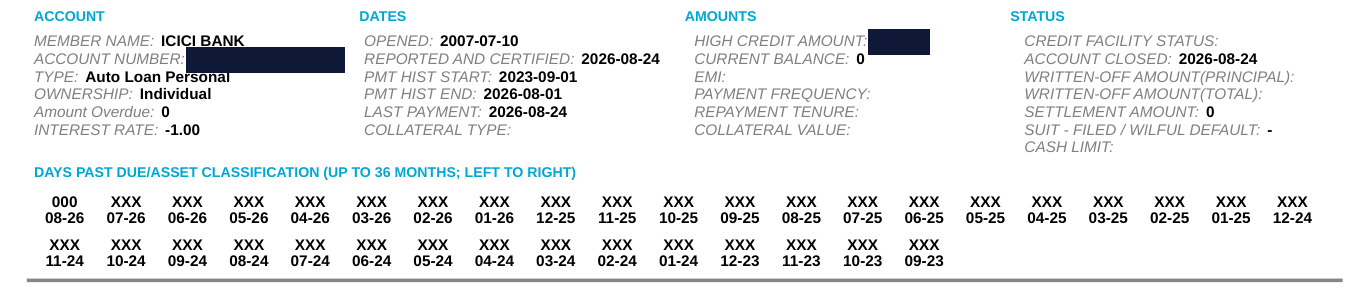
Extracts from the client's own CIBIL reports, pulled 16 July and 28 August 2026, published with his consent. Account numbers, amounts, control numbers and identifiers are redacted; dates and statuses are as reported. The August pull is CIBIL's condensed report format, which is why the two extracts look different. The Kotak correction is not shown: it had not yet reached the 28 August CIBIL pull, and we publish only what a report in hand shows.
His review, in his words
I had two issues across all four credit bureaus, and I contacted Kenstone for assistance. My assigned executive, Vaidehi, provided extraordinary follow-up and escalation support with the respective banks. She was always available whenever I needed to speak with her.
Because of her consistent follow-ups and timely emails, all my issues across the four bureaus were successfully resolved. Vaidehi had promised me that she would get my issues cleared by the end of August, and she kept her word.
Thank you so much, Vaidehi, and the entire Kenstone team, for your excellent support and dedication. I highly recommend Vaidehi and Kenstone to anyone looking for reliable and professional credit bureau assistance.
Public Google review, quoted as it appears · view the original screenshot →
Why this case matters
Three things. First, a settled tag does not expire. These were 2012 closures on a 2026 report, and they would have been on a 2030 report too. The only way a Settled status changes is the lender reporting something different — which means the dues are paid in full, or the lender accepts that the tag was wrong, as it was on the Kotak account. Second, a rejected bureau dispute is not the end of the road. Both disputes here were rejected because the bureau can only relay, and the lenders did not respond. The correction came from escalating against the lender and staying on it — the route we set out in our dispute escalation guide. Third, it is a case where the score did not move, and we say so. What a lender sees on the file changed; the number, driven by his current borrowing, did not. We publish the report extracts because that is a more honest measure of the work than a before-and-after score, and because clearing a settled status is about what the record says, not a promise about a number.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
 By Michelle Juanita
Three delinquencies, two banks — one corrected rank
CMR 9 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad
Looking for local help after reading this Ernakulam case? See Kenstone Credit in Kochi for the current contact and visit arrangements. This client’s outcome is not a promise of similar results.
Useful links