Case studies · Personal · Nashik, Maharashtra · suit-filed flag
Home · Case studies · Suit Filed removed in eight days
A Suit Filed flag he had already paid off — removed in eight days: 662 → 710

Background
Mr. Santosh Chavan of Nashik, Maharashtra, came to us with a new loan application stalled by two lines on his report. The first was the harshest flag the consumer report carries: his AAVASFIN housing loan showed "Suit Filed" — even though the dues behind it had been cleared back in April 2025, more than a year earlier, and his payment grid ran clean month after month. The second: a SHRIRAMFIN business loan, paid off with the NOC in hand, still reflecting a balance and an overdue. Rabia Basri took the onboarding, set the expectation honestly — discrepancies with evidence behind them are correctable — and the file landed on my desk on 10 August 2026.
Eight days, two tracks
Both tracks started the same day. For the housing loan, a correction demand went to the lender with the clearance evidence, and a bureau dispute was raised in parallel for the record. AAVASFIN replied within two days — with a wrinkle worth documenting: the email ID on their file was outdated, so nothing sent to it would ever have reached the client. We had the current ID registered immediately and the rectification continued without losing a day. For the business loan, the correction request went to SHRIRAMFIN with the NOC attached — and when two days passed without movement, the matter was escalated through the PMO grievance mechanism rather than waiting politely in a queue.
The outcome
The report refreshed on 17 August 2026 — roughly eight days after the case was taken up — with both lines corrected: the Suit Filed flag removed from the housing loan, and the business loan reporting closed at zero balance, zero overdue. His score moved from 662 to 710, and the loan application that had been stalled had nothing left standing in its way. It is the fastest resolution in this library — and the honest reason it was fast is that the evidence was complete before we started: dues genuinely cleared, NOC genuinely in hand. Speed follows proof.
Report evidenceView his reports — before and after+
Tap to compare the two reports
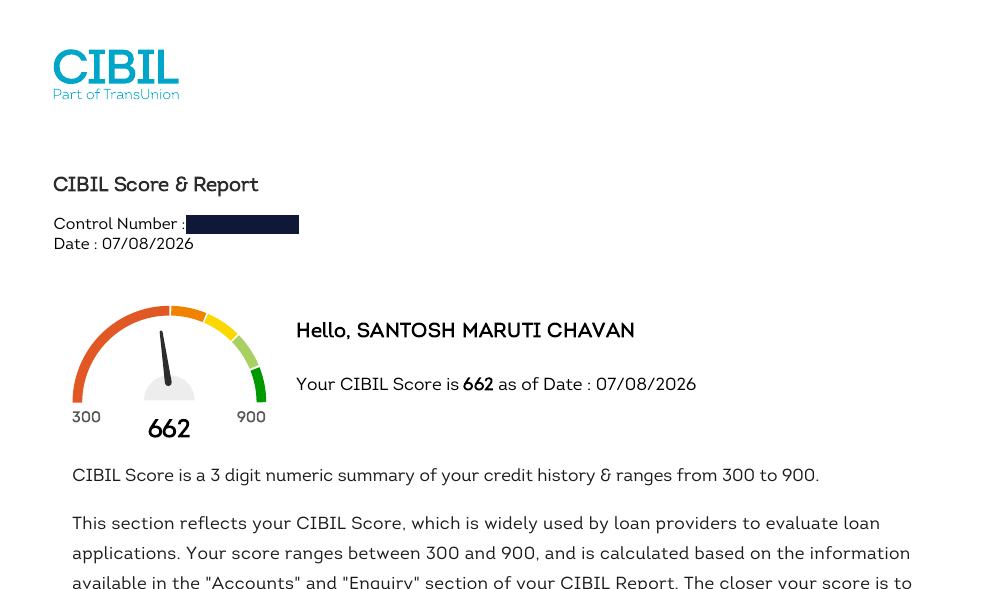
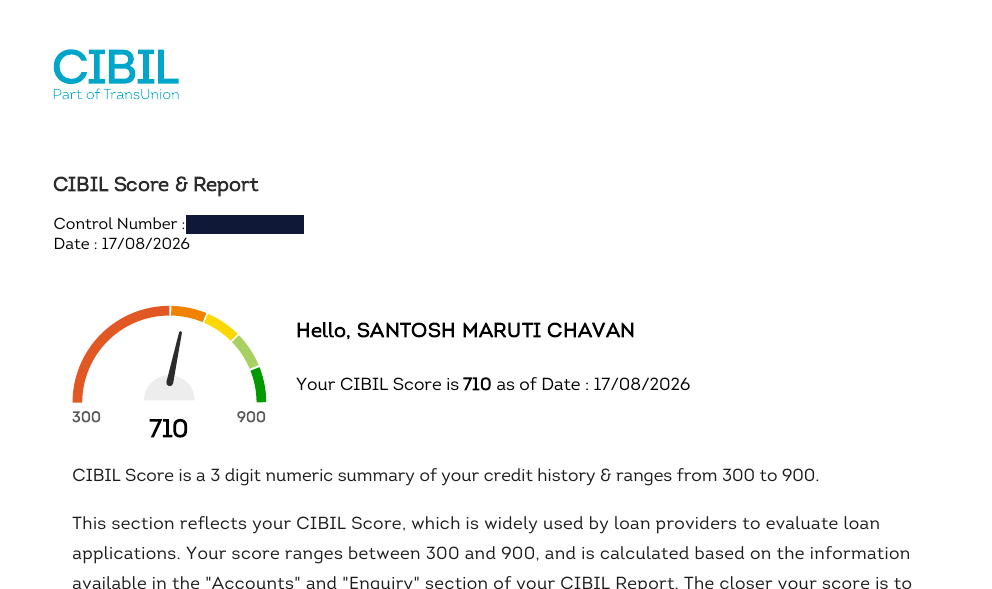
The AAVASFIN housing loan — the Suit-Filed field, 7 August versus 17 August
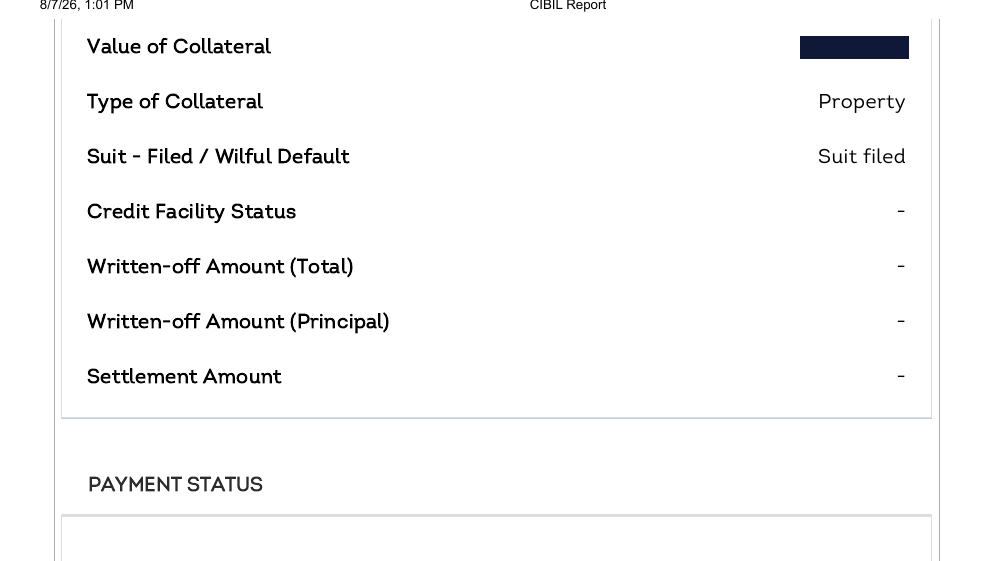
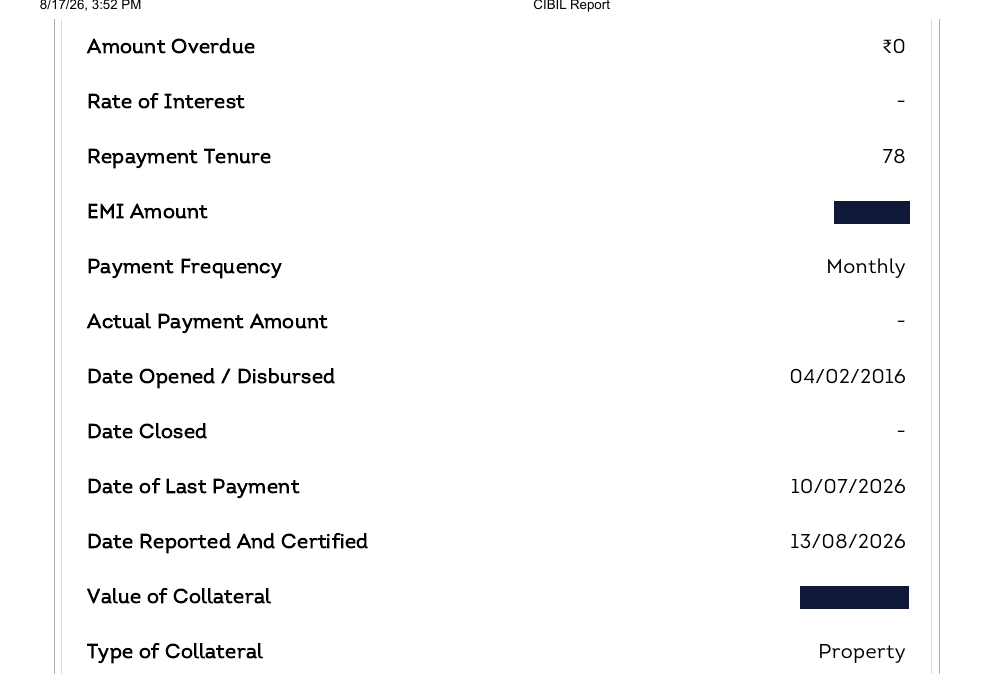
The SHRIRAMFIN business loan — dues showing after the NOC, then closed at zero
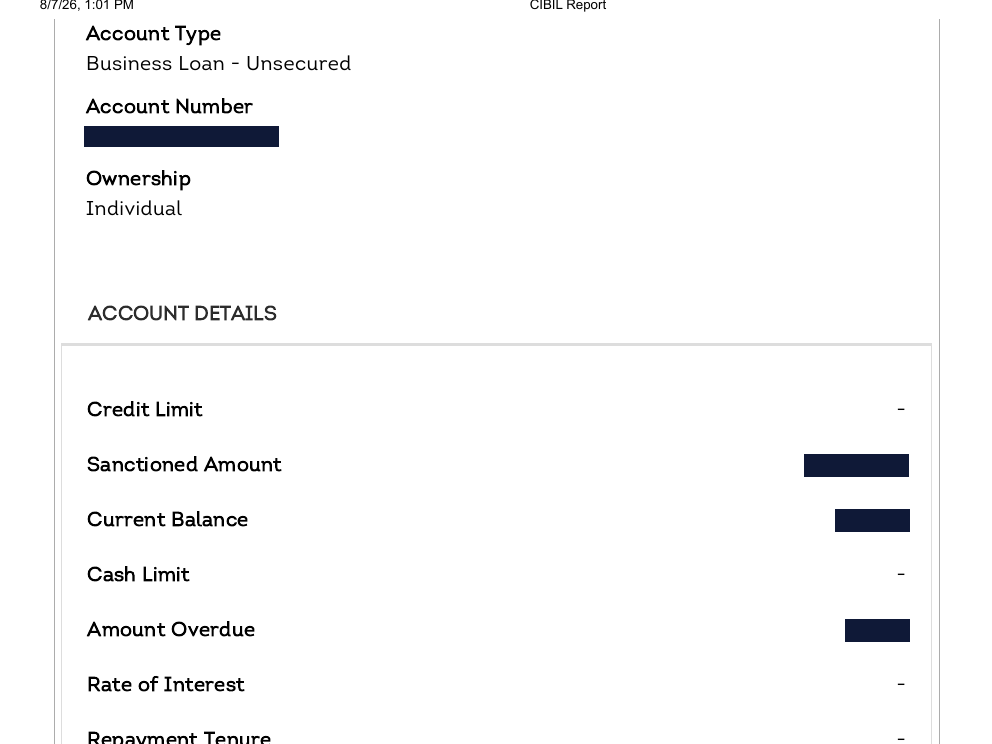
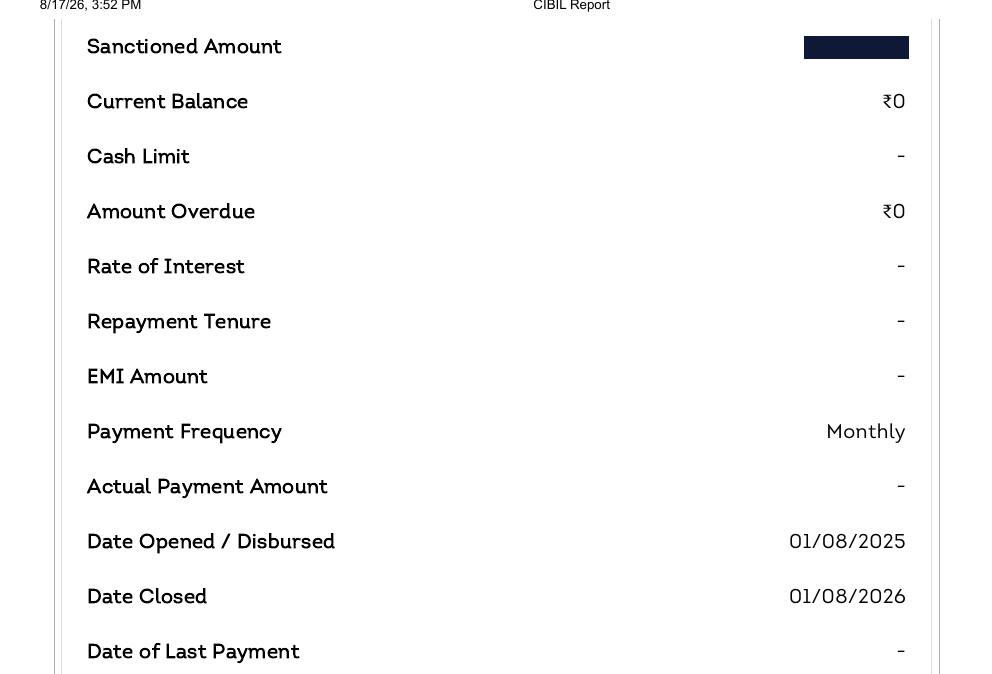
Raw extracts from Mr. Santosh's own TransUnion CIBIL reports, labelled by pull dates — ten days apart. Account numbers, amounts and identifiers are redacted; the lenders are named in this article. Published with his consent.
His testimonial, in his words
Recorded by Mr. Santosh — 33 seconds, captions available. His transcript, verbatim:
Hello. I am Santosh Chavan from Nashik, Maharashtra. I had a problem in CIBIL, so Rabia Ma'am and Rudolph Sir, they helped me a lot. My — it was a negative flag of the suit file. They removed this suit, this flag, within eight days. Now I will not have any problem with the loan in the bank. Thank you, both of them.
Why this case matters
Because "Suit Filed" is the flag borrowers fear most — and this case documents the version nobody explains: the flag can outlive the debt. Dues cleared in April 2025 were still wearing a litigation label sixteen months later, failing loan checks a paid-up borrower should have passed. The removal took neither a lawyer nor a year: evidence of clearance, a correction demand to the lender, a parallel bureau dispute, and escalation the moment the queue stalled. It also documents a quiet failure mode worth checking on your own file — a lender holding a dead email address, so their "we informed the customer" never reached anyone. If a suit-filed or wilful-default remark is on your report, this is the exact service lane for it, and here is why the NOC you were handed is only half the job until the bureaus say the same thing.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
 By Michelle Juanita
Three delinquencies, two banks — one corrected rank
CMR 7 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad