Case studies · Personal · Bengaluru · RBI escalation
Home · Case studies · RBI escalation: wrong reporting corrected
The letter the bank asked for, and the escalation that undid it: 640 → 728
Background
Mr. Balsingh Shankarsingh Hajeri of Bengaluru came to us with a profile carrying multiple written-off and overdue accounts across different banks and institutions — his January 2026 CIBIL read 640. Each account was reviewed and worked individually: foreclosure and outstanding details obtained, options negotiated. On one account with IndiaBulls, where the outstanding was significantly high, negotiation brought the amount down to where the client could realistically clear it — and he did. Account by account, the profile was being repaired. Except one.
The account that would not correct
Mr. Balsingh had been paying Belgaum Rani Chennamma Bank on time — and the payments were not being reported correctly on his credit reports. When we first contacted the bank, corrections were assured. The reporting continued unchanged. In the same period, he applied to the same bank for a loan, and during that process the bank asked him to submit a letter stating that all his credit-related issues had been resolved, assuring him it would help the application. He trusted them and submitted it. The loan was rejected anyway — and the incorrect remarks stayed on his reports.
The loop
From then on, every complaint we raised met the same wall: the bank pointed to the letter the client himself had submitted — he had confirmed his issues were resolved, they said; the updates had already been made, they said. The reports said otherwise, month after month. The repeated assurances without correction put the client under real stress, and it became clear no amount of ordinary follow-up would break the loop. So we stopped following up — and escalated.
The escalation
The matter went to the Reserve Bank of India, laid out completely: the incorrect reporting against documented on-time payments, the sequence of assurances, the letter and how it was being used, and the impact on the client. Following the escalation, the bank reviewed the matter — and took corrective action: the reporting was corrected and updated accurately, while the other accounts we had been resolving individually were cleared and updated alongside.
The outcome
Corrections reflected across all four credit bureaus, and his CIBIL moved from 640 to 728 — documented below in his own report extracts, the Rani Chennamma account going from overdue reporting in January to closed at zero in June. What began as a pile of write-offs, overdues and one immovable bank ended as a clean, accurate profile.
Report evidenceView his reports — before and after+
Tap to compare the two reports
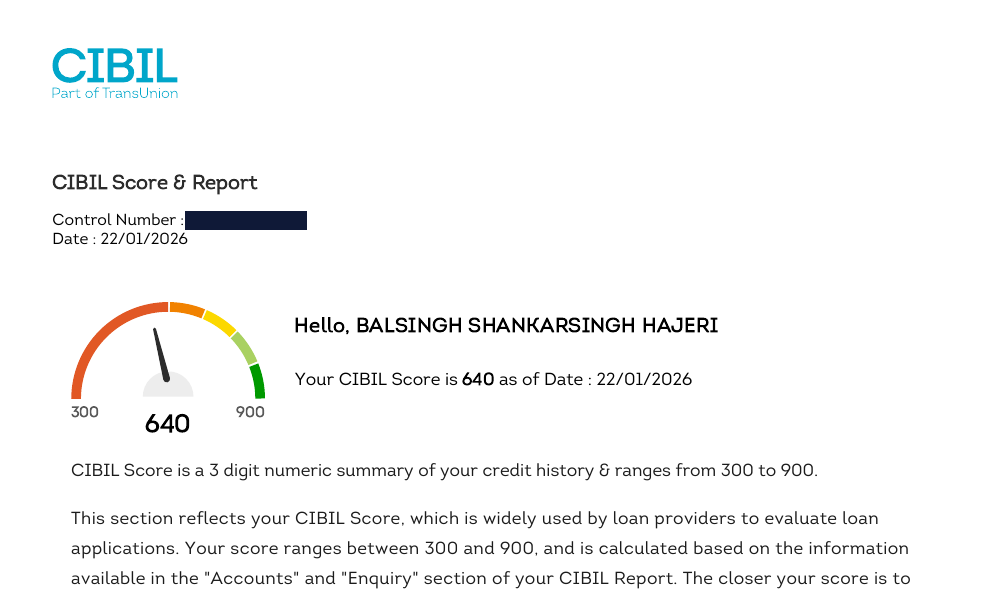
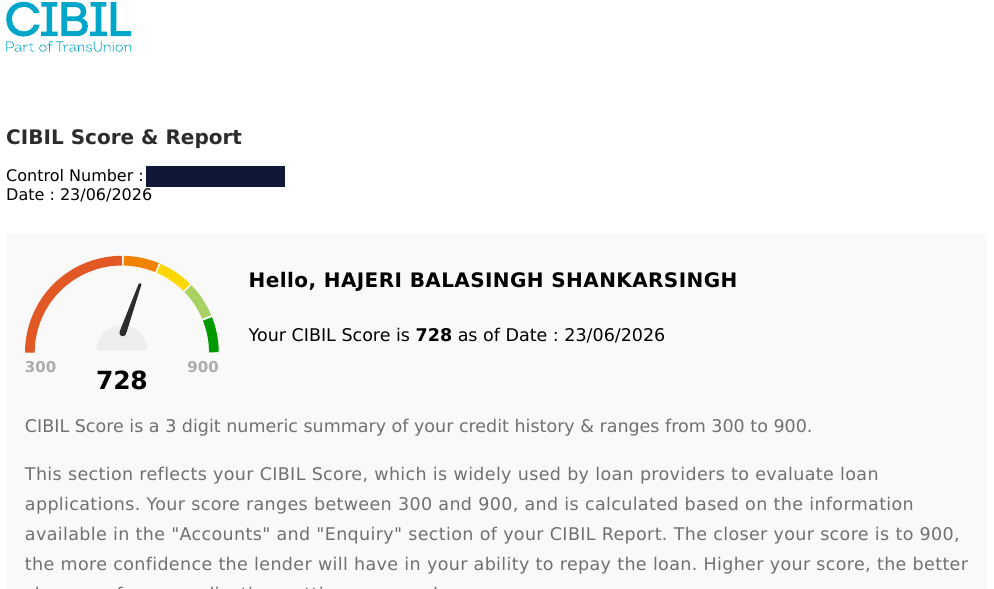
The Rani Chennamma Bank reporting — January versus June
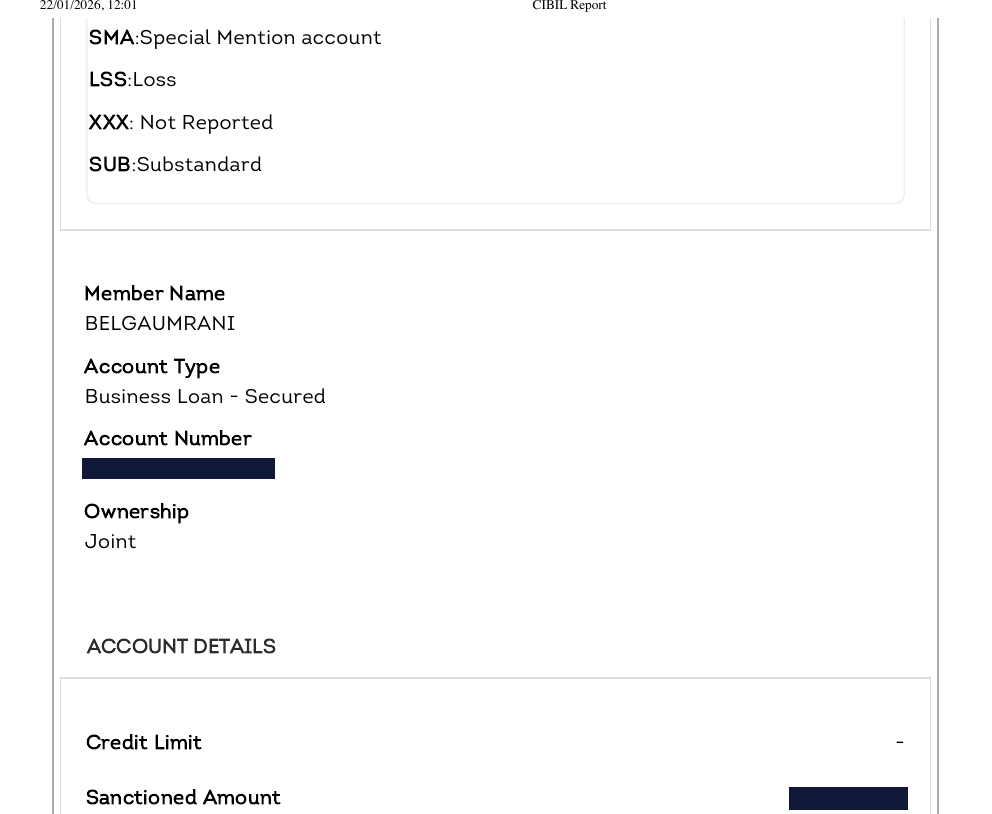
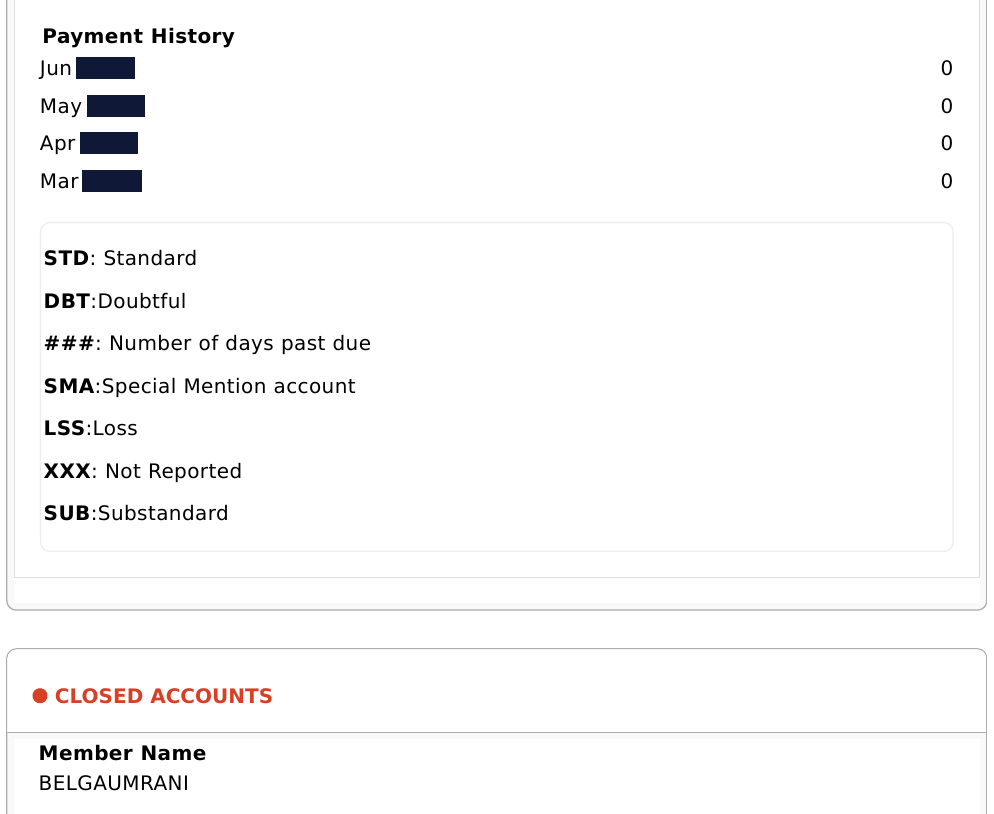
Raw extracts from Mr. Balsingh's own TransUnion CIBIL reports, labelled by report pull dates. Account numbers, amounts and identifiers are redacted; the institutions are named in this article. Published with his consent.
His testimonial, in his words
Recorded by Mr. Balsingh — 50 seconds, captions available. His transcript, verbatim:
Hello, Namaste. I would like to thank you Michelle for giving the great services. All four bureaus, whatever issues I had, it has been resolved very nicely, and all four credit bureaus have been cleared. And Michelle was very helpful whenever I had queries — she used to give us helpful information, and she attended all my queries and everything, and I'm very thankful to Michelle and team. So finally I have got all my issues resolved from Michelle and team, and all my four credit bureaus have been updated. I am very thankful to your services. Thank you very much.
Why this case matters
Because it documents a pattern every borrower should know before signing anything: never submit a letter stating your issues are resolved while they are not — whatever the assurance attached, a written confirmation in the lender's file can be read back against every future correction demand. And it shows the machinery that exists precisely for walls like this one: when a lender's assurances and its reporting tell different stories, the RBI escalation route compels the review that phone calls never will. Payments made on time are a matter of record; a report that says otherwise is a defect with a legal remedy — the full dispute-to-escalation playbook is here.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
By Michelle JuanitaThree delinquencies, two banks — one corrected rank
CMR 7 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad