
Background
Sharadamma and her family run a business in Manvi, in Karnataka’s Raichur district. They applied for a home loan and for an increase in their business overdraft limit. Both applications were turned down because of what their credit reports showed.
When they asked their bank, Union Bank, it said it was already reporting the account to the credit bureaus and that nothing more could be done from its side. They tried several times without getting anywhere, and then came to us.
What the analysis found
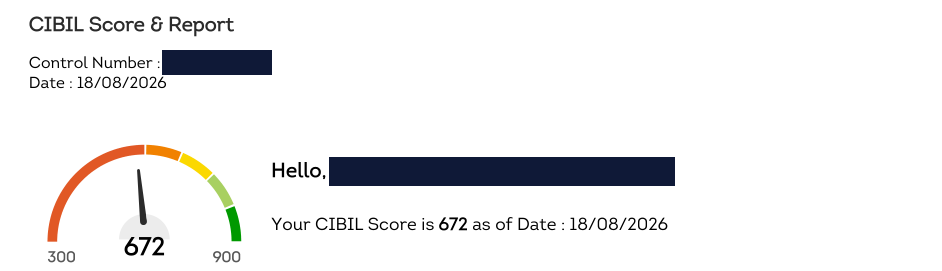
Supraja reviewed her reports from all four bureaus. The problem was amount overdue in the CIBIL report on one account that the bank had stopped updating. On her CIBIL report pulled on 18 August 2026 (score 672), the Union Bank overdraft, opened on 24 September 2015, held jointly and secured against property, read like this:
- Last reported: 31 December 2020. Nothing had been reported on it for more than five and a half years.
- Last payment shown: 30 November 2020, and the payment history stopped at December 2020.
- Amount overdue: the whole balance, about ₹32.7 lakh.
A lender reading that file saw a ₹32.7 lakh overdraft entirely overdue, with no sign of activity since 2020. The account had in fact stayed in use, but the report did not show it.
The approach
Because the family had a good relationship with the bank, Supraja started there. She collected the account statement up to date and sent the bank a formal email asking it to correct the reporting.
The first reply did not fix anything. Since the wrong reporting was holding up both the home loan and the overdraft increase, she escalated the matter and kept following up, by email and with the bank, until the account was reported correctly to CIBIL, Experian, Equifax and CRIF High Mark.
The dates on this page are report pulls, 18 August to 27 October 2026; they are evidence dates, not the dates the engagement began or ended.
The outcome
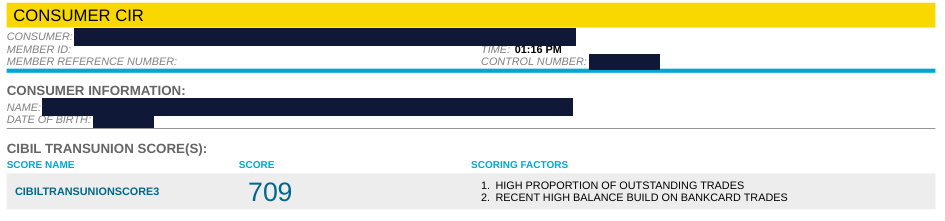
On her CIBIL report pulled on 22 September 2026 (score 700), Union Bank had re-reported the overdraft, certified on 23 August 2026: ₹0 overdue, last payment 31 July 2025, and a payment history filled in from September 2023 to August 2026. The report pulled on 27 October 2026 shows the same, with the score at 709.
On 27 October all four bureaus show the overdraft open and current with nothing overdue. Her scores that day were Experian 727, Equifax 766 and CRIF High Mark 674. We were not given earlier reports from those three bureaus, so we do not claim how much they moved.
Two honest notes. First, the new payment history is not spotless: May 2026 is reported at 39 days past due, and that stays, because it is accurate. Second, a separate Union Bank business loan from 2024 was 45 to 46 days late in July and August 2026, with about ₹40,500 overdue on the August report; it was brought up to date by September. That also helped the score, so we do not credit all 37 points to the overdraft correction.
Report evidenceCompare the before and after reports
Choose a report to view its extracts
CIBIL score and report date
Union Bank overdraft
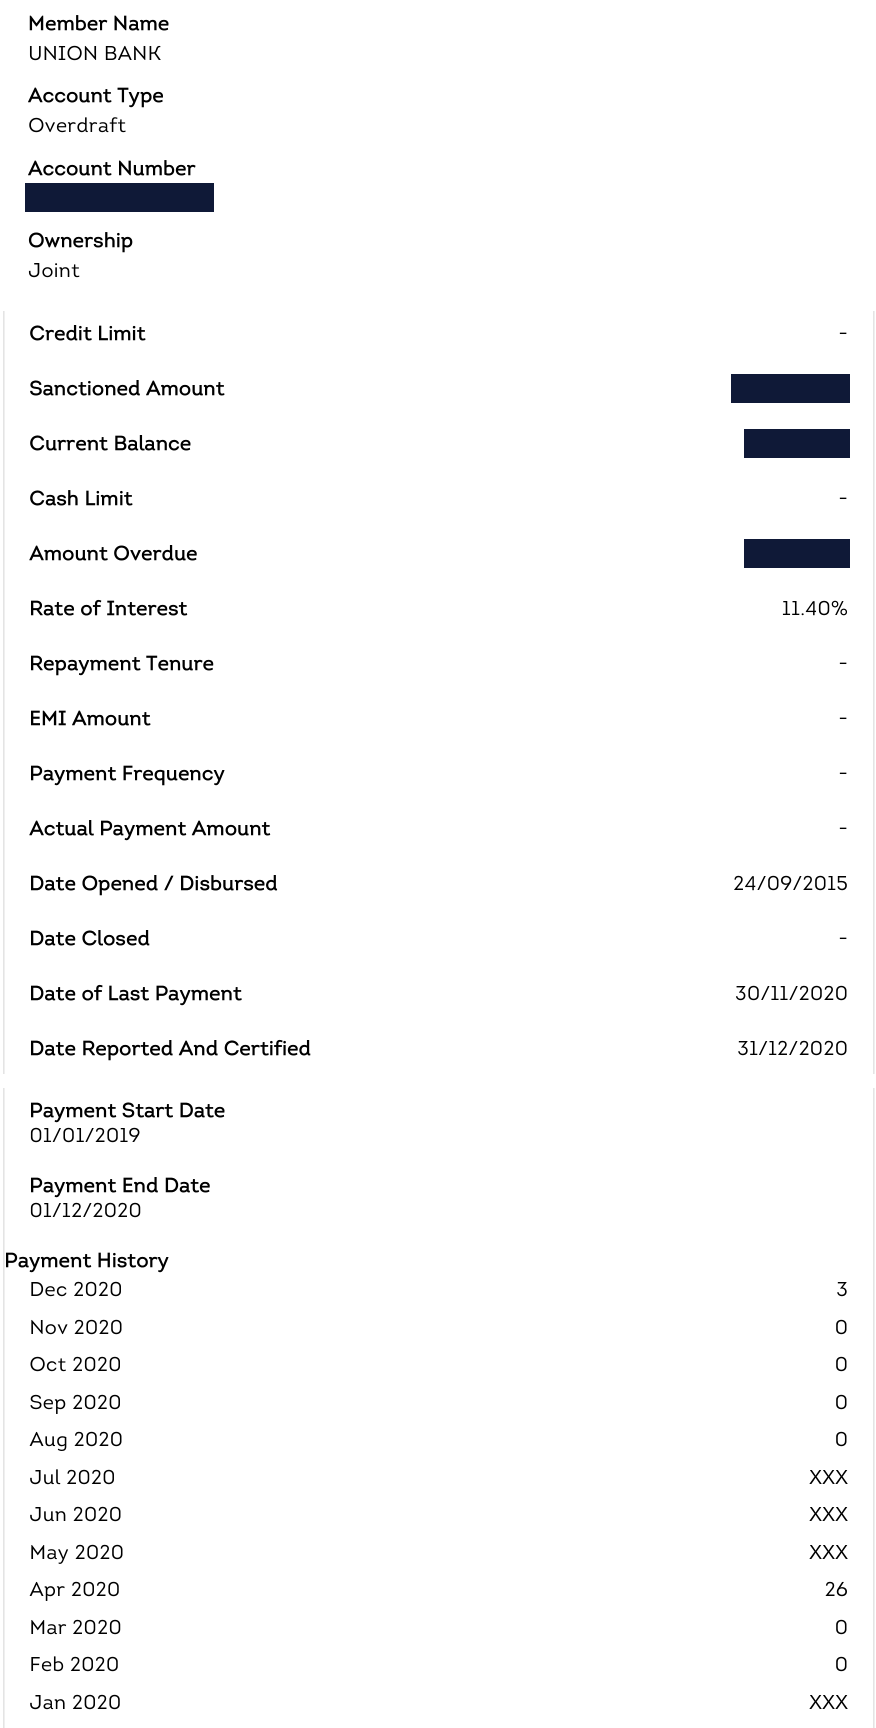
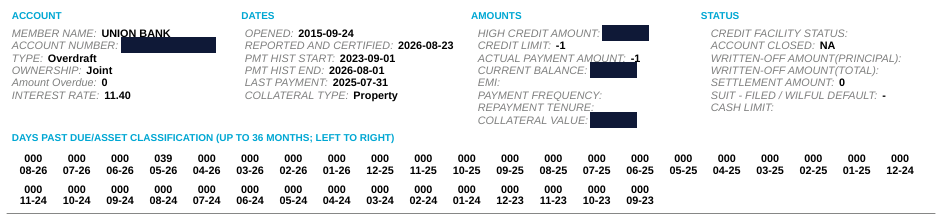
Crops from the client’s CIBIL reports, pulled 18 August and 27 October 2026. The before image stacks the overdraft’s header, details and payment history from the 18 August report; the after image is the same account’s block on the 27 October report. On the before report the amount overdue equals the whole current balance. Account numbers, amounts, the control number, her name and date of birth are redacted; dates, statuses, days past due and scores are as reported.
Her son’s review, in his words
Very good services and helped to improve credit score
Public Google review by her son, Karthik Patil, quoted as written · view the original screenshot →
Why this case matters
“We are already reporting it” is not the same as reporting it correctly. The bank was sending something to the bureaus; it just had not updated this account since 2020. Check the date reported and the amount overdue on every account, not only the score. Our guide on how to read a CIBIL report shows where to look.
Bring the statement, then keep going. An up-to-date account statement is what lets a lender correct its own reporting. When the first reply does not fix it, escalation is the next step, and the CIBIL dispute and escalation guide sets out the routes. Each bureau holds its own copy, which is why we check all four bureaus.
What is accurate stays. The 39-day month in May 2026 and the late months on her business loan are still on the report, because they happened. Accurate negative history cannot be removed. If your report shows an account the lender has stopped updating, our personal credit repair service gives you a written review before you pay.