Case studies · Business · Singampunari, Tamil Nadu
Home · Case studies · Commercial rank 7 to 3, DPD corrected
They offered to fix the record if the complaint was withdrawn. We asked for that in writing.

Two people worked this case. Both accounts appear below, in their own words.
How this case arrived
By Rabia Basri, Sr. Credit Consultant, Kenstone Credit.
The enquiry reached us through the website on a Friday, and it did not come from the borrower. It came from a bank manager who had handled this client's files for years. He had seen the commercial rank slip, the client had no idea it had happened, and he wanted it sorted before it cost the business a facility.
He was straightforward about his process. He had searched online, found several agencies, and sent enquiries to more than one of us. I called him back the same day.
He asked direct questions and I answered them without softening any of it: what a report can tell us, what nobody can promise, how an escalation actually works, and how long each stage realistically takes. He said what he wanted was a resolution, not an attempt.
My answer was that cases with this pattern come to us regularly and my confidence was high, and that our commitment does not sit on a phone call. It is written down. If we cannot deliver, the money goes back. That is the difference between buying a hope and buying a commitment, and it is the reason I never have to overstate anything.
Because it was a commercial report, he preferred not to forward it himself. With the client's authorization arranged through him, we pulled the report and shared the complete analysis: what was wrong, what could be corrected, what could not, and the timeline he could expect. After reading it he told me he had come to the right company.
I raised the proforma invoice. The enquiry had come on Friday and the payment was made on Monday. There was no negotiation over our fee, because there is nothing to negotiate. The price is published and it is the same for everyone.
Through the whole engagement the manager stayed our point of contact, and the case moved to Vaidhehi's desk.
How it was resolved
By Vaidhehi P, Sr. Credit Analyst, Kenstone Credit.
The challenge
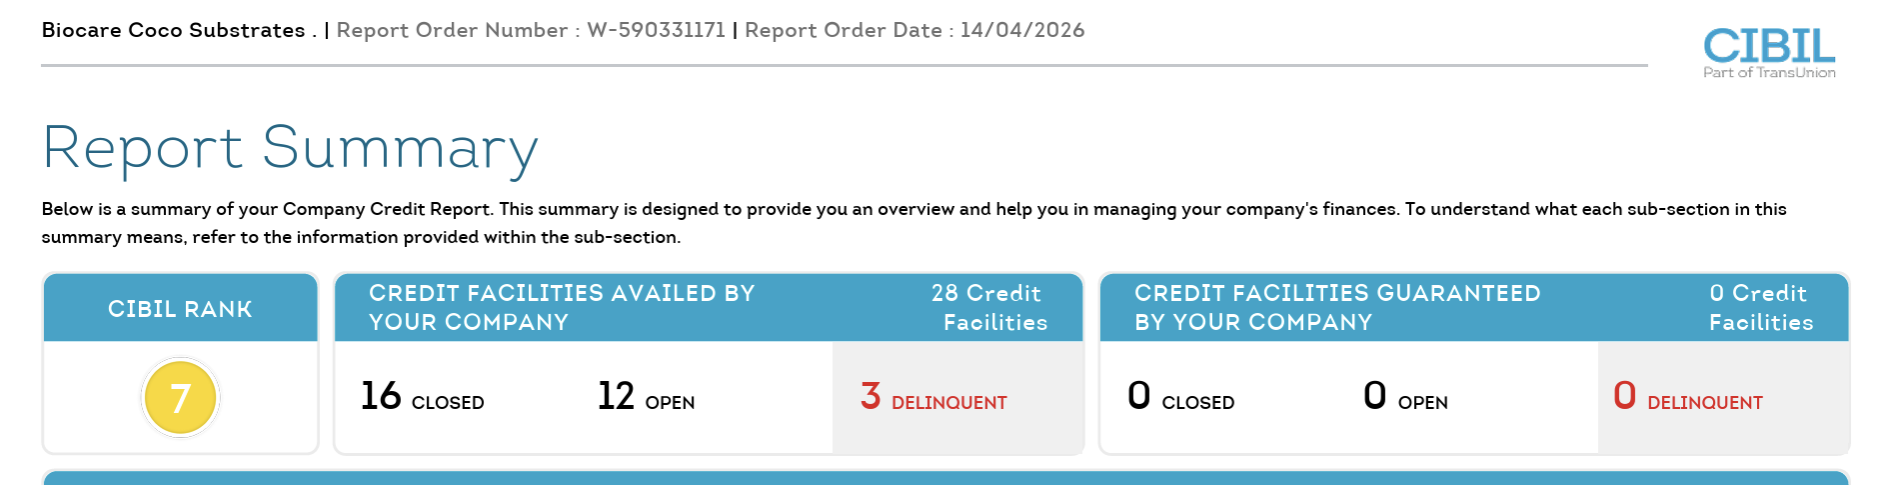
When the Biocare case was assigned to me, the commercial report showed a rank of 7, three delinquent accounts reported by the lender, and DPD information that was simply incorrect.
What I did first
I raised disputes for the incorrect DPDs through the regular process. The disputes were rejected. I escalated the matter through the PMO portal, and after that escalation two of the three accounts were corrected. One account still continued to reflect incorrect DPD, so I raised a second PMO escalation for the remaining account.
The critical moment
The customer then received a call from the lender saying they would remove the DPD only if the complaint was withdrawn.
To protect the customer's interests, I asked the lender to give that commitment in writing, by email. They refused to put anything in writing.
That refusal is the whole reason we did not withdraw. A correction promised on a phone call, with the complaint closed first, leaves a client with no record, no deadline, and no way back.
How I handled it
I spoke directly with the concerned representative and stated our position plainly. If the incorrect DPD was not corrected by 30 June, we would escalate the matter to the RBI. The complaint would state that the customer had been asked to withdraw the complaint before the correction was made. And we would seek appropriate compensation for the customer if required.
After that discussion, the representative agreed to resolve the issue and asked for time until 30 June.
The result
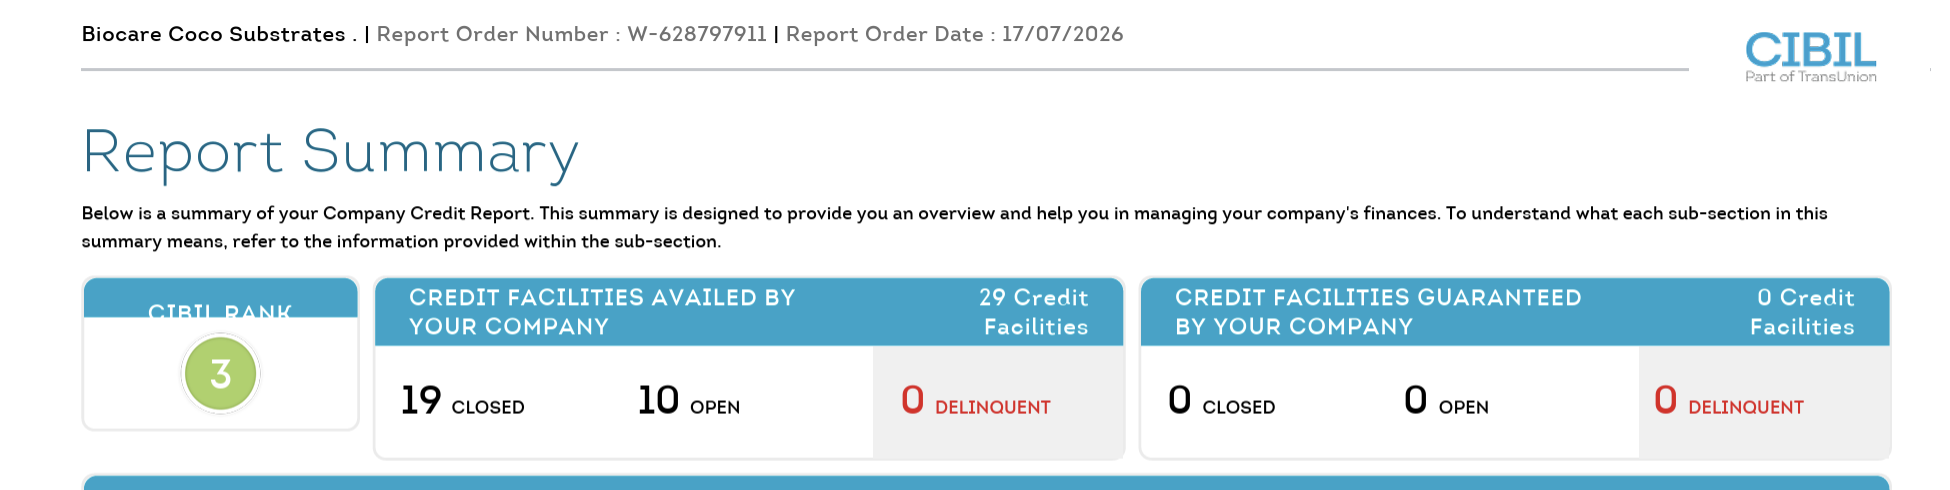
I refreshed the report on 3 July.
Report evidenceView the report — before and after+
Tap to compare the two reports
The three accounts, corrected






Same company, two commercial report pulls three months apart. The summary moves from rank 7 with 3 delinquent facilities to rank 3 with 0. Below it, the three disputed accounts: each header shows days past due before and after, and the lender's own last reported date advancing from 15 March to 30 June 2026, which is the lender re-reporting the corrected history at source. The lender's name, account numbers, balances and payment grids are not published. Excerpts shown with the client's written consent.
Why this case matters
Being asked to withdraw a complaint before the record is corrected is a request to give up the only leverage a borrower has. It may be offered in good faith. It may not. Either way, the client should never be the one carrying that risk, and a written commitment costs an institution nothing if it intends to keep it.
We kept the complaint open, set a date, and said exactly what the escalation would contain. The correction followed, and the rank moved from 7 to 3.
Dear Team,
Thank you for the prompt rectification of my CIBIL score issue. The entire process was very smooth and hassle-free.
My special thanks to Cabrini and Vaidehi Madam for being extremely helpful, supportive, and response the complete process.
Verified public review · view on Google →
Published with the client's written consent.
More documented cases
Different problems. Same standard.
Three banks, three errors — one commercial report corrected
SMA · not-theirs · stale BG — fixed
By Vaidhehi PThree delinquencies, two banks — one corrected rank
CMR 7 → 5 · 15 days
 By Akshatha Shetty
Commercial CIBIL rank 7 → 3 — and the funding that followed
3 lenders · AMC since
 By Kenstone Credit
Trust, twice: a wrongful "wilful default," then a stranger's gold loan
2 engagements
By Vaidhehi P