Case studies · Personal · Kasaragod, Kerala · settled status
Home · Case studies · Post Write-Off Settled cleared
He was told the loan was closed. The report said "Post Write-Off Settled" — and a 764 was rejected for it.

Background
Mr. K. S. Moideen Kunhi of Kasaragod, Kerala, had one line wrong on an otherwise strong report — and it was enough. His CIBIL stood at 764. His Kotak Prime auto loan had been settled, and at the time of settlement he was told the account was closed and there was nothing further to worry about. Then he applied to the bank for a new auto loan — and was rejected, because the report carried the status "Post Write-Off Settled": the label that tells every underwriter the account was closed for less than what was owed. He reached us through a chartered-accountant partner in Kerala who has referred several clients before him.
The first job was explaining what "Post Write-Off – Settled" actually means: not a closed account, but one the lender wrote off and then accepted less than the full dues on — a status that quietly follows a borrower into every future application. Nobody had told him that at the time of settlement. The second job was the harder conversation: clearing the remaining outstanding properly, instead of leaving the settlement standing, was the route that could actually change the record. He understood the difference between a settlement and a closure, agreed to clear the amount with Kotak, decided to avoid settlements in future — and signed up for the correction work the same day.
The correction — rejected first, then escalated
With the outstanding cleared, the account should have updated on its own. It did not — the status stayed "Post (WO) Settled" across bureaus. Disputes went to the bureaus requesting correction of the status; the dispute was rejected, and the label stayed. Rather than re-filing the same dispute for the same rejection, the matter went directly at the lender: a formal grievance against Kotak Prime through the PMO grievance portal, stating plainly that payment was complete and the reporting was still adverse, followed up continuously until the lender acted.
The outcome
The lender corrected the account and the update flowed to the bureaus. The 19 August report shows the Kotak Prime auto loan with its Credit Facility Status blank — no settlement, no write-off — documented below. His score barely moved (764 → 765), which is the whole point: the score was never the problem. One status line was, and it is gone.
Report evidenceView his reports — before and after+
Tap to compare the two reports
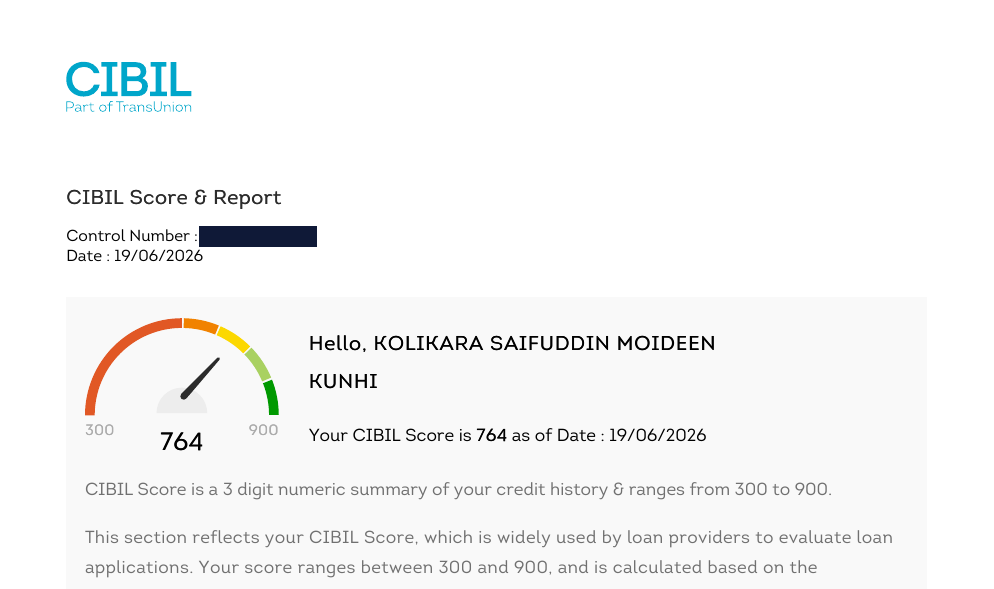
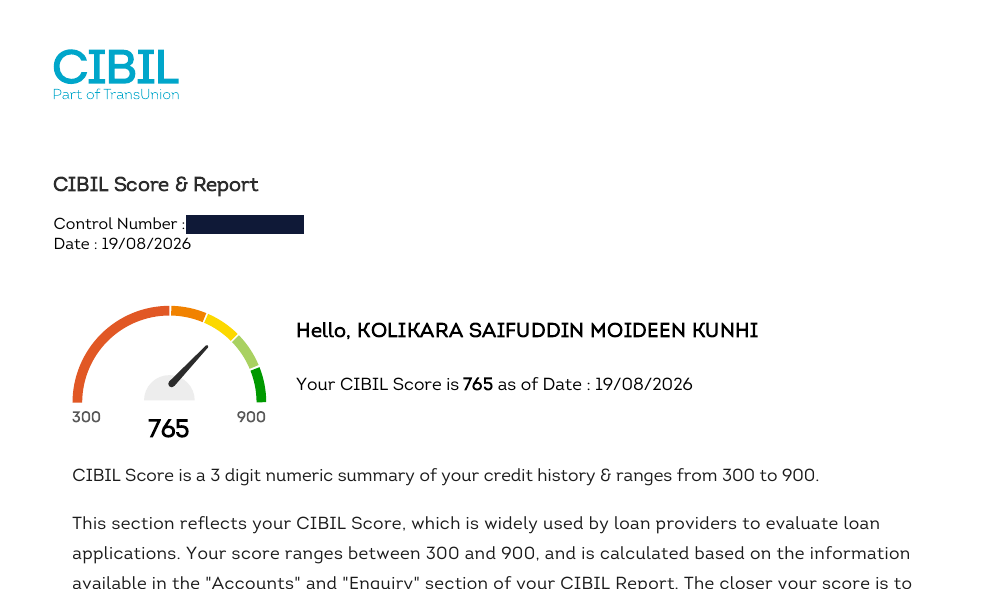
The Kotak Prime auto loan — the status field, June versus August
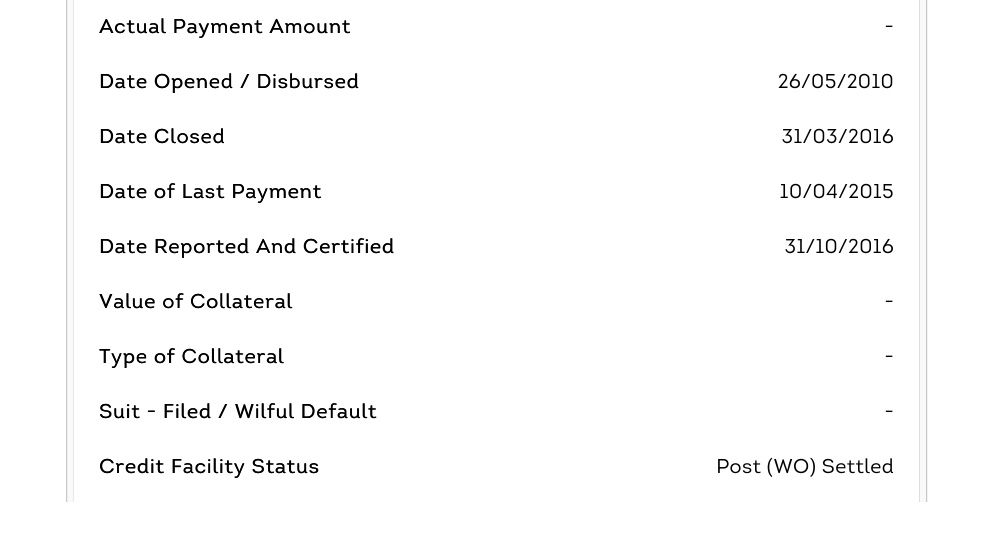
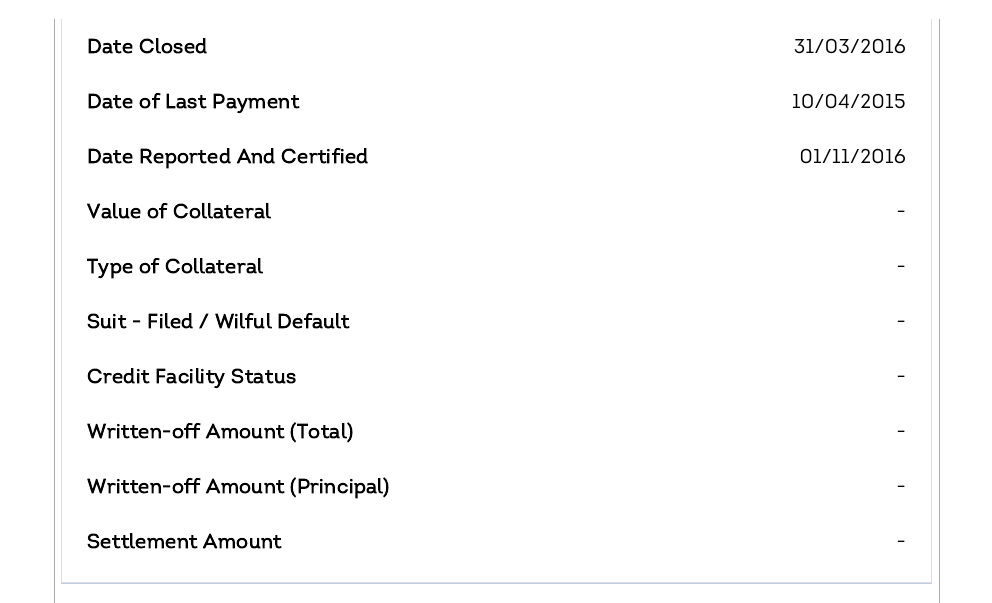
Raw extracts from Mr. Moideen Kunhi's own TransUnion CIBIL reports, labelled by pull dates. Account numbers, amounts and identifiers are redacted; the lender is named in this article. Published with his consent.
His testimonial, in his words
Recorded by Mr. Moideen Kunhi — 59 seconds, captions available. His transcript, verbatim:
Hi, I am Moideen Kolikara. I just want to thank you, Kenstone, for resolving my issue. You know, I just got a message from my bank that, you know, when I approached for a vehicle loan, that is something went wrong with my — all finance, I mean all vehicle loan which I already closed, but there is some, you know, comment is closed like settled, which is from one of my financial, which financed for my car. So I, I was just, you know, I was wondering how it happened, but I was very blind that, you know, how to resolve the issue, where to contact, whom to contact, and searching, searching, you know, finally I got Kenstone. You know, it was a good experience. I got the right vendor and, you know, all my issues resolved. Thank you very much, Kenstone.
It was great experience with kenstone capital regarding the loan closing issues resolved in all 4 parties including cibil and experian The Approach from your end was highly satisfied specially akshata and vaidehi Daily follow up from day one to until issues resolved favorably
Why this case matters
Because it is the third chapter of the one lesson borrowers most need and are least told: closure and clearance are different things, and the label knows the difference. Our Nellore case shows a client choosing closure with open eyes; our Hosur case shows a ₹254 clearance blanking a write-off; this case shows a settlement — accepted on the assurance that it was "closed" — converted into a clean record by paying the balance and then forcing the reporting to follow. Two further things worth keeping: a 764 gets rejected when one field says settled, so the score you check is not the file the bank reads; and a rejected bureau dispute is where the work starts, not where it ends — what a settlement really costs, and how to upgrade it, and the escalation ladder above the bureaus.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
 By Michelle Juanita
Three delinquencies, two banks — one corrected rank
CMR 7 → 5 · 15 days
By Akshatha ShettyA genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad