Case studies · Personal · Hosur, Tamil Nadu · written-off card
Home · Case studies · Seven-year write-off cleared
A write-off from seven years ago, over a few hundred rupees: cleared to a blank status, 625 → 700

Background
Mr. R. Boominathan of Hosur, Tamil Nadu, came to us with a CIBIL score of 625, an urgent loan requirement, and one clear, sensible goal: reach at least 700. The damage traced back nearly seven years — an Axis Bank credit card on which a small residual (in his own words, "some 1000 rupees") went unpaid while he was working abroad, unaware. Over the years that residual became a Written-off status with a days-past-due history in the hundreds: a few hundred rupees doing the reputational work of a defaulted loan. Harish Krishnamurthy took the first consultation and laid out the rectification route; the file then came to my desk for the analysis.
Step by step — and one plateau
The first dispute went to Axis Bank with the account's history laid out. Within about a week the classification moved from Written-off to Post Write-Off Closed, and the score jumped 625 → 675. The analysis then surfaced the number that decides everything in cases like this: the remaining total loan value was ₹254. He cleared it — and that single small payment changed the case from a closure into a full clearance, the path that blanks the status entirely rather than leaving a "post write-off" label behind. Follow-ups after payment moved the score 675 → 680 → 690. And then it sat at 690 for several weeks.
A plateau is information. Re-reading the profile pointed at the historical DPD reporting still weighing on the account, so multiple representations went to Axis seeking a review of the repayment history. In parallel, the other three bureaus were checked — and that review found something the client did not know: a legitimate loan account of his was missing from one bureau's profile, a positive line that should have been helping him. Corrective action went in for that too. Repair is not only removing what is wrong; it is also making sure what is right gets counted.
The outcome
Confirmation came that the disputed DPD reporting had been updated, and the score reached the number he had named on day one: 700. The 1 September report shows the Axis card with its Credit Facility Status blank, written-off amounts gone, closed on 22 July 2026 at ₹0 overdue — documented below. Roughly 40 days, a 75-point move, and the loan application he had been unable to file went through.
Report evidenceView his reports — before and after+
Tap to compare the two reports
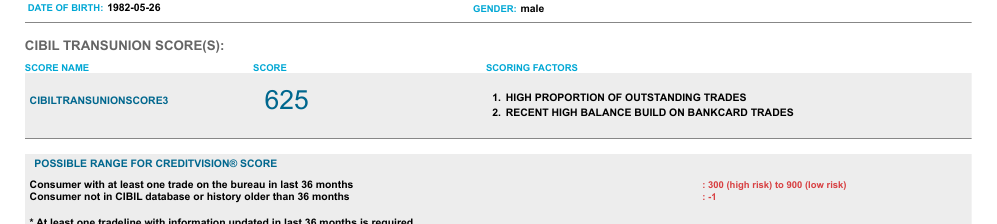
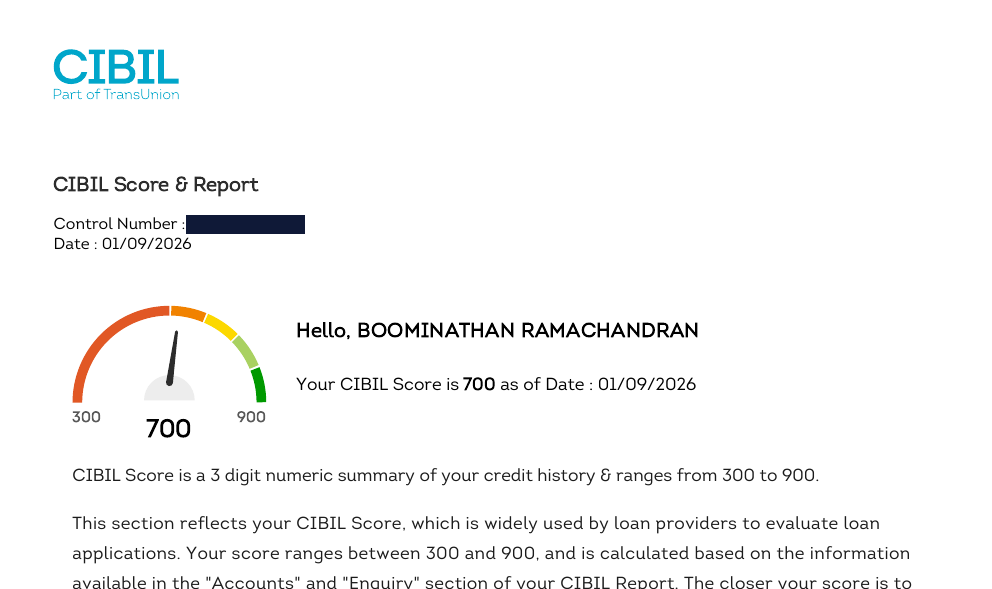
The Axis Bank credit card — written-off with a 900-day history in July; status blank and closed at zero in September
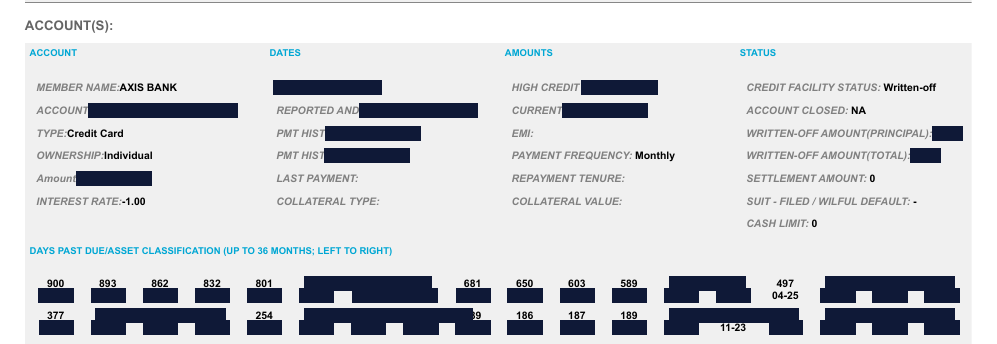
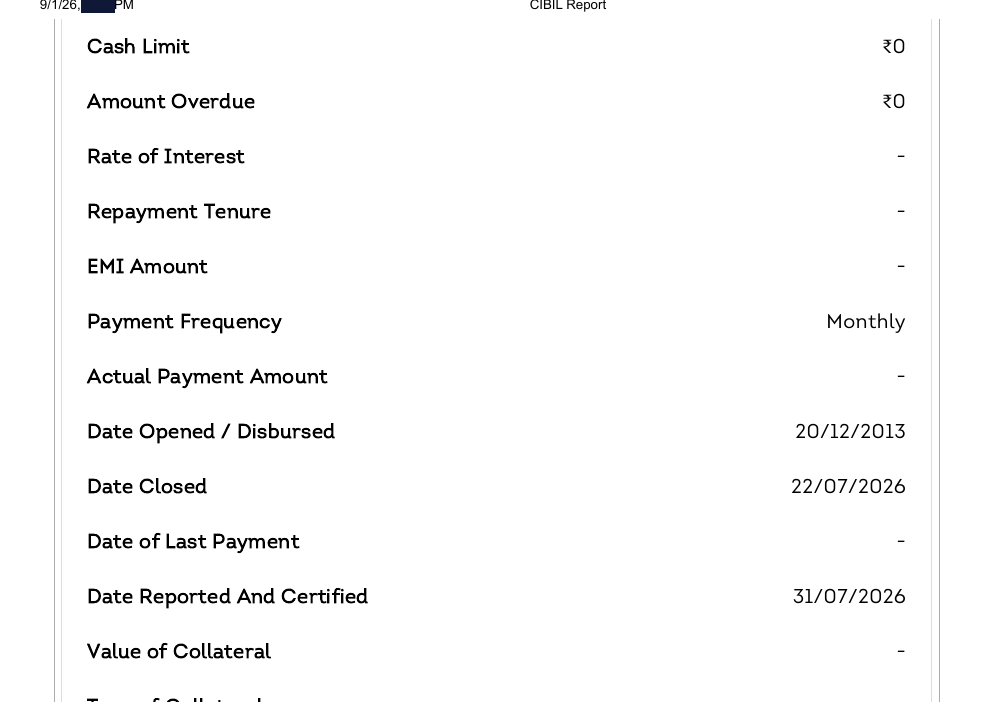
Raw extracts from Mr. Boominathan's own TransUnion CIBIL reports, labelled by pull dates. Account numbers, amounts and identifiers are redacted; the lender is named in this article. Published with his consent.
His testimonial, in his words
Recorded by Mr. Boominathan — 47 seconds, captions available. His transcript, verbatim:
Actually, I was facing issue when my credit score only 625, because it happened seven years back. I missed one of the due of the credit card. So now when I approached the loan, I was facing this issue due to the CIBIL score, then I approached Kenstone. They helped a lot, really nice customer service. They have approached proper channel, right, saying the dispute. Finally, my score went to 700. So now I was successfully able to apply the loan. I strongly suggest to go with Kenstone if you want to improve your credit score. Thank you.
Why this case matters
Three lessons, each documented above. Small residuals do not stay small: a forgotten few hundred rupees became a seven-year write-off with a 900-day history — the single most common origin story we see. Closure and clearance are different outcomes: our Nellore case shows a client choosing closure and keeping a "Post Write Off Closed" label by design; this case shows the other road — pay the total loan value, here ₹254, and the status goes blank. Same rule, opposite choices, both honest. And a plateau is a clue, not a ceiling: the 690 stall pointed straight at the DPD history and, on the way, at a positive account one bureau had lost. If an old write-off is standing between you and a loan, start with what the status actually means and what the upgrade path costs — then start with the analysis.
More documented cases
Different problems. Same standard.
Three lenders, four bureaus — one report finally telling the truth
737 → 790 · 40–45 days · ₹16L sanctioned
 By Smitha N
Stuck for a year — even with another agency. Closed in three months.
2–3 months · overdue removed
 By Michelle Juanita
Three delinquencies, two banks — one corrected rank
CMR 7 → 5 · 15 days
 By Akshatha Shetty
A genuine written-off account, resolved the honest way — in 14 days
14 days · NDC obtained · fully remote
 By Aradhana Prasad